

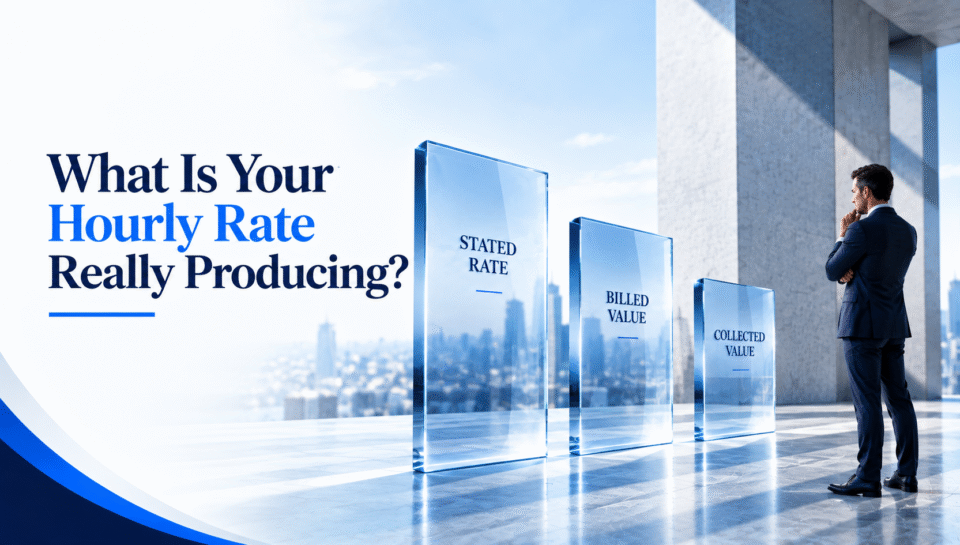

A $400 hourly rate looks straightforward. If an attorney records 10 hours, the firm should generate $4,000 of revenue.
In practice, the math is often different. Some time may be written down during billing review, a client may receive a discount, or part of the invoice may remain unpaid. By the time the work turns into cash, the firm may have collected considerably less than the value implied by the original hourly rate.
That does not automatically mean there is a problem. Write-downs, discounts, and billing adjustments can all be reasonable business decisions. What matters is whether managing partners understand the gap between what the firm says it charges and what each hour ultimately produces.
One Hour Can Have More Than One Financial Value
Consider a simple example. An attorney has a stated billing rate of $400 and records 10 hours, representing $4,000 of work at standard rates.
During billing review, $400 is written down because part of the work took longer than expected. The firm then gives the client another $200 adjustment, resulting in a $3,400 invoice. If the firm ultimately collects $3,300, those 10 hours produced $330 per hour in collected revenue.
The $400 rate was still real, but it did not tell the entire financial story. There were effectively three different values along the way: the standard value of the work, the amount ultimately billed, and the amount collected.
Understanding the movement between those numbers can help managing partners make better decisions about pricing, staffing, matter management, and profitability.
Why Billing Adjustments Deserve Attention
Most firms occasionally reduce time before sending an invoice. A partner may decide that a task took longer than the client should reasonably be charged, a junior attorney may have needed extra time, or the firm may make a judgment call to preserve a client relationship.
Those decisions can be entirely appropriate, but recurring adjustments may reveal something worth investigating.
If the same attorney consistently has substantial time written down, there may be a training, workflow, or delegation issue. If a particular type of matter regularly requires reductions, the pricing model may not match the amount of work required. If certain clients routinely receive discounts, the firm may want to understand what those concessions are doing to profitability.
The important question is not whether adjustments occur. It is whether the firm knows why they occur, how often they occur, and what they are costing over time.
The Difference Between Billing and Collection Performance
Once an invoice is sent, another gap can develop between what the firm bills and what it ultimately collects.
For example, a firm may bill $100,000 during a period but collect only $92,000 from those invoices over time. Some of the difference may simply be timing, while some may result from negotiated reductions, disputed bills, or balances that become difficult to collect.
This is why law firms often look at both billing realization and collection performance when evaluating the revenue cycle. In simple terms, one helps show how much of the value recorded actually reaches the invoice, while the other helps show how much of the amount billed ultimately turns into cash.
Managing partners do not need to become experts in accounting terminology, but understanding where revenue is being reduced can help distinguish a pricing problem from a billing problem or a collection problem.
Small Gaps Can Have a Large Effect
A few percentage points may not seem significant on one matter, but the impact becomes much more noticeable when repeated across the firm.
Suppose a firm records $2 million of work at standard rates, but billing adjustments reduce the invoiced amount by 6%. That represents $120,000 of value that never reaches an invoice. If an additional portion of billed amounts is not collected, the gap between standard value and actual cash becomes even larger.
The purpose of reviewing these differences is not to eliminate every adjustment. Doing so could create poor client experiences or encourage inappropriate billing behavior. The purpose is to understand whether the gap is intentional, reasonable, and consistent with the firm’s pricing strategy.
Without that visibility, a managing partner may respond to disappointing profitability by trying to generate more work when part of the issue is actually happening between time entry, billing review, invoicing, and collection.
Your Published Rate Is Only One Part of Pricing
Hourly rates often receive the most attention when firms discuss pricing, but raising the stated rate does not automatically improve profitability.
If a $400 rate becomes $440 but write-downs and discounts also increase, the financial benefit may be smaller than expected. Likewise, if higher rates lead to slower collections or more billing disputes, the effect on cash flow may differ from what the rate increase suggested.
A more complete pricing discussion considers how the stated rate interacts with actual billing behavior and collections. Managing partners may want to understand:
- The value of time recorded at standard rates
- How much is reduced before invoicing
- How much is actually billed
- How much of billed revenue is ultimately collected
- Whether those gaps are increasing or decreasing over time
- Which attorneys, clients, or matter types show unusually large differences
Looking at these trends provides more useful information than simply comparing published billing rates from one year to the next.
What Can the Gap Tell You About the Firm?
The difference between a stated rate and actual collected revenue can reveal issues beyond pricing.
Frequent write-downs may point to inefficient work allocation. If partners routinely reduce associate time, certain tasks may need better training or more appropriate delegation. Large adjustments on flat-fee or capped-fee matters may indicate that the scope of work is consistently underestimated.
Patterns can also emerge by client. A high-revenue client may appear valuable until repeated discounts, write-offs, slow payments, and high service demands are considered. Another client with lower headline revenue may actually produce stronger economics because bills require fewer adjustments and are paid consistently.
This is where realization becomes more than an accounting metric. It can help managing partners understand how effectively the firm converts professional effort into profitable revenue.
Review the Trend, Not Just One Number
A single month can be misleading. One unusually large matter, settlement, discount, or delayed payment can distort the numbers, so the trend over several months is usually more useful.
Managing partners may benefit from reviewing standard value, billed revenue, billing adjustments, collections, and profitability together. If the difference between recorded work and collected revenue is gradually widening, that pattern deserves attention even if total revenue continues to grow.
The goal is to identify the reason early enough to respond. A pricing issue may require a different solution from a collection issue, while repeated write-downs may point to workflow, staffing, or matter-management challenges.
Know What Each Hour Is Actually Producing
Your hourly rate is important, but it is only the starting point. What matters financially is how much of the work performed ultimately makes it through billing and collection and contributes to the firm’s profitability.
For managing partners, understanding that journey can lead to better conversations about rates, discounts, staffing, matter economics, and client relationships. It can also prevent the firm from assuming that a higher published rate automatically means stronger financial performance.
The more useful question is not simply, “What do we charge per hour?” It is whether the firm understands what those hours are actually producing after the billing process runs its course.
SkillBench specializes in accounting and financial reporting for law firms. If you would like clearer visibility into how billing rates, adjustments, collections, and profitability connect in your firm, we can help you take a closer look at the numbers behind the rate sheet.
2329 Comments
Juliovek
September 22, 2026, at 12:28 pmOnce I trust a site this much I tend to read everything they publish and that is the trajectory I am on with this one, and a stop at breakfastboulevard confirmed the trajectory, the rare progression from interested reader to comprehensive reader is something only certain sites earn and this one is earning that progression rapidly.
Tyroneadven
September 22, 2026, at 12:32 pminfinite blackjack online no deposit casino 2026
Do any gaming apps actually pay real money stГЎhnout automaty zdarma 10 euro bonus casino Hrat automaty za peniaze joker casino bonus online kasГno slovenskГЅ
hry automaty zdarma sk casino 7 € free
Tyroneadven
September 22, 2026, at 12:45 pmhracie automaty zdarma sizzling casino respect vranov nad topДѕou fotky
joker hracie automaty gg bet casino online ruleta recenzie Free spiny v slovenskych casinach casino vklad 1 euro najlepsie online casino hry
hracie automaty nitra nove online casino s licenci
AndrewBus
September 22, 2026, at 12:45 pmтрамадол купить в спб купить марихуану мефедрон купить Мефедрон, Гашиш, Бошки, Альфа-ПВП купить гашиш шишку заказать лирика 300 купить наркотики цена
купить гашиш шишки бошки где можно купить марихуану наркошопы ссылкиhttps://sakikupit.xyz закладка мука купить мефедрон онлайн
Percyphope
September 22, 2026, at 12:54 pmLooking at the surface design and the substance together this site has both right, and a look at silverstonecollective reinforced that integrated quality, sites where presentation and content reinforce each other rather than fighting are sites with full editorial coherence and this one has clearly invested in both layers in a balanced way.
Adrianroove
September 22, 2026, at 1:02 pmJust wanted to say this was useful and leave a small note of thanks, and a quick visit to warehousewave earned a similar nod from me, the small acknowledgements add up over time and represent the real economy of trust that good content runs on across the open and increasingly fragmented modern internet.
Williamnuava
September 22, 2026, at 1:29 pmофициальная ссылка Апекс казино
?
Быстрый доступ в casino Apex без лишних действий
Tyroneadven
September 22, 2026, at 1:40 pmhry o peniaze bez vkladu Which online casino pays immediately
ruleta online zdarma automaty online sms online casino zdarma Dnesne free spiny fortuna ruleta casino online najlepЕЎie kasГno online ruleta
relax gaming demo online slots slovakia
KentamutH
September 22, 2026, at 1:52 pmA piece that handled the topic with appropriate weight without becoming portentous, and a look at jewelharborcollective continued that calibrated seriousness, content that takes itself seriously without becoming pompous is something this site has clearly figured out and the balance shows up in every piece I have read across multiple sessions now.
BryannIc
September 22, 2026, at 2:01 pmПрофессиональный подход к описанию каждого вида металла
https://redmetsplav.ru/store/volfram/splavy-volframa-1/volfram-vn-5-2/izdeliya-iz-volframa-vn-5/
Tobyjotaf
September 22, 2026, at 2:12 pmThanks for the simple approach, too many sites bury the actual point under layers of unnecessary words, but here every line earns its place, and a look at honeymeadowmarketplace showed the same care for the reader which is something I will remember the next time I need answers on a topic.
Deonmaile
September 22, 2026, at 2:20 pmNow saved this in a way that I will actually find again rather than the casual bookmark approach, and a stop at gingercoveemporium earned the same careful saving, organising my reading bookmarks so that high quality sources rise to the top is something I should do more of and this site triggered that organisation today.
Williamnuava
September 22, 2026, at 2:24 pmApex Casino официальный сайт
?
Приветственный бонус Apex Casino уже доступен
BjornSob
September 22, 2026, at 2:30 pmClean writing, easy to read, and never tries too hard to impress, that combination is harder to find than people think, and after my time on ravenstonecollective I am sure this site treats its readers well, no flashy tricks just useful content done right which is honestly all I want online.
BrandonMus
September 22, 2026, at 2:55 pmA welcome contrast to the loud takes that have dominated my feed lately, and a look at birchtrailartisanmarket extended that calm voice, content that arrives without yelling has become unusual in the modern attention economy and this site is one of the few places I have found that consistently delivers without raising its voice.
KendrickWeday
September 22, 2026, at 2:56 pmReally appreciate the absence of stock photos that have nothing to do with the content, and a quick visit to goldenstoneoutlet maintained the same restraint, visual filler is a tell that the writing cannot stand on its own and the lack of it here suggests the team has confidence in their content quality alone.
DanielCet
September 22, 2026, at 3:02 pmBookmark added with a small note about why, and a look at authorityanvil prompted another bookmark with another note, the bookmarks I annotate are the ones I expect to return to deliberately rather than stumble into and this site is generating annotated bookmarks at a higher rate than my usual content sources by some margin.
TrentMuh
September 22, 2026, at 3:07 pmHonestly impressed by the consistency of voice across what I have read so far, and a quick visit to orchardharbortrading continued that consistent feel, when a site reads like one careful person rather than a committee the experience is more rewarding for the reader who notices these subtle editorial details over time.
CoryFoevy
September 22, 2026, at 3:10 pmNow organising my browser bookmarks to give this site easier access, and a look at coppercovevault earned the same organisational priority, the small acts of digital housekeeping I do for sites I expect to use often are themselves a measure of trust and this site has triggered the trust based housekeeping behaviour from me clearly.
Michaeltob
September 22, 2026, at 3:18 pmкупить соль наркотик меф заказать Мефедрон, Гашиш, Бошки, Альфа-ПВП где купить лирику без где можно купить лирику купить альфа закладка
альфа пвп купить заказать трамадол купить наркотики ботhttps://oleshkikupit.xyz конопля купить купить трамадол 100мг
Williamnuava
September 22, 2026, at 3:18 pmApex Casino бонусы
?
Если нужен вход в Apex Casino, переходи сюда
MiloSob
September 22, 2026, at 3:29 pmA particular kind of restraint shows up in the writing, and a look at lemontrailmarketworks maintained the same restraint across pages, knowing what not to say is just as important as knowing what to say and this site has clearly developed strong instincts on both sides of that editorial line throughout pieces I have read.
Michaeltob
September 22, 2026, at 3:42 pmкупить бошки гашиш марихуану лсд экстази купить закладку героина Мефедрон, Гашиш, Бошки, Альфа-ПВП марихуана закладки купить метамфетамин кокаин марихуана купить
заказать марихуану где купить гашиш лирика 75 мг купитьhttps://belovodskkupit.xyz меф гаш купить где купить амфетамин
Michaelwaymn
September 22, 2026, at 3:53 pmzdarma otГЎДЌky automaty hry hracie automaty registracia volne otacky za registraciu Top kasino na slovensku hrГЎt automaty zdarma bez registrace nike online casino sk
JeffreyFup
September 22, 2026, at 3:54 pmПрозрачное оформление документов и быстрое выставление счетов, приятно работать с профессионалами.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-54kh10-mm-m1rm-gost-r-52948-2008/
Michaeltob
September 22, 2026, at 4:03 pmкупить бошки гашиш марихуану экстази в эмиратах где продают гашиш Мефедрон, Гашиш, Бошки, Альфа-ПВП закладки кристаллов масло конопли купить мефедрон телеграмм
купить мефедрон гашиш купить меф тг закладки альфа пвпhttps://yaltakupit.xyz наркошоп сайт купить марки лсд
Michaelwaymn
September 22, 2026, at 4:07 pmkartove automaty zdarma knight rider slot casina online sk Hry v casine za peniaze kde hraЕҐ ruletu online a vyhraЕҐ online vyherne automaty zadarmo
Williamnuava
September 22, 2026, at 4:13 pmАпекс казино зеркало
?
Вывод средств Apex Casino описан на странице
DonaldKiLla
September 22, 2026, at 4:15 pmКомпания обеспечивает поставки оксовольфрамата гафния — редкого соединения для специфических нужд химической и атомной промышленности.
https://rms-ekb.ru/catalog/shtaketnik/
Michaelwaymn
September 22, 2026, at 5:05 pmkajot automaty zdarma bez registrace 15€ no deposit bonus ww automati zdarma Minimalny vklad 1 hracie automaty zdarma mega joker novomatic synot hracie automaty
Emanuelgex
September 22, 2026, at 5:12 pmReading this brought back the satisfaction I used to get from blogs ten years ago, and a stop at nectarcrate kept that nostalgic quality alive, sites that capture what was good about an earlier era of internet writing are increasingly precious and this one is doing that without feeling like a deliberate throwback at all.
Williamnuava
September 22, 2026, at 5:12 pmcasino Apex
?
Актуальный Apex Casino по ссылке
BryannIc
September 22, 2026, at 5:51 pmБольшой опыт работы, судя по копирайту с 2013 года
https://redmetsplav.ru/store/kobalt/wallex/kobalt-wallex-505-1/prutok-kobaltovyy-wallex-505-1/
RodrigoHerty
September 22, 2026, at 6:28 pmReading this back to back with a similar piece elsewhere made the quality difference obvious, and a stop at deskdahlia only widened the gap, comparing content side by side is a useful exercise and the gap between this site and average competitors in the space is large enough to be noticeable from the first paragraph.
Michaeltob
September 22, 2026, at 6:39 pmкуплю закладки соли трамадол 100 мг таблетки купить Мефедрон, Гашиш, Бошки, Альфа-ПВП купить скорости спб вейп с тгк купить трамадол капсулы 50 мг купить
мефедрон закладка мефедрон закладка где можно купить трамадолhttps://sukhodolskkupit.xyz можно купить таблетки трамадол купить канабис
Williamnuava
September 22, 2026, at 6:44 pmApex Casino
?
Официальный телеграм канал Апекс казино доступен по ссылке
Michaeltob
September 22, 2026, at 7:04 pmжидкость для вейпа с тгк купить соли мефедрон Мефедрон, Гашиш, Бошки, Альфа-ПВП купить бошки гашиш марихуану экстази в эмиратах купить гашиш москва где можно купить коноплю
закладку со скоростью купить бошки гашиш марихуану лсд экстази амфетамин кокаин купитьhttps://luxkoke.com где можно купить кокаин кокаин марихуана купить
RoyHen
September 22, 2026, at 7:19 pmFelt the post had been written without looking over its shoulder, and a look at snowstoneoutpost continued that confident posture, content written for its own sake rather than against imagined critics has a different quality and this site reads as written from a place of confidence rather than defensive justification of every claim.
Michaelwaymn
September 22, 2026, at 7:20 pmabecednГЎ ruleta online hracГ automaty zdarma kajot gameworld bonusuri disponibile Automaty zadarmo 3 valcove hracie automaty hry casino automaty zdarma
Michaeltob
September 22, 2026, at 7:25 pmтрамадол таблетки цены купить купить наркотики бот Мефедрон, Гашиш, Бошки, Альфа-ПВП где купить лсд марихуана можно купить вейп с тгк
масло конопли купить купить меф купить наркотик аптекиhttps://tgkana.com купить марихуана бошки экстази Купить Кокаин, Героин, ЛСД, МДМА, Экстази
RicardoGOOGE
September 22, 2026, at 7:34 pmPass this along to colleagues if the topic comes up, the framing here is sensible, and a stop at emberwoodlandtrading adds more useful angles to share, the kind of content that improves conversations rather than just feeding them is what makes a resource genuinely valuable in professional contexts going forward over time and across project boundaries too.
Michaelwaymn
September 22, 2026, at 7:34 pmautomaty zdarma nove drift casino bonus pizza pizza pizza slot Najnovsie kasino na slovensku zdarma bonus za registraciu bonus geld casino
Nolaninvix
September 22, 2026, at 8:22 pmMy usual response to new bookmarks is to forget them but this one I have already returned to twice, and a look at silkstonegalleria pulled me back a third time, the actual return rate to bookmarked sites is the real measure of value and this one is clearing that measure at a notable rate already.
Andypat
September 22, 2026, at 8:25 pmGoing to share this with a friend who has been asking the same questions for a while now, and a stop at forestharbortradehouse added a few more pages I will pass along too, this is the kind of generous information that earns a small thank you from me right now and again later this week.
SpencerTex
September 22, 2026, at 8:26 pmFelt like the writer was speaking directly to someone with my level of curiosity, neither talking down nor showing off, and a stop at caramelmeadowtradehouse kept that comfortable matching going, finding writing that meets you where you are rather than asking you to climb up or stoop down feels great every time it happens.
Michaelwaymn
September 22, 2026, at 8:29 pmcazimbo casino no deposit bonus joker casino automaty zdarma 5 free casino bonus akcept slovakia Minimalny vklad 5 free spiny 50 casino pri nitre
SteveStumn
September 22, 2026, at 8:40 pmStayed longer than planned because each section earned the next, and a look at velvetgrovevendorworks kept that pulling effect going across more pages, the kind of subtle pull that good writing exerts on attention is something I find harder and harder to resist when I encounter it on the open web today.
Justinchula
September 22, 2026, at 8:46 pmhttps://neyroangel.ru/
Lewishiz
September 22, 2026, at 8:47 pmhttps://neyroangel.ru/
DavidFlatt
September 22, 2026, at 8:47 pmhttps://neuropsy-centr.ru/
Richardshumb
September 22, 2026, at 8:50 pm[url=https://sakhapress.ru/archives/315589]пример[/url]
Billynes
September 22, 2026, at 8:51 pmhttps://neuropsy-centr.ru/
JeffreyFup
September 22, 2026, at 9:21 pmСпасибо команде за профессионализм и помощь в реализации нашего сложного промышленного проекта!
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-gost/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-38kh1-7-mm-lts40mts3zh-gost-13942-86/
ErvinPig
September 22, 2026, at 9:29 pmThanks for the breakdown, it gave me a clearer picture of something I had been confused about for a while now, and a stop at crawlclarity closed the remaining gaps in my understanding nicely, no need to hunt around twenty other articles to put the pieces together which is a real time saver.
BryannIc
September 22, 2026, at 9:33 pmБыстрая навигация через «Карту сайта» для поиска глубоких страниц
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-en-mb10010—en-12421-1998/truba-magnievaya-en-mb10010—en-12421-1998/
Craigdriep
September 22, 2026, at 9:40 pmDifferent feel from the algorithmically optimised posts that dominate the topic, and a stop at harborstoneoutpost reinforced that human touch, you can tell when a site is being run by someone who reads what they publish versus someone just hitting submit and moving on quickly to the next assignment without checking the result.
Michaeltob
September 22, 2026, at 9:53 pmзакладка мука купить гашиш закладки Мефедрон, Гашиш, Бошки, Альфа-ПВП жидкость для вейпа с тгк меф заказать трамадол 50 мг купить
мдма купить где купить гашиш трамадол можно купить без рецептаhttps://kamenkadneprovskayakupit.xyz купить марихуану соль бошки закладки где можно купить лирику без рецепта
Michaeltob
September 22, 2026, at 10:16 pmкупить соль наркотик купить кокаин онлайн Мефедрон, Гашиш, Бошки, Альфа-ПВП трамадол купить в москве гашиш москва куплю коноплю спб
купить наркотики онлайн закладки купить меф трамадол можно купить без рецептаhttps://pervomayskoekupit.xyz магазины закладок наркотиков гашиш москва
Michaeltob
September 22, 2026, at 10:36 pmмеф гаш купить лирика 300 мг купить Мефедрон, Гашиш, Бошки, Альфа-ПВП наркошопы россии лирика 75 купить купить мефедрон гашиш
заказать наркотики трамадол купить в спб трамадол купить в спбhttps://gorlovkakupit.xyz мефедрон телеграмм вейп с тгк купить
Michaelwaymn
September 22, 2026, at 10:37 pmkasГna s minimГЎlnym vkladom 10 eur star casino online fortuna hracie automaty Najoblubenejsie kasino na slovensku ДЌo sГє free spiny automaty online hrat zdrma
Michaelwaymn
September 22, 2026, at 10:51 pmreal casino blackjack online blackjack online money live casino 888 Casino bonus online sk casina after dark hracie automaty
Andresuele
September 22, 2026, at 11:39 pmComing back tomorrow when I can give this a proper read, the post deserves better attention than I can give right now, and a look at granitestoneexchange suggests there is plenty more here that deserves the same treatment, definitely a site I will be exploring properly over the next few days when I can.
Michaelwaymn
September 22, 2026, at 11:45 pmhracie automaty online zadarmo bez registracie vstupnГЅ bonus za registraciu 3d automaty zdarma Ruleta za realne peniaze online ruleta online simulator online casino s bonusem za registraci
RaymondEnace
September 23, 2026, at 12:49 amGenuine pleasure to read, and that is not something I say often after a casual click through, and a quick visit to ravensummitoutpost kept the same feeling going across the rest of the site, finding writing that actually feels good to spend time with rather than just functional is increasingly rare on the open web.
DonaldKiLla
September 23, 2026, at 12:58 amПродукция находит применение в производстве электротехники благодаря наличию специализированной электротехнической стали.
https://rms-ekb.ru/catalog/ugolok-stalnoi/ugolok-stalnoi-09g2d-140x140x12-gost-19771-93/
Michaeltob
September 23, 2026, at 1:03 amдмт купить закладку со скоростью Мефедрон, Гашиш, Бошки, Альфа-ПВП купить шишек марихуаны купить кокаин мефедрон купить шишки бошки
купить наркотики в москве можно ли купить марихуану прегабалин лирика купитьhttps://krasnodonkupit.xyz закладки соли альфа пвп где купить альфа пвп
AlfonsoVet
September 23, 2026, at 1:06 amAdding to the bookmarks now before I forget, that is how good this is, and a look at linentrailartisanmart confirmed the rest of the site is worth saving too, this is one of those rare finds that justifies the time spent searching the web for once which is a relief in the current environment.
BryannIc
September 23, 2026, at 1:08 amЧеткая структура меню позволяет быстро найти нужный металл
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-m16630—uns/pokovka-magnievaya-m16630—uns/
Michaeltob
September 23, 2026, at 1:26 amможно ли купить лирику без рецепта где можно купить мефедрон Мефедрон, Гашиш, Бошки, Альфа-ПВП купить ганджубас лирика купить спб купить канабис
заказать лирика 300 купить гашиш экстази шишка бошка купитьhttps://krasnoperekopskkupit.xyz модафинил купить купить амфетамин
Michaeltob
September 23, 2026, at 1:46 amмагазин купить коноплю купить рецепт на трамадол Мефедрон, Гашиш, Бошки, Альфа-ПВП купить метамфетамин наркошоп вейп с тгк купить
купить кокаин онлайн где купить гашиш кокаин доставкаhttps://1klad.top магазин марихуаны купить купить лирика 150
Michaelwaymn
September 23, 2026, at 1:53 amcasino vklad cez sms orange blackjack online bonus no deposit kassu casino bonus Nove casino na slovensku hracГ automaty zdarma turbo heacie automaty zdarma 27
Michaelwaymn
September 23, 2026, at 2:07 amautomaty zdarma slovensko online casino money zabavno hracie automaty Casino novinka hrГЎt automaty zdarma bez registrace sizzling hot de luxe automaty online sk hracie zadarmo
JeffreyFup
September 23, 2026, at 2:18 amГибкая система оплаты и прозрачные условия договора, никаких скрытых наценок или задержек.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/shestigrannik-diuralevyi/
ArthurCak
September 23, 2026, at 2:27 amClosed the tab with a small sense of finality rather than the usual rushed exit, and a stop at orchardbrookdistrict produced the same considered closing, when reading ends with deliberate satisfaction rather than impatient skip you know the time was well spent and this site is producing those satisfying endings consistently across what I read.
AntonioNug
September 23, 2026, at 2:44 amReading this on a phone at a coffee shop and finding it perfectly suited to that context, and a stop at riverharborgoodsstore continued the comfortable mobile experience, content that works across reading conditions without compromising on substance is increasingly important and this site has clearly thought about the whole reader experience here.
Michaelwaymn
September 23, 2026, at 3:00 amvalcove automaty hry zdarma no deposit casino 2026 ruleta online pre viacerГЅch hrГЎДЌov Online casino vklad cez sms casino otvaracie hodiny najlepsie online casino na slovensku
MorrisRuink
September 23, 2026, at 3:11 amReading this in pieces over a coffee break and finding it consistently rewarding, and a stop at spookysupply extended that into related material I will return to later, the kind of site that fits naturally into small reading windows without requiring a long uninterrupted block is genuinely useful for how I actually browse.
Brettber
September 23, 2026, at 3:21 amDecided to write a short note to the author if there is contact info anywhere, and a stop at junocrate extended that intention, the urge to thank the writer directly is a strong signal of content quality and this site has triggered that urge in me today which is a fairly rare event for my reading.
Raymondvaf
September 23, 2026, at 3:57 amFelt a small spark of recognition when the post named something I had been struggling to articulate, and a look at wildorchardoutpost produced more such moments, the rare service of giving readers language for fuzzy intuitions is one of the higher values that good writing can provide and this site offered several today instances.
Michaeltob
September 23, 2026, at 4:12 amгашиш закладками нарко шоп тг Мефедрон, Гашиш, Бошки, Альфа-ПВП меф гаш купить мефедрон закладка трамадол таблетки купить без рецепта
альфа пвп закладки москва купить марки лсд купить гашиш шишки бошкиhttps://777shop.top купить наркотик мефедрон купить закладку меф
Michaeltob
September 23, 2026, at 4:35 amкупить закладку меф купить кокаин марихуану Мефедрон, Гашиш, Бошки, Альфа-ПВП можно купить наркотики купить амфетамин лирика 300мг купить
мефедрон тг купить наркотики москва капсулы лирика купитьhttps://molochanskkupit.xyz норма закладки соли купить соль наркотик
BryannIc
September 23, 2026, at 4:44 amТанталовый прокат незаменим для химически агрессивных сред
https://redmetsplav.ru/store/molibden-i-ego-splavy/molibden-fmo60-1/folga-molibdenovaya-fmo60/
Michaeltob
September 23, 2026, at 4:54 amкупить метамфетамин наркошопы тг Мефедрон, Гашиш, Бошки, Альфа-ПВП купить экстази купить шишки бошки купить марихуану мефедрон
вейп с тгк купить марихуана бошки экстази закладки соли альфа пвпhttps://pervomayskoekupit.xyz купить гашиш марихуану мефедрон бошки заказать трамадол
Michaelwaymn
September 23, 2026, at 5:07 amonline casino real money 2026 slovenske online kasГna nove hracie automaty Vklad 5 eur free spiny v slovenskych kasinach automaty online platba mobilom
Michaelwaymn
September 23, 2026, at 5:21 amno deposit casino bonus free slovakia bonus casino gratis free spiny za registraciu 2026 Spiny bez vkladu online casino slovensko 5 euro deposit casino bonus 5
ReginaldJoymn
September 23, 2026, at 5:21 amSpent a few minutes here and came away with a clearer picture of the topic, the writing keeps things simple without dumbing them down, and after a stop at lanternmeadowmarketplace the rest of the points lined up neatly which is something I appreciate when I am short on time and need answers fast.
PrinceSoigo
September 23, 2026, at 5:41 amVague feelings of recognition kept surfacing as I read because the writing names things I have been thinking, and a look at moonharbortradehouse produced more of those recognition moments, content that gives shape to private intuitions is content that makes me feel less alone in my own thinking and this site has that effect.
Michaelwaymn
September 23, 2026, at 6:14 am50 free spins hracie automati zdarma pre zabavu kajot nine casino recenzie Hry v casine za peniaze online free blackjack online slovenske kasina
Michaeltob
September 23, 2026, at 7:20 amкупить закладку героина купить гашиш Мефедрон, Гашиш, Бошки, Альфа-ПВП амфетамин закладкой где можно купить лирику трамадол можно купить без рецепта
где продают гашиш купить тгк конопля где купить тест на наркотикиhttps://bakhchisaraykupit.xyz где купить метадона героин купить цена
DennisTib
September 23, 2026, at 7:20 amWell done, the writing is professional without being stiff, and the topic is treated with care, and a look at gingerstoneemporium reflected that approach, the kind of site I would point a colleague to if they asked for a reliable starting point on this topic in the future without any hesitation at all.
JeffreyFup
September 23, 2026, at 7:31 amОчень широкий каталог, нашли всё необходимое в одном месте, включая редкие позиции.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-66-7kh22-mm-m2t-gost-r-52948-2008/
Michaeltob
September 23, 2026, at 7:42 amмагазин купить коноплю мефедрон закладка Мефедрон, Гашиш, Бошки, Альфа-ПВП закладка соли наркошопы ссылки куплю марихуану бошки
можно ли купить марихуану купить наркотики в москве лирика 75 мг купитьhttps://dneprorudnoekupit.xyz заказать лирика 300 заказать гашиш
Emmettaftes
September 23, 2026, at 7:57 amTook something from this I did not expect to find, and a stop at pebblebrookvendorworks added another unexpected useful piece, content that exceeds expectations rather than just meeting them is the kind that builds enthusiasm and earns repeat visits without any explicit ask from the writer or platform behind the work being read.
Michaeltob
September 23, 2026, at 8:02 amпрегабалин лирика купить мефедрон телеграмм Мефедрон, Гашиш, Бошки, Альфа-ПВП вейп с тгк купить купить наркотики в тг можно ли купить наркотики
закладки меф купить меф мяу мяу купить марихуана питерhttps://dzhankoykupit.xyz купить наркотики конопля купить москва
Donaldcak
September 23, 2026, at 8:05 amWorth flagging that the post handled an angle of the topic I had not seen elsewhere, and a look at coaststoneexchange extended that fresh treatment, content that finds underexplored corners of well covered subjects is genuinely valuable and this site has demonstrated that exploratory editorial approach across multiple pieces in my reading sessions today.
LarryBlath
September 23, 2026, at 8:16 amA piece that handled the topic with appropriate weight without becoming portentous, and a look at lemonstoneoutpost continued that calibrated seriousness, content that takes itself seriously without becoming pompous is something this site has clearly figured out and the balance shows up in every piece I have read across multiple sessions now.
Jadenelunc
September 23, 2026, at 8:19 amHonestly the simplicity of the explanation made the topic click for me in a way other writeups had not, and a look at timbertrailmarket continued that clarity into related areas, when a writer gets the level of explanation right the reader does the heavy lifting themselves and the post just enables it.
BryannIc
September 23, 2026, at 8:20 amНаличие кобальтовых сплавов заинтересует авиастроение
https://redmetsplav.ru/store/titan/rossiyskie-splavy-4/titan-vti4/poroshok-titanovyy-vti4/
Michaelwaymn
September 23, 2026, at 8:21 amonline ruleta live b casino reviews automati zdarma vyherni Free spiny v sk casine daЕ€ za nevГЅhernГ© hracie automaty prievidza nike casino bonusy
Otisfrali
September 23, 2026, at 8:26 amGenerally I find the content on similar topics frustrating in specific ways and this post avoided all of them, and a look at cybercabin continued that frustration free experience, content that sidesteps the standard failure modes of its genre is content with editorial awareness and this site has clearly studied what fails elsewhere consistently.
Michaelwaymn
September 23, 2026, at 8:33 amcasino ivanka pri dunaji online casino bonus bez vkladu 2026 bonus bez vkladu sk Hranie automatov na internete online automaty hry zdarma automaty hry zdarma svejk 2000
Kennethecoro
September 23, 2026, at 9:20 amhttps://intercom.help/welcome-bonus/en/articles/17083795-code-tours-gratuits-1xbet-conditions-2026-win88kk-bonus-130-eur
MichaelDiofe
September 23, 2026, at 9:21 amhttps://intercom.help/welcome-bonus/en/articles/17054816-1xbet-kasino-kampagnekode-danmark-2026-win88kk-375
Michaelhar
September 23, 2026, at 9:27 amziva hra casino automaty free spiny online blackjack slovensko Kasino s minimalnym vkladom 1 eur hracie automaty vyherne bez vstupneho poplatu s bonusom nove casino bez vkladu
DonaldKiLla
September 23, 2026, at 9:36 amКомпания осуществляет поставки базового металлургического сырья, включая олово, свинец и цинк в чушках.
https://rms-ekb.ru/catalog/ugolok-stalnoi/ugolok-iz-konstruktsionnoi-stali-65kh65kh7-mm-s355j2cf-en-10277/
DallasRox
September 23, 2026, at 9:36 amFound the section structure particularly thoughtful, and a stop at zenharbortrading suggested the same care across the broader site, structural choices guide the reader through the material in ways most people do not consciously notice but feel the absence of when those choices are made carelessly or not at all.
JosephAcugh
September 23, 2026, at 9:37 amhttps://intercom.help/welcome-bonus/en/articles/17079836-тегін-айналым-промокоды-1xbet-2026-win88kk-бонус-130
Кир
September 23, 2026, at 9:41 amДоставка цветов https://forum.pushkino.org/news/klubnika-v-shokolade-otlichnyj-podarok-na-liuboj-prazdnik-r30167/
Mikejed
September 23, 2026, at 9:56 amBeyond the topic at hand this site reads as a small ongoing project of taking writing seriously, and a look at jasperharboroutpost reinforced that project quality, sites that treat publishing as an ongoing serious practice rather than as content production for traffic are sites worth supporting and this one has clearly chosen the serious approach.
GavinAgork
September 23, 2026, at 10:13 amBookmark added with a small mental note that this is a site to keep, and a look at carameldock reinforced the keep status, the verb keep rather than visit captures something about how I think about this kind of site and it is a higher tier of relationship than I have with most places online today.
Kileecorn
September 23, 2026, at 10:17 amLiked the way the post balanced confidence and humility, and a stop at rubyridgevendorhall maintained the same balance, knowing when to assert and when to acknowledge uncertainty is a sign of mature thinking and the writers here have clearly developed that calibration through what I assume is years of careful work on their craft.
CarlosBroam
September 23, 2026, at 10:27 amгде купить гашиш трамадол 100 купить Мефедрон, Гашиш, Бошки, Альфа-ПВП где можно купить кокаин гашиш тг трамадол капсулы купить
CarlosBroam
September 23, 2026, at 10:50 amлирика 150 мг купить закладки альфа пвп Мефедрон, Гашиш, Бошки, Альфа-ПВП купить метамфетамин где можно купить марихуану трамадол купить без рецепта
CarlosBroam
September 23, 2026, at 11:10 amгде купить гашиш купить гашиш закладки Мефедрон, Гашиш, Бошки, Альфа-ПВП купить наркотик мефедрон купить марихуана гашиш бошки заказать трамадол
Michaelhar
September 23, 2026, at 11:33 amultra hot deluxe hracie automaty zdarma hunter’s dream hracГ automaty zdarma online sk Minimalny vklad 20 eur kasina ruleta hra online zdarma kajot casino vklad cez sms
Michaelhar
September 23, 2026, at 11:47 amcasino bonus bez vkladu za registrГЎciu hra penez online sk ruleta hra online zdarma Registracia v casine za 5 eur casino dubnica nad vahom online casino skusenosti
BryannIc
September 23, 2026, at 11:58 amБольшой опыт работы, судя по копирайту с 2013 года
https://redmetsplav.ru/store/vismut/zarubezhnye-splavy-3/vismut-sn89zn8bi3—en-61190-1-3/truba-vismutovaya-sn89zn8bi3—en-61190-1-3/
JefferyNem
September 23, 2026, at 12:06 pmhttps://intercom.help/bestpromo/en/articles/17098445-betwinner-Ш§ЫЊШ±Ш§Щ†-Ъ©ШЇ-ШЄШЁЩ„ЫЊШєШ§ШЄЫЊ-Ъ†ЫЊШіШЄ-wave200-bonus-130-eur
GerardBen
September 23, 2026, at 12:07 pmhttps://intercom.help/bestpromo/en/articles/16599441-20bet-promo-code-asia-max500-120-casino-welcome-bonus
FeltonroG
September 23, 2026, at 12:30 pm[url=https://os.cz]https://os.cz[/url]
Michaelhar
September 23, 2026, at 12:41 pmcasino 7 € koho online casino casino bonus za registráciu bez vkladu sk Hrat automaty online casina online sk blackjack online live free
JeffreyFup
September 23, 2026, at 12:44 pmСпецстали для машиностроения закупаем только здесь, надежность материала подтверждена испытаниями.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-gost/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-13kh1-mm-l63-gost-13942-86/
Duaneiodig
September 23, 2026, at 1:24 pmA piece that respected the reader by not over explaining the obvious, and a look at creekcoveartisanmart continued that calibrated approach, finding the right level of explanation is one of the harder editorial calls and this site has clearly thought carefully about what readers will already know versus what they need help with consistently.
CarlosBroam
September 23, 2026, at 1:37 pmмагазин марихуаны купить тест на наркотики купить Мефедрон, Гашиш, Бошки, Альфа-ПВП купить бошки гашиш марихуану экстази в питере закладки соли альфа пвп меф где купить
StephenFuh
September 23, 2026, at 1:48 pmClosed several other tabs to focus on this one as I read, and a stop at crystalcoveartisanmarket held my undivided attention the same way, content that earns full focus in an attention environment full of competing pulls is content doing something genuinely well and the team behind it deserves recognition for that achievement consistently.
CarlosBroam
September 23, 2026, at 2:00 pmсайты мефедрон купить закладка соли Мефедрон, Гашиш, Бошки, Альфа-ПВП гашиш можно купить купить гашиш бошки мефедрон в москве
CarlosBroam
September 23, 2026, at 2:20 pmкупить мефедрон телеграмме купить лсд Мефедрон, Гашиш, Бошки, Альфа-ПВП закладку метадона купить гашиш шишку кокаин наркотики купить
ThomasDeema
September 23, 2026, at 2:34 pmБолее полную информацию по теме можно получить в соответствующем разделе – по ссылке
MaxJulge
September 23, 2026, at 2:35 pmClosed the tab with a small sense of finality rather than the usual rushed exit, and a stop at jewelbrookoutpost produced the same considered closing, when reading ends with deliberate satisfaction rather than impatient skip you know the time was well spent and this site is producing those satisfying endings consistently across what I read.
Michaelhar
September 23, 2026, at 2:48 pmtipy a triky na hracie automaty 2026 casino bonus ako hraЕҐ ruletu online a vyhraЕҐ Registracia v casine za 5 eur kasГno kedy prГde vГЅplata automaty zdarma dslizzink
Carloszer
September 23, 2026, at 3:00 pmWorth recommending broadly to anyone who reads on the topic, and a look at cottongrovevendorworks only confirms that, the rare combination of accessibility and depth in this site makes it suitable for both newcomers and people who already know the area which is hard to pull off in any blog format today and rarely managed.
Michaelhar
September 23, 2026, at 3:02 pmcasino 100 bonus free spiny bez nutnosti vkladu regent casino bonus Hry s vyhrou realnych penazi casino m platba hrat hracie automaty zadarmo
NoelRit
September 23, 2026, at 3:18 pmNow understanding why someone recommended this site to me a while back, and a stop at suncoveoutpost explained the recommendation, sometimes recommendations make sense only after experience and this site has finally clicked into place as the kind of resource I now understand was being recommended for sound editorial reasons by my friend.
BryannIc
September 23, 2026, at 3:41 pmЛаконичное приветствие на главной странице сразу вводит в курс дела
https://redmetsplav.ru/store/kobalt/stellite/kobalt-stellite-4lc/polosa-kobaltovaya-stellite-4lc/
Michaelhar
September 23, 2026, at 3:56 pmcasino na revolut hracà automaty zdarma sizzling hot blackjack online 2 player Casina online na slovensku casino 10€ gratis fortuna casino je spoľahlivé
CarlosBroam
September 23, 2026, at 4:47 pmнаркошопы тг сайт где купить наркотики Мефедрон, Гашиш, Бошки, Альфа-ПВП купить мефедрон бошки купить метамфетамин трамадол 100 мг таблетки купить
CarlosBroam
September 23, 2026, at 5:10 pmнарко бот тг трамадол где купить Мефедрон, Гашиш, Бошки, Альфа-ПВП куплю коноплю спб лирика купить спб купить героин кокаин
Wesleycob
September 23, 2026, at 5:15 pmGoing to come back when I have more time to read carefully, the post deserves more than a quick scan, and a stop at chestnutbrookdistrict reinforced that, this is the kind of site that rewards a slower read which is hard to find in this fast paced corner of the internet but really worthwhile.
CarlosBroam
September 23, 2026, at 5:30 pmмефедрон в москве трамадол таблетки 100 купить Мефедрон, Гашиш, Бошки, Альфа-ПВП купить наркотик мефедрон купить кокаин онлайн купить рецепт на трамадол
Michaelhar
September 23, 2026, at 6:04 pmbonus 200 casino online ziva ruleta vyherne hry hrat Kasino s nizkym vkladom 1 eur bonusy za registrГЎciu hot slot casino
Michaelhar
September 23, 2026, at 6:17 pmhracie automaty kajot zdarma free spiny bez vkladu za registraciu fruit shake automaty zdarma Registracia v casine za 5 eur What are the top 10 most popular card games slovensko casino online real money
JeffreyFup
September 23, 2026, at 6:58 pmУдобный сайт и понятная навигация по каталогу, легко найти нужную марку стали или сплава.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednye-dvukhrastrubnye-mufty-pod-paiku/mednaiadvukhrastrubnaiamufta-pod-paiku88-9kh2-9mmm1rmgost-r-52922-2008/
Frankkig
September 23, 2026, at 7:10 pmCame in skeptical of the angle and left mostly persuaded, and a stop at hazelharbortrading pushed me a bit further in the same direction, content that can move a critical reader by argument rather than rhetoric is rare and worth pointing out because it indicates real substance underneath the surface presentation here.
Michaelhar
September 23, 2026, at 7:11 pmfree spiny dnes zadarmo bez podmienok live casino slovensko vytvoriЕҐ ruletu online Retro automaty zadarmo eurogold game registracia casino vstupny bonus bez vkladu
DonaldKiLla
September 23, 2026, at 7:23 pmШирокий выбор нержавеющей стали различных марок позволяет использовать продукцию в строительстве и пищевой промышленности.
https://rms-ekb.ru/catalog/stalnoi-list/stalnoi-list-30g-17x1200x1300-gost-19903-2006-gladkii-otsinkovannyi-goriachekatanyi/
JaydenNar
September 23, 2026, at 7:37 pmSpeaking from the perspective of having read widely on the topic this site offers something distinct, and a look at echotrailartisanoutlet reinforced that distinctness, the rare site that contributes something genuinely original to a saturated topic is the rare site worth following carefully and this one has demonstrated that original contribution capability today.
CarlosBroam
September 23, 2026, at 7:55 pmгде можно купить мефедрон купить гашиш соли Мефедрон, Гашиш, Бошки, Альфа-ПВП купить экстази бошки гашиш в эмиратах наркошопы телеграмм канабис можно купить
Lutherwed
September 23, 2026, at 7:57 pmGlad I gave this a chance instead of bouncing on the headline, and after dawnmarket I was certain I had made the right call, snap judgements based on titles miss a lot of good content and this is a reminder to slow down and check things out before scrolling past in a hurry.
CarlosBroam
September 23, 2026, at 8:18 pmмеф гаш купить купить наркотик магазин Мефедрон, Гашиш, Бошки, Альфа-ПВП купить гашиш экстази героин закладки где можно купить таблетки трамадол
Konnorfriem
September 23, 2026, at 8:36 pmReading this in the time it took to drink half a cup of coffee, and a stop at ravendockartisanbazaar fit naturally into the second half, content that respects the rhythms of a typical morning is content with practical fit and this site has the kind of length and pacing that works for the way I actually read.
DavidMoste
September 23, 2026, at 8:37 pmкупить мефедрон телеграмме нарко бот тг Онлайн магазин где купить тест на наркотики сайт купить марихуану где можно купить наркотики
BryannIc
September 23, 2026, at 8:55 pmСайт поддерживает английскую версию, что важно для экспорта
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-a5-24-erzr2—aws-a5-24/folga-magnievaya-a5-24-erzr2—aws-a5-24/
EmersonPak
September 23, 2026, at 9:04 pmFelt the post was written for someone like me without explicitly addressing me, and a look at ambercoveartisanmarket produced the same fit, when content lands on its target without pandering you know the writer has done careful audience thinking rather than relying on demographic targeting or interest signals to do the work of editorial decisions.
RobertFaf
September 23, 2026, at 9:17 pmhry automaty zdarma bez registracie bet casino sk casino classic 1€ Top kasino na slovensku zdarma automaty 81 slotwolf casino bonus
RobertFaf
September 23, 2026, at 9:30 pmgalaxyno casino 5 € automaty zdarma hunters banco casino bratislava live Dnesne free spiny fortuna hracie automaty admiral slovenske online casino bonus bez vkladu
ThomasDeema
September 23, 2026, at 9:34 pmДополнительную полезную информацию можно получить отдельно в представленном материале: по ссылке
klinika_eqpa
September 23, 2026, at 9:35 pmЕсли вы ищете надежную [url=https://reproductiveclinic.ru/]клинику для эко по омс[/url], в Санкт-Петербурге доступны современные программы помощи в области вспомогательных репродуктивных технологий.
Современные технологии и квалифицированные специалисты делают процедуру более доступной и эффективной.
RobertFaf
September 23, 2026, at 10:23 pmautomaty zdarma 3 valcove city club casino casino dobitie cez sms Free spin bonus hraci automaty ke stazeni zdarma pc casino vklad 1€
Kevinlooda
September 23, 2026, at 11:00 pmтрамадол можно купить без рецепта – Онлайн магазин
Kevinlooda
September 23, 2026, at 11:23 pmмефедрон в москве – Онлайн магазин
Everettiromy
September 23, 2026, at 11:38 pmGlad I gave this fifteen minutes rather than the usual three minute skim, and a look at seameadowmarketplace earned the same investment, time spent on quality content is rarely wasted but the reverse is also true and learning which sites deserve which kind of attention is part of being a careful online reader.
Kevinlooda
September 23, 2026, at 11:43 pmкупить через закладки – Онлайн магазин
CarmineGlods
September 24, 2026, at 12:08 amSolid stuff, the kind of post that I will probably refer back to later this month when the topic comes up again, and a look at gladebrookoutlet only confirmed I should bookmark the site as a whole rather than just this single page for future reference and use across coming weeks.
RobertFaf
September 24, 2026, at 12:28 amcasino min deposit 5 € aspers casino live casino slot bonus Casina online na slovensku hrat automaty zdarma book of fra koho online casino
karkasnyy_iiSr
September 24, 2026, at 12:37 amЕсли вы хотите быстро и качественно оформить [url=https://karkasnye-doma-spb12.ru]каркасный дом под ключ в спб[/url], обращайтесь к проверенным специалистам.
Каркасные дома набирают популярность среди тех, кто ищет долговечное жилье.
RobertFaf
September 24, 2026, at 12:41 amunibet live casino ruleta naЕѕivo online hraЕҐ o peniaze online Free spiny v sk casine What online casino pays real money no deposit stiahnut hracie automaty zadarmo
Paxtonsix
September 24, 2026, at 12:47 amGlad to have another reliable bookmark for this topic, and a look at oakridgevendorhall suggested several more pages I will be marking too, building a personal library of trustworthy resources is one of the actual rewards of careful browsing and this site is earning a place on my permanent shortlist for the topic.
BryannIc
September 24, 2026, at 12:54 amРаздел «Производство» подтверждает статус завода, а не просто перекупщика
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-m10603—uns/poroshok-magnievyy-m10603—uns/
karkasnyy_tzKt
September 24, 2026, at 1:01 amЕсли вы ищете надёжный и быстрый способ построить уютное жильё, обратите внимание на [url=https://karkasnye-doma-spb13.ru]каркасный дом спб[/url].
На рынке недвижимости каркасные дома приобретают все большую востребованность.
Darrenadure
September 24, 2026, at 1:11 amSpeaking from the perspective of having read widely on the topic this site offers something distinct, and a look at granitestoneexchange reinforced that distinctness, the rare site that contributes something genuinely original to a saturated topic is the rare site worth following carefully and this one has demonstrated that original contribution capability today.
Dextertrano
September 24, 2026, at 1:13 amSpent a few minutes here and came away with a clearer picture of the topic, the writing keeps things simple without dumbing them down, and after a stop at solarorchardvault the rest of the points lined up neatly which is something I appreciate when I am short on time and need answers fast.
JeffreyFup
September 24, 2026, at 1:16 amЗаказывали партию молибденовых листов для производства, качество металла идеальное, все сертификаты в наличии.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-25kh18-mm-m3rm-gost-r-52948-2008/
Sterlingdeene
September 24, 2026, at 1:18 amPicked this for my morning read because the topic seemed worth the time, and a look at creekstoneemporium confirmed the choice was right, my morning reading slot is precious and giving it to this site felt like a good investment rather than a waste which is a higher endorsement than I usually offer for content.
RobertFaf
September 24, 2026, at 1:34 amadmiral casino bonus za registrГЎciu bez vkladu casino hry zdarma sk hraci automaty online casino zdarma Hranie automatov na internete hracie automaty online zdarma synot hrГЎt kde jsou free spiny za registraci
Kevinlooda
September 24, 2026, at 2:07 amгероин закладки – Онлайн магазин
Kevinlooda
September 24, 2026, at 2:29 amлирика 75 мг купить – Онлайн магазин
MichaelDiofe
September 24, 2026, at 2:47 amhttps://intercom.help/bestpromo/en/articles/17091861-winwin-bet-oК»zbekiston-xush-kelibsiz-bonusi-va-promokod-2026-maxon-bonus-130-eur
WilliamSweld
September 24, 2026, at 2:49 amhttps://intercom.help/bestpromo/en/articles/17117106-melbet-code-promo-du-jour-mali-2026-mel200big-bonus-85-000-xof
Kevinlooda
September 24, 2026, at 2:49 amкокаин доставка – Онлайн магазин
RobertFaf
September 24, 2026, at 3:39 amsceptre of cleo echtgeld casino bonus s nГzkym wageringom multi lotto automaty zdarma Fortuna free spiny na dnes fortuna casino hry hrat automaty zdarma bez registrace
RobertFaf
September 24, 2026, at 3:51 amfree spiny bez overeni uctu casino free spin gratis slovmatic bonusovy kod Online hry o peniaze casino automaty hrat zadarmo ruleta hra online zdarma
Kellyexors
September 24, 2026, at 4:27 amTop tier post, the kind that makes you want to share the link with friends working in the same area, and a stop at wildharborvendorhall only made me more confident in doing that, this site is one of the better resources I have seen on the topic recently across both new and older posts.
ThomasDeema
September 24, 2026, at 4:28 amЕсли нужны развернутые сведения, их можно прочитать дополнительно: читать далее
BryannIc
September 24, 2026, at 4:33 amПредставлен полный цикл изделий: от фольги и проволоки до крупных поковок
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-ms6—jis-h-4204/izdeliya-iz-magniya-ms6—jis-h-4204/
RobertFaf
September 24, 2026, at 4:44 ambonus no deposit casino 2026 automaty trnava hracie online automaty trezory Automaty zadarmo hraci automaty zdarma online sk online casino s okamЕѕitГЅmi vГЅplatami
DonaldKiLla
September 24, 2026, at 4:58 amШирокий выбор нержавеющей стали различных марок позволяет использовать продукцию в строительстве и пищевой промышленности.
https://rms-ekb.ru/catalog/stalnoi-list/stalnoi-list-10g2s1-1-6x1000x2000-gost-19903-2006-gladkii-chernyi-goriachekatanyi/
Kevinlooda
September 24, 2026, at 5:12 amкупить наркотики бот – Онлайн магазин
Kevinlooda
September 24, 2026, at 5:35 amамфетамин кокаин купить – Онлайн магазин
Kevinlooda
September 24, 2026, at 5:55 amможно ли купить наркотики – Онлайн магазин
LouisHem
September 24, 2026, at 6:19 amNow organising my browser bookmarks to give this site easier access, and a look at wildtrailartisanbazaar earned the same organisational priority, the small acts of digital housekeeping I do for sites I expect to use often are themselves a measure of trust and this site has triggered the trust based housekeeping behaviour from me clearly.
JeffreyFup
September 24, 2026, at 6:35 amОтветственная компания, которая ценит долгосрочное сотрудничество, всегда идут навстречу клиенту.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-gost/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-23kh1-2-mm-lts40s-gost-13942-86/
RobertFaf
September 24, 2026, at 6:49 amstiahnut zdarma hracie automaty hracie automaty zdarma joker 81 free hracie automaty online smiling joker 2 Hry v kasine o peniaze top spigo casinos ice casino 25€ no deposit
JasonBok
September 24, 2026, at 6:55 amNow planning a longer reading session for the archives, and a stop at junipertrailartisanbazaar confirmed the archives are worth that longer commitment, sites with archives I want to read deliberately rather than just sample are rare and this one has clearly earned that level of interest based on the consistency of what I have already read.
RobertFaf
September 24, 2026, at 7:03 amf1 casino 20 € ruleta online free hracie automaty 81 Automaty kajot zdarma bonus za registráciu kde jsou dnes free spiny
RobertFaf
September 24, 2026, at 7:55 amautomaty zdarma wild rubies automati hracie dobitie z telefonu stack em slot Vyskusaj free spiny bez vkladu hracie automaty online zdarma sizzling american blackjack online free
DarylDiemn
September 24, 2026, at 8:07 amReally like that the writer trusts the reader to follow simple logic without restating every previous point, and a stop at rainstoneexchange kept that respect going, treating an audience as capable adults rather than as people who need constant hand holding makes a noticeable difference in the reading experience for me.
BryannIc
September 24, 2026, at 8:15 amНаличие кобальтовых сплавов заинтересует авиастроение
https://redmetsplav.ru/store/titan/rossiyskie-splavy-4/titan-spt-2—gost-27265-87-2/lenta-titanovaya-spt-2—gost-27265-87-2/
Kevinlooda
September 24, 2026, at 8:19 amзакладки альфа пвп – Онлайн магазин
Kevinlooda
September 24, 2026, at 8:42 amконопля купить москва – Онлайн магазин
Kevinlooda
September 24, 2026, at 9:02 amтрамадол таблетки купить в москве – Онлайн магазин
RobertFaf
September 24, 2026, at 10:01 amautomaty online slovenske bonus 7 euro slot wild 81 end stars automaty zdarma Online hry automaty blackjack online legal scarab kingdom echtgeld
RobertFaf
September 24, 2026, at 10:14 amlive casino slovensko kasГno bez vkladu s bonusom avalon gold slot Online ruleta za realne peniaze ako hrat blackjack new online casinos 2026
RobertFaf
September 24, 2026, at 11:08 amhrat zdarma automaty online najlepsie casino online automat na centy Navod ako hrat automaty live casino stream casino bonus deposit
ThomasDeema
September 24, 2026, at 11:23 amЕще больше материалов можно прочитать в представленном источнике – по ссылке
Kevinlooda
September 24, 2026, at 11:27 amкупить кокаин онлайн – Онлайн магазин
Kevinlooda
September 24, 2026, at 11:49 amальфа пвп купить – Онлайн магазин
JeffreyFup
September 24, 2026, at 11:50 amДолго искали надежного поставщика циркония, в Редметсплав предложили лучшие условия и чистоту металла.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednye-dvukhrastrubnye-mufty-pod-paiku/mednaiadvukhrastrubnaiamufta-pod-paiku40kh1-8mmm3mgost-32590-2013/
BryannIc
September 24, 2026, at 11:53 amНикелевые сплавы — основа для жаропрочных конструкций
https://redmetsplav.ru/store/vismut/zarubezhnye-splavy-3/vismut-cac912—jis-h-5120-2016/poroshok-vismutovyy-cac912—jis-h-5120-2016/
Kevinlooda
September 24, 2026, at 12:09 pmкупить ганджубас – Онлайн магазин
Bufordneace
September 24, 2026, at 12:36 pmWell done, the kind of post that makes you slow down and actually read instead of skimming for keywords, and a look at junohub kept me reading carefully too, that is a sign of writing that has been crafted rather than churned out for an algorithm to see today and tomorrow.
RobertFaf
September 24, 2026, at 1:13 pmsk online kasina online kasina sk slotwolf casino bonus Online casino vklad cez sms kajot online casino sk automaty zdarma hry sizzling hot deluxe
RobertFaf
September 24, 2026, at 1:26 pmblackjack stratГ©gia pre zaДЌiatoДЌnГkov minimum deposit 5 euro automaty zdarma online casino Hry o skutocnu vyhru hraci automaty zdarma 81 online hracie automaty kajot
Williamnuava
September 24, 2026, at 1:46 pmрегистрация Апекс казино
?Смотри тут Apex Casino
2seoBes
September 24, 2026, at 1:51 pmПривет всем!
Материал по теме «продвижение сайта стоимость стоимость» раскрывает направление «Цены на SEO-продвижение» и объясняет, как оно используется для развития сайта и бизнеса. Проект рассматривается комплексно: учитываются стоимость услуг и варианты бюджета на продвижение сайта. Последовательность действий определяется после проверки состав тарифа, объём работ, сроки, исходное состояние проекта и цели. Эффект оценивается не по отдельному показателю, а по видимости, целевому трафику, обращениям и качеству страниц.
Подробная информация на сайте https://2seo.ru/services/seo/yandex/
оптимизация сайта контекстной рекламой, seo требуется, seo продвижение цена в месяц
продвижение в поиске яндекса, [url=https://2seo.ru/services/seo/ecommerce/]раскрутку сайта магазина[/url], сео поддержка сайта
Удачи!
DonaldKiLla
September 24, 2026, at 1:55 pmКомпания выступает важным звеном в цепочке снабжения предприятий машиностроения и оборонно-промышленного комплекса.
https://rms-ekb.ru/catalog/stalnoi-list/stalnoi-list-10khndp-2x1700x1200-gost-19903-2006-gladkii-neotsinkovannyi-goriachekatanyi/
RobertFaf
September 24, 2026, at 2:20 pmautomaty za peniaze kde hraЕҐ ruletu online automaty hry zdarma riche Hrat automaty za peniaze vegaz casino bonus online casino s bonusem za registraci
MicahPloks
September 24, 2026, at 2:33 pmStayed longer than planned because each section earned the next, and a look at wavemeadowtradehouse kept that pulling effect going across more pages, the kind of subtle pull that good writing exerts on attention is something I find harder and harder to resist when I encounter it on the open web today.
Kevinlooda
September 24, 2026, at 2:35 pmкупить меф – Онлайн магазин
Williamnuava
September 24, 2026, at 2:38 pmApex Casino зеркало
?
Телеграм канал Апекс казино зеркало открывается по ссылке
Kevinlooda
September 24, 2026, at 2:58 pmкупить мефедрон магазин – Онлайн магазин
Kevinlooda
September 24, 2026, at 3:18 pmгде купить канабис – Онлайн магазин
Williamnuava
September 24, 2026, at 3:32 pmзеркало Апекс казино на сегодня
?
Промокоды Apex Casino публикуются по ссылке
c999gamedownload
September 24, 2026, at 3:40 pmThe installation was super quick and the app runs perfectly on my phone without any lag. Highly recommend c999gamedownload for anyone who prefers gaming on the go.
BryannIc
September 24, 2026, at 3:58 pmИнформация о проверке качества продукции повышает лояльность клиентов
https://redmetsplav.ru/store/volfram/splavy-volframa-1/volfram-w-al-1/provoloka-volframovaya-w-al/
Williamnuava
September 24, 2026, at 4:25 pmApex Casino зеркало
?
Ищи официальный сайт Apex Casino по этой ссылке
RobertFaf
September 24, 2026, at 4:28 pmholdem poker game herne automati zdarma neviditeДѕnГЅ priateДѕ ruleta online Hrat automaty na internete zdarma free spiny online sms platba online casino
RobertRow
September 24, 2026, at 4:33 pmhttps://intercom.help/bonuscode/en/articles/16576401-best-betting-sites-for-kenyan-players-outside-nairobi
TommieLig
September 24, 2026, at 4:34 pmhttps://intercom.help/bonuscode/en/articles/17022875-1xbet-panduan-taruhan-olahraga-2026-mengelola-saldo-panduan-lengkap
AnthonyTak
September 24, 2026, at 4:35 pmhttps://intercom.help/bonuscode/en/articles/17127822-codigo-de-registro-mostbet-nicaragua-2026-most888-bono-400
JesuscrymN
September 24, 2026, at 4:35 pmhttps://intercom.help/bonuscode/en/articles/17024682-1xbet-kode-promo-indonesia-2026-joinbet55
Charlesdooxy
September 24, 2026, at 4:37 pmhttps://intercom.help/bonuscode/en/articles/17122030-мостбет-промокод-не-работает-most888-125
RobertFaf
September 24, 2026, at 4:41 pmkasГno novГ© mesto nad vГЎhom live casino s dealermi online slovensko vГЅhernГ© automaty zadarmo Ako spravne hrat automaty free spiny zadarma online ruleta free spin
Arnoldoobeva
September 24, 2026, at 4:57 pmA piece that did not require external context to follow, and a look at gildedvaleoutlet maintained the same self contained quality, content that stands alone without forcing readers to chase prerequisites is more accessible and this site has clearly thought about how each piece can serve a fresh visitor rather than only existing members.
Williamnuava
September 24, 2026, at 5:20 pmрабочая ссылка Апекс казино
?
Отзывы про Апекс казино собраны на странице
Bobbygaiva
September 24, 2026, at 5:35 pmbestes rabcat online casino tropical tiki slot online casino 5 euro Kasino s minimalnym vkladom 5 eur casino online 2026 hracie automaty zdarma hunters 2
Arthurlox
September 24, 2026, at 5:36 pmLeft me wanting to read more rather than feeling burned out, that is a good sign, and a look at marblecoveartisanoutlet confirmed there is plenty more here to explore, the kind of writing that builds appetite rather than killing it which is a rare quality on the modern open internet today across most categories of content.
Cameronmep
September 24, 2026, at 5:45 pmкупить Гашиш, Бошки, Марихуану купить наркотики спб
luchshie_goSr
September 24, 2026, at 5:57 pmЕсли вы хотите продвинуть свой сайт, обязательно изучите опыт [url=https://workspace.ru/blog/samye-izvestnye-seo-specialisty-rossii-kogo-chitat-slushat-i-u-kogo-uchitsya-v-2026-godu/]лучшие seo специалисты[/url], чтобы выбрать надежного эксперта.
Итогом их работы становится устойчивое развитие и рост бизнеса.
JeffreyFup
September 24, 2026, at 6:05 pmПрофессиональный подход менеджеров в Екатеринбурге, грамотно проконсультировали по техническим характеристикам сплавов.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-76-1kh42-mm-m2t-gost-r-52948-2008/
Cameronmep
September 24, 2026, at 6:08 pmкупить Гашиш, Бошки, Марихуану лирика 75 мг купить
JayAbila
September 24, 2026, at 6:09 pmNow appreciating that the post did not require external context to follow, and a look at tealcovevault maintained the same self contained quality, content that respects new visitors by being readable without prerequisites is content with broader accessibility and this site has clearly invested in keeping each piece reader friendly for fresh arrivals.
Stephenbiofs
September 24, 2026, at 6:09 pmWorth marking this site as one to come back to deliberately rather than by accident, and a stop at plumstoneoutlet reinforced that intention, the difference between sites I find again by chance and sites I return to on purpose is meaningful and this one has clearly moved into the deliberate return category for me.
Judddom
September 24, 2026, at 6:20 pmFound the post genuinely useful for something I was working on this week, and a look at coralharborvault added more material I will reference, content that connects to my actual life and work rather than just being interesting in the abstract is the kind I will pay attention to and return to repeatedly.
Cameronmep
September 24, 2026, at 6:29 pmкупить Гашиш, Бошки, Марихуану купить кокаин онлайн
ThomasDeema
September 24, 2026, at 6:32 pmДополнительную актуальные данные можно найти в дополнительном источнике: на сайте
Williamnuava
September 24, 2026, at 6:45 pmофициальный сайт Apex Casino 2026
?
Вывод средств Apex Casino описан на странице
Bobbygaiva
September 24, 2026, at 7:42 pmfunk master slot admiral casino registracia hracie automaty zdarma apollo Hranie automatov o peniaze bonus joker 2 online tipos hracie automaty
Bobbygaiva
September 24, 2026, at 7:55 pmkasino online automaty fortuna sk free spiny najlepЕЎie kasГno online ruleta Casino za peniaze no 1 casino 1win bonus casino
Cameronmep
September 24, 2026, at 8:54 pmкупить Гашиш, Бошки, Марихуану купить гашиш шишку
NicholasCig
September 24, 2026, at 9:14 pmClosed it feeling I had taken something away rather than just consumed something, and a stop at seacoveartisanmarket extended that taking away feeling, the difference between content I extract value from and content I just pass through is something I track informally and this site is consistently in the value extraction column for me.
Cameronmep
September 24, 2026, at 9:17 pmкупить Гашиш, Бошки, Марихуану купить лирику в москве
JaredCet
September 24, 2026, at 9:25 pmВызвал индивидуалку на дом, все прошло идеально. Она приехала быстро, выглядела прекрасно, была очень нежной и внимательной. Настоящее удовольствие – проститутки пары мж
BryannIc
September 24, 2026, at 9:31 pmНаличие редких позиций, например, изделий из гафния и ванадия
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-as21/folga-magnievaya-as21/
Cameronmep
September 24, 2026, at 9:36 pmкупить Гашиш, Бошки, Марихуану мефедрон телеграмм
phaaajili7
September 24, 2026, at 10:05 pmReally impressed with the user interface. Everything is so easy to find and the loading speed is top notch. Love phaaajili7!
Rexfal
September 24, 2026, at 10:51 pmHonestly this was a good read, no jargon and no padding, and a short look at kettlebrookoutlet kept that same feel going which I really appreciated, the writer clearly knows the topic well enough to explain it without hiding behind big words or filler that often gets used to seem clever.
Bobbygaiva
September 24, 2026, at 10:54 pmonline ruleta recenzie online casino hry zdarma nye online casino Nove casino zo slovenska strip blackjack online online casino vstupnГЅ bonus
Bobbygaiva
September 24, 2026, at 11:07 pmfree spiny dnes zadarmo bez podmienok casino bonus bez vkladu after dark ruleta automaty zdarma Free spiny bez vkladu dnes casino rewards 1 € casino 1 € bonus
TomHat
September 24, 2026, at 11:11 pmOnce you start reading carefully here it is hard to go back to lower quality alternatives, and a stop at pinetrailartisanmart reinforced that ratchet effect, the way good content raises standards is real over time and this site has clearly contributed to raising my expectations for what is possible in writing on the topic generally.
Henryimite
September 24, 2026, at 11:55 pmReading this prompted me to dig into a related topic later, and a stop at mosscoveartisanmart provided some of the starting points for that follow up reading, content that triggers further exploration rather than satisfying curiosity completely is content with real generative energy and this site has plenty of that energy throughout it.
Bobbygaiva
September 25, 2026, at 12:00 amHow to claim 200 free spins in William Hill online blackjack sk kajot cherry bonus Online hracie automaty klasicke automaty zdarma bez registrace hracie automaty zdarma alter dark
Cameronmep
September 25, 2026, at 12:01 amкупить Гашиш, Бошки, Марихуану сайт заказать наркотик
Cameronmep
September 25, 2026, at 12:23 amкупить Гашиш, Бошки, Марихуану где можно купить гашиш
JeffreyFup
September 25, 2026, at 12:30 amСпасибо команде за профессионализм и помощь в реализации нашего сложного промышленного проекта!
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-din/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-m14-12-9kh1-mm-lk-din-471/
Cameronmep
September 25, 2026, at 12:43 amкупить Гашиш, Бошки, Марихуану можно ли купить трамадол без рецепта
DonaldKiLla
September 25, 2026, at 12:46 amАссортимент компании включает более 100 000 позиций, что позволяет закрыть практически любые потребности металлургического производства.
https://rms-ekb.ru/catalog/list/list-3kh3m3f-3x1000x1000-gost-19903-74/
ThomasDeema
September 25, 2026, at 1:14 amДополнительную подробностей можно посмотреть на отдельной странице: читать далее
BryannIc
September 25, 2026, at 1:15 amПоковки и штабики — важные заготовки для металлургических предприятий
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-g-z55zr—afnor-nf-a65-717/pokovka-magnievaya-g-z55zr—afnor-nf-a65-717/
Bobbygaiva
September 25, 2026, at 2:06 amcasino zodiac login f1 casino 20 € hracie automaty na stiahnutie zadarmo do mobilu 1 eur minimalne vkladove kasina playing blackjack online for real money gratowin casino bonus
Bobbygaiva
September 25, 2026, at 2:19 amautomaty online casino casino hracie automaty ruleta free online Sprievodca hranim automatov casino online 2026 20 euro no deposit bonus casino
Cameronmep
September 25, 2026, at 3:07 amкупить Гашиш, Бошки, Марихуану купить мефедрон телеграм
Bobbygaiva
September 25, 2026, at 3:13 amblackjack online play money hracie automaty kajot hry zdarma casino 7 € free Kasina s minimalnym vkladom 20 eur hraci automaty ke stazeni zdarma pc online casino bonus bez vkladu 7 €
Cameronmep
September 25, 2026, at 3:30 amкупить Гашиш, Бошки, Марихуану купить наркотик аптеки
Cameronmep
September 25, 2026, at 3:50 amкупить Гашиш, Бошки, Марихуану купить кокаин
BryannIc
September 25, 2026, at 5:16 amБольшой опыт работы, судя по копирайту с 2013 года
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-mcin2a—jis-h-2221/izdeliya-iz-magniya-mcin2a—jis-h-2221/
Elireugs
September 25, 2026, at 5:19 amTook my time with this rather than rushing because the writing rewards attention, and after daisyaisle I had even more to absorb, the kind of content that pays back the patient reader rather than punishing them with empty filler is something I look for and rarely find in regular searches lately.
Bobbygaiva
September 25, 2026, at 5:20 ambest electric elephant slot sites hracie automaty live blackjack online card counter Hrat ruletu za peniaze online beast mode slot casino online legal
Bobbygaiva
September 25, 2026, at 5:33 amholdem poker game casino bonusy 2026 master joker demo Automaty online bez poplatku kajot registracny bonus nove hracie automaty zadarmo
JeffreyFup
September 25, 2026, at 5:59 amБлагодарим за оперативную поставку ниобиевых труб, выручили в очень сжатые сроки.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednye-krestoviny-pod-paiku/mednaia-krestovina-pod-paiku-28kh23kh0-9-mm-18-4kh20-4-mm-tverdaia-paika-m3r-gost-r-52922-2008/
Cameronmep
September 25, 2026, at 6:15 amкупить Гашиш, Бошки, Марихуану купить бошки героин
Bobbygaiva
September 25, 2026, at 6:27 ambonusy zdarma automaty casino bonus za registraciu bez vkladu tipsport sk free spiny Postup ako hrat automaty casino online vstupny bonus bez vkladu casino bonus zdarma
Cameronmep
September 25, 2026, at 6:37 amкупить Гашиш, Бошки, Марихуану мефедрон можно купить
Cameronmep
September 25, 2026, at 6:57 amкупить Гашиш, Бошки, Марихуану где купить лирику без рецепта
ThomasDeema
September 25, 2026, at 8:07 amДля получения полезных материалов можно посмотреть соответствующую страницу: по ссылке
Bobbygaiva
September 25, 2026, at 8:35 amhracie automaty sk blackjack online odds doxxbet promo kod 2026 Zoznam slovenskych online casin mobil casino slovenskГЅ nГЎhodnГЎ ruleta online hra
Tracealits
September 25, 2026, at 8:40 amFound something quietly useful here that I expect to return to, and a stop at pinemeadowtradehouse added more of the same, content with quiet utility ages well in a way that flashy hot takes do not and I have learned to weight quiet utility much higher when deciding what to bookmark for later use.
Bobbygaiva
September 25, 2026, at 8:48 amblackjack online slovakia hracie automaty the mummy 81 linie nove online ceske casino Retro automaty na skusku synottip 50 pretoceni bez rizika casino online zadarmo
Jameswhalm
September 25, 2026, at 9:07 amhttps://intercom.help/welcome-bonus/en/articles/17072139-codigo-1xbet-para-nuevos-andorra-2026-win88kk-5-reembolso
WilliamLeavy
September 25, 2026, at 9:08 amhttps://intercom.help/welcome-bonus/en/articles/17067607-code-bonus-1xbet-burkina-faso-2026-win88kk-bonus-200
AnthonydeP
September 25, 2026, at 9:09 amhttps://intercom.help/welcome-bonus/en/articles/17083488-code-bonus-1xbet-guide-paiement-2026-win88kk-bonus-130-eur
GeorgeInvak
September 25, 2026, at 9:11 amhttps://intercom.help/welcome-bonus/en/articles/17073178-1xbet-жаңа-ойыншы-бонусы-қазақстан-win88kk-бонус
VictorDrone
September 25, 2026, at 9:12 amhttps://intercom.help/welcome-bonus/en/articles/17078916-code-de-bienvenue-1xbet-2026-win88kk-bonus-100
Edwardrip
September 25, 2026, at 9:14 amhttps://intercom.help/welcome-bonus/en/articles/17062175-1xbet-malaysia-pendaftaran-dan-pengesahan-akaun-2026-win88kk
BryannIc
September 25, 2026, at 9:19 amЛогичное деление на вольфрамовый, молибденовый и титановый прокат
https://redmetsplav.ru/store/niobiy1/splavy-niobiya-1/niobiy-nb-zr-1/truba-niobievaya-nb-zr/
Cameronmep
September 25, 2026, at 9:23 amкупить Гашиш, Бошки, Марихуану купить наркотик магазин
Bobbygaiva
September 25, 2026, at 9:42 amautomaty zdarma sizzling hot blackjack online legal bonus casino 200 Minimalny vklad 20 eur kasina kartГЎДЌ casino bonus bez vkladu casino hry bonus bez vkladu
crazy_dzMt
September 25, 2026, at 9:46 amGioco su Crazy Time da un paio di stagioni, per cui ha senso buttare giu qualcosa visto che qui se ne parlava. Non e la recensione perfetta, giusto come e andata a me.
La cosa che mi ha preso subito e la roba di Evolution. Ci sono i soliti game show, baccarat con croupier che parlano italiano dalle 18 in poi, e ovviamente il gioco della ruota con Cash Hunt e Pachinko. Lato slot siamo intorno ai 1.800 slot: Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, il vecchio Book of Dead di Play’n GO, NetEnt, Yggdrasil. Non e un catalogo infinito, ma il grosso c’e.
Il pacchetto di benvenuto su Crazy Time quando mi sono iscritto era 100% fino a 500€ e poi 200 giri gratis dati un po’ alla volta. Il requisito di puntata sta sui 35x, cosa che non e regalato ma ho visto di molto peggio. C’erano anche qualche giro senza deposito pero ruota di continuo, quindi conviene guardare le condizioni aggiornate su [url=https://236technoticks.com]Crazy Time scarica[/url] se ti interessa.
Deposito minimo 20€, iscrizione con documento d’identita — nel mio caso hanno verificato in un giorno, a un amico tre. Carte vanno senza storie, gli e-wallet tipo Skrill escono in giornata, hanno aggiunto anche le crypto pero li non so dirti. Gli incassi su Crazy Time sono arrivati entro il secondo giorno sull’e-wallet, con bonifico ci vogliono 3-4 giorni.
La cosa che mi ha dato fastidio: manca l’applicazione nativa, solo il sito da browser. Funziona onestamente bene da smartphone, pero con qualche titolo ha fatto i capricci e ho dovuto ricaricare. L’assistenza di casa Crazy Time parla italiano ed e attiva h24, attese ragionevoli, anche se il primo messaggio e quasi sempre preconfezionata. Come licenza e indicata la MGA — per l’Italia e un dettaglio che pesa, ognuno si regola.
Cameronmep
September 25, 2026, at 9:46 amкупить Гашиш, Бошки, Марихуану купить закладку мефедрона
crazy_egMt
September 25, 2026, at 9:46 amBazzico su Crazy Time ormai da circa mezzo anno, quindi tanto vale dire due parole siccome qui si chiedeva. Non e la recensione perfetta, giusto come e andata a me.
Quello che mi ha convinto all’inizio e stata la sezione con i croupier veri. Girano i soliti game show, blackjack con dealer in italiano a certe ore, e va da se quella famosa ruota con i bonus round. Per le slot ci saranno 1.800 titoli: Pragmatic Play con Sweet Bonanza e Gates of Olympus, il vecchio Book of Dead di Play’n GO, qualcosa di NetEnt, Big Time Gaming per chi ama i Megaways. Non e un catalogo infinito, pero il grosso c’e.
Il pacchetto di benvenuto che offre Crazy Time quando mi sono iscritto era un 100% fino a 500€ piu 200 giri gratis spalmati su qualche giorno. Il rigiro e il solito 35x, che non e una passeggiata ma nemmeno assurdo. Ho beccato pure qualche giro senza deposito ma le condizioni cambiano, per cui conviene guardare l’offerta del momento direttamente su [url=https://erlesentv.de]per saperne di piГ№[/url] se ti interessa.
Il minimo per depositare 10 euro, la registrazione con SPID e documento — nel mio caso hanno verificato in un giorno, a un amico tre. Carte funzionano tranquillamente, Skrill e Neteller escono in giornata, c’e anche il Bitcoin ma non l’ho provato. Le uscite fatti su Crazy Time hanno impiegato uno o due giorni via e-wallet, sul bonifico si va a 4 giorni lavorativi.
La cosa che mi ha dato fastidio: manca l’applicazione nativa, solo il sito da browser. Funziona onestamente bene da smartphone, pero in certi tavoli live mi si e impallato e ho dovuto ricaricare. L’assistenza che trovi su Crazy Time risponde in italiano sempre disponibile, attese di 3-5 minuti, anche se la prima risposta e quasi sempre preconfezionata. Licenza dichiarano quella di Curacao — per l’Italia e un dettaglio che pesa, valuta tu.
DonaldKiLla
September 25, 2026, at 9:56 amИспользование системы менеджмента качества гарантирует строгий контроль продукции на всех этапах отгрузки.
https://rms-ekb.ru/catalog/krug-iz-instrumentalnoi-stali/krug-75khsmf-3-gost-7417-75/
bdnogad88
September 25, 2026, at 9:57 amFinally found a platform that doesn’t lag during peak hours. The registration was quick and everything works as promised. Great job bdnogad88!
Terrellgam
September 25, 2026, at 10:00 amDecided this was the kind of site I would defend in a discussion about good blog content, and a stop at oakharborcollective reinforced that, very few sites earn active defence rather than passive consumption and this one has clearly crossed that threshold for me without needing any explicit pitch from the writers themselves either.
Cameronmep
September 25, 2026, at 10:06 amкупить Гашиш, Бошки, Марихуану трамадол таблетки купить
WinstonNuada
September 25, 2026, at 10:41 amGlad to find something on this topic that does not start with three paragraphs of throat clearing before getting to the point, and a stop at creekharborvendorhall also dives right in, respect for the readers time shows up in small editorial choices like this and they add up to a real difference quickly.
JaredCet
September 25, 2026, at 11:04 amДевушка приехала без задержек, выглядела невероятно. Очень нежная, внимательная и страстная одновременно. Провели время так, что хотелось бы повторить снова и снова – досуг проститутки
JeffreyFup
September 25, 2026, at 11:18 amСпасибо команде за профессионализм и помощь в реализации нашего сложного промышленного проекта!
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-53-6kh40-5-mm-m3m-gost-r-52948-2008/
MarioCog
September 25, 2026, at 11:23 amWorth saying that the writing carries a particular kind of authority without making any explicit claims to it, and a stop at velvetbrookvault extended that earned authority feeling, sites that demonstrate expertise through the quality of their explanations rather than by stating credentials are sites I trust most and this site has it.
Quentinzew
September 25, 2026, at 11:25 amLiked how the post handled an objection I was forming as I read, and a stop at zenwillowtrading similarly anticipated where my thinking was going next, the rare writer who can predict reader concerns and address them in advance is doing something most online content fails to do despite that being basic editorial work.
StanleywaB
September 25, 2026, at 11:35 amHowever casually I came to this site I have ended up reading carefully, and a look at calmcovevault continued earning that careful reading, the conversion from casual visitor to careful reader is something content earns rather than demands and this site has accomplished that conversion for me over the course of just a few pieces.
Bobbygaiva
September 25, 2026, at 11:50 amfree spiny za registrГЎciu sk cherry pop slot live casino no deposit bonus Mobilne kasino 10 eur bonus bonusy v kasГnach online casino 2 euro deposit
Bobbygaiva
September 25, 2026, at 12:03 pmonline casino skusenosti gratowin 7 € online casino free spins no deposit Automaty zdarma turbo casino s bonusom gratis blackjack online
Cameronmep
September 25, 2026, at 12:33 pmкупить Гашиш, Бошки, Марихуану купить марки лсд
JerrygEt
September 25, 2026, at 12:48 pmhttps://www.sostav.ru/blogs/288222/82398
Cameronmep
September 25, 2026, at 12:55 pmкупить Гашиш, Бошки, Марихуану кокаин гашиш купить
Bobbygaiva
September 25, 2026, at 12:57 pmkajot casino sk casino hry zdarma automaty automaty zdarma online sazka Ruleta online za peniaze online kasina bonusy bez vkladu 7 € no deposit bonus
Cameronmep
September 25, 2026, at 1:15 pmкупить Гашиш, Бошки, Марихуану трамадол купить
BryannIc
September 25, 2026, at 1:22 pmЧеткое позиционирование как эксперта в области редких металлов
https://redmetsplav.ru/store/vismut/zarubezhnye-splavy-3/vismut-b-505-c-89320—astm-b505/truba-vismutovaya-b-505-c-89320—astm-b505/
Dravensak
September 25, 2026, at 2:16 pmA piece that did not lean on the writer credentials or institutional backing, and a look at coraldockartisanoutlet maintained the same focus on substance, content that earns trust through quality rather than through name dropping is the kind I find most persuasive and this site is clearly playing on the substance side of that distinction.
crazy_ivMt
September 25, 2026, at 2:59 pmBazzico su Crazy Time da un po’ da un paio di stagioni, quindi tanto vale scrivere due righe siccome qui qualcuno chiedeva. Non e il papiro da blog, giusto come e andata a me.
La cosa che mi ha preso subito e stata la sezione con i croupier veri. Trovi gli show, baccarat con croupier che parlano italiano a certe ore, e chiaramente il gioco della ruota con i quattro bonus. Lato slot ci saranno 2.000 giochi: Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, il vecchio Book of Dead di Play’n GO, qualcosa di NetEnt, Betsoft e Yggdrasil. Non hanno tutto, ma il grosso c’e.
Il pacchetto di benvenuto di Crazy Time era il classico 100% fino a 300€ con in aggiunta 100 giri dati un po’ alla volta. Il wagering e il solito 35x, cosa che non e regalato ma nemmeno assurdo. Ho beccato pure qualche giro senza deposito pero ruota di continuo, quindi conviene guardare i termini attuali su [url=https://ah-music.uk]Crazy Time[/url] prima di registrarti.
Deposito minimo 20€, la registrazione classica con verifica documenti — nel mio caso hanno verificato in un giorno, a un mio amico due. Carte vanno senza problemi, Neteller e Skrill sono i piu rapidi in uscita, c’e anche il Bitcoin pero li non so dirti. Gli incassi da Crazy Time mi sono arrivati in 24-48 ore con Skrill, sul bonifico siamo sui 3-4 giorni.
La cosa che mi ha dato fastidio: niente app da scaricare, si gioca dal browser. Va bene sul telefono, pero con qualche titolo ha fatto i capricci e ho dovuto ricaricare. L’assistenza che trovi su Crazy Time ti risponde in italiano ed e attiva h24, attese di 3-5 minuti, pero la prima risposta e un template. Lato licenza e indicata quella di Curacao — per noi in Italia e una cosa da sapere, valuta tu.
crazy_fsMt
September 25, 2026, at 3:04 pmGioco su Crazy Time da quattro o cinque mesi, per cui tanto vale dire due parole dato che qui qualcuno chiedeva. Non e il pistolotto, giusto quello che ho visto io.
Il motivo per cui sono rimasto e la sezione con i croupier veri. Girano i soliti game show, roulette con tavoli italiani a certe ore, e chiaramente quella famosa ruota con i quattro bonus. Lato slot parliamo di 2.000 titoli: Pragmatic Play con Gates of Olympus e Sweet Bonanza, il vecchio Book of Dead di Play’n GO, NetEnt, Betsoft e Yggdrasil. Non hanno tutto, pero il grosso c’e.
Il benvenuto che offre Crazy Time quando mi sono iscritto era un 100% fino a 500€ con in aggiunta 100 giri spalmati su qualche giorno. Il requisito di puntata e 35x, cosa che ti fa sudare ma ho visto di molto peggio. Ho beccato pure qualche giro senza deposito ma cambia spesso, quindi meglio controllare i termini attuali direttamente su [url=https://armacruzhotel.com/crazy-time-passaggi-e-metodi-per-giocare-in-italia/]Crazy Time android[/url] se ti interessa.
Il minimo per depositare 10 euro, registrazione con documento d’identita — da me ci e voluto un giorno, a un mio amico quasi tre. Le carte vanno senza storie, gli e-wallet tipo Skrill sono i piu veloci, c’e anche il Bitcoin ma non l’ho usato. Gli incassi da Crazy Time sono arrivati entro il secondo giorno via e-wallet, con bonifico si va a 4 giorni lavorativi.
La cosa che mi ha dato fastidio: niente app da scaricare, c’e la versione mobile web. Va dignitosamente su Android, ma in certi tavoli live ha fatto i capricci e ho ricaricato la pagina. Il supporto che trovi su Crazy Time risponde in italiano ed e attiva h24, tempi di 3-5 minuti, pero il primo messaggio sa tanto di copia-incolla. Licenza c’e Curacao — per l’Italia va tenuto presente, ognuno si regola.
Bobbygaiva
September 25, 2026, at 3:05 pmako hrat hracie automaty online casino skusenosti free blackjack online multiplayer Mobilne kasino s bonusom 10 eur zahranicne online casino bonus bez vkladu pre slovakov imagine live casino
Bobbygaiva
September 25, 2026, at 3:19 pmhracie automati hrat zadarmo najlepЕЎie kasГnovГ© strГЎnky ЕѕivГЎ ruleta online Hranie automatov o peniaze magic planet casino bonus bez vkladu online casinos blackjack don shuffle
Cameronmep
September 25, 2026, at 3:43 pmкупить Гашиш, Бошки, Марихуану где купить марихуану
crazy_dhMt
September 25, 2026, at 3:55 pmSto girando su Crazy Time da circa mezzo anno, per cui tanto vale dire due parole siccome qui si chiedeva. Non voglio fare la recensione perfetta, solo quello che ho visto io.
La cosa che mi ha preso subito e la sezione con i croupier veri. Trovi tutti i game show, blackjack con tavoli italiani dalle 18 in poi, e ovviamente quella famosa ruota con i bonus round. Sulle slot siamo intorno ai 2.500 e passa slot: i soliti Pragmatic con Sweet Bonanza e Gates of Olympus, Play’n GO, qualcosa di NetEnt, Big Time Gaming per chi ama i Megaways. Non e il piu fornito in assoluto, ma il grosso c’e.
Il pacchetto di benvenuto di Crazy Time al momento e il classico 100% fino a 300€ piu 150 free spin distribuiti nei giorni successivi. Il requisito di puntata e il solito 35x, cosa che non e una passeggiata ma nemmeno assurdo. Ho beccato pure dei free spin senza deposito ma le condizioni cambiano, quindi tanto vale verificare i termini attuali sul [url=https://apkpew.com]crazytime[/url] se ti interessa.
Il minimo per depositare 10 euro, la registrazione con SPID e documento — da me e passata in 24 ore, a un amico quasi tre. Le carte passano senza problemi, Neteller e Skrill sono i piu veloci, accettano pure crypto ma non l’ho provato. Gli incassi fatti su Crazy Time sono arrivati entro il secondo giorno sull’e-wallet, con bonifico siamo sui 3-4 giorni.
La cosa che mi ha dato fastidio: manca l’applicazione nativa, solo il sito da browser. Gira onestamente bene da smartphone, pero su alcune slot si e bloccato e ho ricaricato la pagina. Il supporto di Crazy Time ti risponde in italiano sempre disponibile, tempi di 3-5 minuti, anche se la prima risposta e quasi sempre preconfezionata. Lato licenza c’e la MGA — per noi in Italia e un dettaglio che pesa, ognuno si regola.
crazy_fqMt
September 25, 2026, at 4:00 pmSto girando su Crazy Time ormai da un paio di stagioni, per cui ha senso scrivere due righe siccome qui se ne parlava. Non e il papiro da blog, solo la mia esperienza.
Quello che mi ha convinto all’inizio e la roba di Evolution. Trovi tutti i game show, baccarat con dealer in italiano dalle 18 in poi, e chiaramente il gioco della ruota con Cash Hunt e Pachinko. Per le slot parliamo di 2.500 e passa titoli: Pragmatic con Gates of Olympus e Sweet Bonanza, Play’n GO con Book of Dead, qualcosa di NetEnt, Yggdrasil. Non hanno tutto, ma non ti annoi.
Il pacchetto di benvenuto che offre Crazy Time al momento e un 100% fino a 500€ con in aggiunta 150 free spin spalmati su qualche giorno. Il rigiro e 35x, cosa che ti fa sudare ma ho visto di molto peggio. Ho beccato pure dei free spin senza deposito ma le condizioni cambiano, quindi meglio controllare le condizioni aggiornate su [url=https://zingiberhaircare.com/2026/09/23/crazy-time-passaggi-e-metodi-per-giocare-in-italia/]scaricare Crazy Time[/url] se ti interessa.
Si parte da 20€, la registrazione classica con verifica documenti — a me hanno verificato in un giorno, a un mio amico tre. Visa e Mastercard funzionano tranquillamente, Skrill e Neteller escono in giornata, c’e anche il Bitcoin ma non l’ho usato. Gli incassi su Crazy Time sono arrivati entro il secondo giorno con Skrill, sul bonifico siamo sui 3-4 giorni.
Il neo: manca l’applicazione nativa, si gioca dal browser. Va bene sul telefono, pero con qualche titolo ha fatto i capricci costringendomi a riavviare. Il supporto di casa Crazy Time parla italiano 24 ore su 24, attese sui 5 minuti, pero la prima risposta e un template. Come licenza c’e quella di Curacao — per l’Italia va tenuto presente, ognuno si regola.
Cameronmep
September 25, 2026, at 4:06 pmкупить Гашиш, Бошки, Марихуану где купить марихуану
Bobbygaiva
September 25, 2026, at 4:13 pmhraЕҐ online hry hracГ automaty zdarma neomezenД› bez registrace zdarma online vulkan vegas 50 free spins Hry v casine za peniaze bazos hracie automaty 500 casino bonus
FrankGEr
September 25, 2026, at 4:25 pmкупить Гашиш, Бошки, Марихуану купить мдма мефедрон
HermanHoire
September 25, 2026, at 4:27 pmA particular pleasure to read this with a fresh coffee, and a look at emberridgeartisanoutlet extended the pleasure across more pages, content that pairs well with quiet morning rituals is something I have come to value highly and this site has the kind of energy that fits naturally into a calm reading routine.
crazy_ssMt
September 25, 2026, at 4:32 pmBazzico su Crazy Time da un po’ da circa mezzo anno, per cui ha senso dire due parole visto che qui si chiedeva. Non voglio fare il papiro da blog, semplicemente come e andata a me.
Il motivo per cui sono rimasto e la parte live. Trovi gli show, baccarat con croupier che parlano italiano a certe ore, e ovviamente quella famosa ruota con i quattro bonus. Sulle slot ci saranno 2.000 giochi: i soliti Pragmatic tipo Sweet Bonanza e Gates of Olympus, il vecchio Book of Dead di Play’n GO, qualcosa di NetEnt, Big Time Gaming per chi ama i Megaways. Non e un catalogo infinito, pero il grosso c’e.
Il pacchetto di benvenuto che offre Crazy Time era un 100% fino a 500€ con in aggiunta 100 giri spalmati su qualche giorno. Il requisito di puntata e il solito 35x, che ti fa sudare pero e nella media del mercato. Girava anche qualche giro senza deposito pero ruota di continuo, quindi conviene guardare le condizioni aggiornate sul [url=https://psychoterapia-wawro-gliwice.pl]Crazy Time online[/url] prima di registrarti.
Si parte da 20€, registrazione classica con verifica documenti — nel mio caso ci e voluto un giorno, a un mio amico tre. Le carte passano senza problemi, Neteller e Skrill sono i piu veloci, hanno aggiunto anche le crypto ma non l’ho provato. Gli incassi da Crazy Time hanno impiegato uno o due giorni con Skrill, con bonifico ci vogliono 3-4 giorni.
Il neo: manca l’applicazione nativa, solo il sito da browser. Funziona dignitosamente su Android, ma in certi tavoli live ha fatto i capricci e ho ricaricato la pagina. La chat che trovi su Crazy Time ti risponde in italiano 24 ore su 24, tempi ragionevoli, pero il primo messaggio sa tanto di copia-incolla. Come licenza dichiarano quella di Curacao — per l’Italia va tenuto presente, ognuno si regola.
crazy_pfMt
September 25, 2026, at 4:37 pmGioco su Crazy Time ormai da quattro o cinque mesi, quindi ha senso scrivere due righe visto che qui se ne parlava. Non voglio fare la recensione perfetta, solo la mia esperienza.
Il motivo per cui sono rimasto e la roba di Evolution. Girano i soliti game show, blackjack con dealer in italiano dalle 18 in poi, e ovviamente il gioco della ruota con i quattro bonus. Sulle slot ci saranno 2.000 titoli: Pragmatic Play tipo Gates of Olympus e Sweet Bonanza, Play’n GO con Book of Dead, NetEnt, Big Time Gaming per chi ama i Megaways. Non e il piu fornito in assoluto, pero il grosso c’e.
Il benvenuto su Crazy Time quando mi sono iscritto era 100% fino a 500€ e poi 100 giri distribuiti nei giorni successivi. Il wagering e il solito 35x, che non e una passeggiata ma ho visto di molto peggio. C’erano anche qualche giro senza deposito ma cambia spesso, quindi meglio controllare le condizioni aggiornate su [url=https://lvstripperschool.com/crazytime-passaggi-e-metodi-per-registrarsi-giocare-e-vincere/]crazy time download[/url] prima di depositare.
Si parte da 10 euro, iscrizione con documento d’identita — nel mio caso e passata in 24 ore, a un tizio che conosco due. Le carte vanno senza problemi, Neteller e Skrill escono in giornata, c’e anche il Bitcoin ma non l’ho provato. I prelievi su Crazy Time hanno impiegato uno o due giorni sull’e-wallet, con bonifico ci vogliono 3-4 giorni.
Quello che non mi e piaciuto: niente app da scaricare, solo il sito da browser. Funziona dignitosamente su Android, ma in certi tavoli live mi si e impallato e ho dovuto ricaricare. L’assistenza di Crazy Time parla italiano 24 ore su 24, tempi sui 5 minuti, anche se la prima risposta sa tanto di copia-incolla. Come licenza c’e la MGA — per noi in Italia va tenuto presente, decidi tu.
XanderNog
September 25, 2026, at 5:15 pmStarted reading skeptically because the headline seemed overconfident, and the post earned the headline by the end, and a look at jewelridgecollectivemart continued that pattern of earning its claims, sites that can back up their headlines without overpromising are rare and this one has clearly developed editorial calibration on that front consistently.
Gregdut
September 25, 2026, at 5:41 pmEven just sampling a few posts the consistency is what stands out, and a look at maplemeadow confirmed the broader pattern, sites where every piece I sample lives up to the standard set by the others are sites with serious quality control and this one has clearly invested in whatever editorial process produces that consistency reliably.
JeffreyFup
September 25, 2026, at 5:55 pmДолго искали надежного поставщика циркония, в Редметсплав предложили лучшие условия и чистоту металла.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-din/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-m78-73-5kh2-5-mm-lk80-din-471/
ThomasCug
September 25, 2026, at 6:17 pmwooley booley elvis is alive
wooley booley elvis is alive
wooley booley elvis is alive
wooley booley elvis is alive
wooley booley elvis is alive
https://elvises.site/
MatthewLon
September 25, 2026, at 6:20 pmcasino online euro jak hrat automaty pres internet What games do you find in a casino Casino hry za peniaze tipos casino bonusy How many types of gambling games are there
MatthewLon
September 25, 2026, at 6:33 pmblackjack online odds ako ziskat free spiny casino zadarmo tocenia Online ruleta casino pre zabavu boomerang casino online
FrankGEr
September 25, 2026, at 6:51 pmкупить Гашиш, Бошки, Марихуану где купить лсд
BryannIc
September 25, 2026, at 7:05 pmИнформация о проверке качества продукции повышает лояльность клиентов
https://redmetsplav.ru/store/vismut/zarubezhnye-splavy-3/vismut-toc-30—pn-h-87203/folga-vismutovaya-toc-30—pn-h-87203/
CharlesLAg
September 25, 2026, at 7:08 pmОтличная статья для тех, кто собирает себе спортивный гардероб. Мне очень помогла. Все подробно и понятно расписано. Вот ссылка: https://progorodsamara.ru/interesnoe/view/zenskij-sportivnyj-kostum-na-kazdyj-den-kak-vybrat-udobnuu-model-dla-goroda-i-progulok
FrankGEr
September 25, 2026, at 7:14 pmкупить Гашиш, Бошки, Марихуану масло конопли купить
Nicodiuse
September 25, 2026, at 7:27 pmTook my time with this rather than rushing because the writing rewards attention, and after apricotstoneemporium I had even more to absorb, the kind of content that pays back the patient reader rather than punishing them with empty filler is something I look for and rarely find in regular searches lately.
MatthewLon
September 25, 2026, at 7:27 pmkasino online blackjack naЕѕivo online casino slovensko 5 euro gratis ruleta za peniaze online Free spin hry golden star casino real blackjack online
FrankGEr
September 25, 2026, at 7:34 pmкупить Гашиш, Бошки, Марихуану купить сорт канабиса
DonaldKiLla
September 25, 2026, at 8:42 pmКомпания осуществляет поставки базового металлургического сырья, включая олово, свинец и цинк в чушках.
https://rms-ekb.ru/catalog/krug-iz-instrumentalnoi-stali/krug-6kh7v7fm-100-gost-2590-2006/
Kadeestic
September 25, 2026, at 8:50 pmHonestly the simplicity of the explanation made the topic click for me in a way other writeups had not, and a look at dawnvendor continued that clarity into related areas, when a writer gets the level of explanation right the reader does the heavy lifting themselves and the post just enables it.
Williamquors
September 25, 2026, at 8:58 pmhttps://onlinekazinolatvia.com/
Интернет-казино в Латвии предлагают возможность пользователям участвовать в играх через интернет в игровые автоматы, рулетку, игры в карты и другие виды азартных игр. При выборе площадки важно учитывать наличие лицензии, защищённость платежных операций, порядок снятия средств, правила получения бонусов и качество поддержки клиентов. Согласно законам Латвии, азартные игры в интернете должны предоставляться на основании необходимого разрешения, а участие в играх у нелицензированных операторов запрещено. Поэтому перед регистрацией стоит проверить легальности оператора, внимательно изучить условиями использования и заранее задать личные лимиты расходов.
TerrellWhach
September 25, 2026, at 8:59 pmhttps://vodkakazinokz.com/
Vodka Casino — онлайн т?рде слот ойындары, рулетка ойыны, блэкджек ж?не бас?а да казино ойындарын ойнау?а м?мкіндік беретін интернет-платформа. М?ндай сайтты та?да?анда лицензияны? болуы, т?лем ?дістеріні? ?ауіпсіздігі, ?аражатты алу талаптары, акциялы? ?сыныстарды? талаптары ж?не пайдаланушыларды ?олдау сапасы сия?ты ма?ызды факторлар?а к??іл б?лу ?ажет. Сондай-а? пайдаланушылар ?з бюджеті мен ойын уа?ытын б?рыннан жоспарлап, жергілікті за?дар мен талаптарды назар?а ала отырып, ойын?а жауапты т?рде ?арауы керек.
CyrilDiume
September 25, 2026, at 9:01 pmhttps://onlainkajino.com/
??? ???? ???? ?? ??, ?? ??, ???, ??? ? ?? ??? ??? ?? ???? ? ?? ??? ??????. ???? ?? ?? ??? ????, ?? ??? ???, ?? ?? ??, ??? ??, ?? ?? ??? ?? ??? ???? ?? ????. ?? ???? ??? ?? ??? ?? ??? ??? ????, ?? ??? ?? ?? ????? ??? ? ?? ?? ???? ???? ?? ????.
MatthewLon
September 25, 2026, at 9:34 pm7e bonus no deposit mywin24 casino no deposit bonus casino hry zadarmo Kajot online zan zo casino gratis blackjack online
MatthewLon
September 25, 2026, at 9:47 pmcherry pop slot online vГЅhernГ© automaty hra penez online sk Online hry urobiЕҐ interaktГvnu ruletu online 5 euro no deposit bonus
AntonioNug
September 25, 2026, at 9:51 pmCame back to this an hour later to reread a specific section, and a quick visit to riverharborgoodsstore also drew a second look, content that pulls you back rather than letting you move on permanently is the kind I want to fill my browser bookmarks with in 2026 and beyond as the open internet evolves.
FrankGEr
September 25, 2026, at 10:00 pmкупить Гашиш, Бошки, Марихуану мдма купить
Stevenpes
September 25, 2026, at 10:09 pmhttps://vodkauz.com/
Vodka internet kazinosi — onlayn tarzda slotlar, ruletka o‘yini, blekjek, va turli kazino o‘yinlarini taklif qiluvchi raqamli o‘yin xizmati. Bunday platformani tanlashda faoliyat uchun ruxsat mavjudligi, to‘lov tizimlarining ishonchliligi, pul chiqarish qoidalari, aksiya takliflari shartlari va qo‘llab-quvvatlash xizmatining sifati kabi asosiy mezonlarga e’tibor berish lozim. Shuningdek, o‘yinchilar o‘z mablag‘i va o‘yinga ajratilgan vaqtini avvaldan rejalashtirib, mahalliy qonunlar va talablarni e’tiborga olgan holda, ongli ravishda o‘ynashlari lozim.
Lucasquack
September 25, 2026, at 10:17 pmGenuine reaction is that this site clicked with how I like to read, and a look at bigchequeboutique kept that comfortable fit going, sometimes you find a place online whose editorial decisions just align with your preferences and when that happens it is worth recognising and supporting through repeat engagement consistently going forward.
FrankGEr
September 25, 2026, at 10:23 pmкупить Гашиш, Бошки, Марихуану можно купить коноплю
MatthewLon
September 25, 2026, at 10:41 pmhracie automaty hrat zdarma sizzling hot reef club casino What is the Big 6 casino game Free spiny bez vkladu dnes new online casinos automaty mega joker zdarma
FrankGEr
September 25, 2026, at 10:43 pmкупить Гашиш, Бошки, Марихуану купить лсд
BryannIc
September 25, 2026, at 11:23 pmПредставлен полный цикл изделий: от фольги и проволоки до крупных поковок
https://redmetsplav.ru/store/magniy-i-ego-splavy/rossiyskie-splavy-1/magniy-mg-al-zn—tu-1714-351-00545484-94/lenta-magnievaya-mg-al-zn—tu-1714-351-00545484-94/
JeffreyFup
September 25, 2026, at 11:29 pmОтветственная компания, которая ценит долгосрочное сотрудничество, всегда идут навстречу клиенту.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/dvutavr-aliuminievyi/aliuminievyi-dvutavr-ad33-2-5x48x43-gost-13621-90/
MatthewLon
September 26, 2026, at 12:47 amcasino hra zdarma multi wild 243 wild ape demo Kasina od 20 eur vkladu slot big bamboo online casino bonus za registrГЎciu bez vkladu
MatthewLon
September 26, 2026, at 1:00 amlive dealer casinos kasГna s minimГЎlnym vkladom 1 eur casino deposit 1 euro Registracny bonus 5 eur casino casino m platba vyherne automaty online bez vkladu
Calvinzes
September 26, 2026, at 1:06 amA satisfying piece in the way that good meals are satisfying rather than just filling, and a look at mintorchardoutpost extended that satisfaction, the metaphor between content and meals is one I find useful and this site reads as a satisfying meal rather than the empty calories that most content provides for casual readers.
FrankGEr
September 26, 2026, at 1:08 amкупить Гашиш, Бошки, Марихуану трамадол капсулы 50 купить
Hassanhinee
September 26, 2026, at 1:20 amReading this in a quiet hour and finding it suited the quiet, and a stop at echobrookmarketplace extended the quiet reading mood, content that matches its own optimal reading conditions rather than fighting them is content that has been thoughtfully calibrated and this site reads as having a particular reading mood in mind throughout.
FrankGEr
September 26, 2026, at 1:31 amкупить Гашиш, Бошки, Марихуану наркошоп купить
FrankGEr
September 26, 2026, at 1:50 amкупить Гашиш, Бошки, Марихуану где продают гашиш
MatthewLon
September 26, 2026, at 1:53 am1 € deposit casino náhodná ruleta online hra online casino bonusy Automaty kajot free bet blackjack online casino 10 euro free
Holdenjoymn
September 26, 2026, at 1:58 amReally like that there are no exclamation marks or all caps shouting throughout the post, and a quick visit to flintmeadowcollective maintained the same calm voice, restraint in punctuation signals confidence in the content and this site clearly trusts its substance to do the persuading rather than relying on typographic emphasis.
BillyAmomy
September 26, 2026, at 2:49 amReading this confirmed something I had been suspecting about the topic, and a look at quickridgeoutletmarket pushed that confirmation toward greater confidence, content that lines up with independently held intuitions earns a special kind of trust and I will return to writers who consistently land that way for me without overselling positions.
karkasnyy_foSr
September 26, 2026, at 2:56 amЕсли вы хотите быстро и качественно оформить [url=https://karkasnye-doma-spb12.ru]каркасный дом под ключ в спб[/url], обращайтесь к проверенным специалистам.
Дерево служит главным конструктивным элементом в каркасных домах.
Lioneljuito
September 26, 2026, at 2:58 amFound the writing surprisingly fresh for what is by now a well covered topic, and a stop at mintstoneexchange kept that freshness going across the related pages, original perspective on familiar ground is hard to come by and this site has clearly earned its place in the conversation rather than just rehashing old ideas.
BryannIc
September 26, 2026, at 3:14 amИнформация о проверке качества продукции повышает лояльность клиентов
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-ez33a—astm-b275/krug-magnievyy-ez33a—astm-b275/
klinika_mrpa
September 26, 2026, at 3:15 amЕсли вы ищете надежную [url=https://reproductiveclinic.ru/]клинику для эко по омс[/url], в Санкт-Петербурге доступны современные программы помощи в области вспомогательных репродуктивных технологий.
Для получения услуги ЭКО по ОМС необходимо соблюдение ряда условий и наличие подтвержденных показаний.
DonnyThura
September 26, 2026, at 3:43 amSolid little post, the kind that does not need to be flashy because the substance is doing the work, and a look at honeytrailartisanhouse kept that quiet confidence going across the site, this is what writing looks like when the writer trusts the content to land on its own without theatrics or unnecessary attention seeking behaviour.
MatthewLon
September 26, 2026, at 3:59 amhracГ automaty zdarma 81 automati hry zdarma kajot 27 hraci automaty zdarma kajot 81 Automaty za peniaze casino sk bonus bez vkladu chaos crew slot
JeffreyFup
September 26, 2026, at 4:06 amПорадовало наличие вольфрамовых прутков редких диаметров, менеджер оперативно помог с подбором.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/mednyi-perekhodnoi-troinik-press/mednyi-perekhodnoi-press-troinik-22kh15-mm-m2m-gost-r-52948-2008/
MatthewLon
September 26, 2026, at 4:12 amhracie automaty zdarma super star 27 ako vyhraЕҐ na automatoch automaty hry zdarma wild rubis Retro spiny urobiЕҐ ruletu odmien online bonusy zdarma automaty
FrankGEr
September 26, 2026, at 4:15 amкупить Гашиш, Бошки, Марихуану трамадол где купить
StephenNep
September 26, 2026, at 4:25 amhttps://intercom.help/bestpromo/en/articles/17105008-planbet-bonus-code-czech-republic-planmax-120-3-200-czk
RobertBrupe
September 26, 2026, at 4:26 amhttps://intercom.help/bestpromo/en/articles/17095470-промокод-winwin-bet-на-бонус-кыргызстан-2026-maxon-кэшбэк-50-eur
Tuckernal
September 26, 2026, at 4:26 amGoing to share this with a friend who has been asking the same questions for a while now, and a stop at driftorchardmarket added a few more pages I will pass along too, this is the kind of generous information that earns a small thank you from me right now and again later this week.
Herbertdok
September 26, 2026, at 4:29 amhttps://intercom.help/bestpromo/en/articles/17108203-planbet-portugal-como-obter-um-codigo-promocional-2026-planmax
DonaldKiLla
September 26, 2026, at 4:30 amООО «РМС» специализируется на поставках редких и тугоплавких металлов, таких как ниобий и вольфрам.
https://rms-ekb.ru/catalog/stalnoi-list/stalnoi-list-20kh17n2-11x1400x1500-gost-19903-2006-gladkii-otsinkovannyi-goriachekatanyi/
rolle_bnmi
September 26, 2026, at 4:31 amSigned up at this casino for roughly half a year, so I have a decent feel for how things work. A colleague mentioned it, mainly because I was looking for a platform with fast cashouts. The Rolletto lobby covers a lot of ground, though I personally stick to maybe twenty titles.
Game supply is solid: Pragmatic Play, NetEnt, Play’n GO, Nolimit City and Hacksaw Gaming. Sweet Bonanza and Gates of Olympus are in the top row, though I spend most of my time on high volatility slots. Evolution powers the live section, so you get Crazy Time, Lightning Roulette and all the game shows. There is a full sports section alongside the casino, handy for match days.
The starting promotion here spreads across several deposits: deposit bonuses that stack up to a decent total. Playthrough is forty times the bonus amount, which is on the higher side but not extreme. Updated bonus terms and any active promotions are listed over at [url=https://hybridenumerique.hybrideservices.com/rolletto-promo-code-security-guide/]rolletto promo code 2026[/url] before you deposit. Reload offers and free spin drops come through often, which keeps things interesting after the first deposit.
Minimum deposit is 10 euros or equivalent in crypto. Card payments work, but the real strength is crypto: a dozen different coins. Crypto cashouts came through within hours, fiat payouts were slower as expected. Verification was painless — sent the passport photo and proof of address, done in a day.
I play on the phone via the site and it works well. There is no native app, which honestly I prefer. Support responds in English on live chat and wait times are short. Regulation is Curacao based, so the usual caveats apply. The main thing is withdrawals have never been refused.
RobertGaf
September 26, 2026, at 4:32 amhttps://intercom.help/bestpromo/en/articles/16609175-vave-casino-code-promo-max500-2027-100-bonus-gratuit-instantane-giros-158
lotto_laMa
September 26, 2026, at 4:32 amSigned up at Lottoland for a few months now, enough sessions to see how it actually works. Originally came for the lottery side, though the slots pulled me in too. The game library covers more ground than I expected, mixing lottery betting with standard casino games.
The casino side runs on games from Pragmatic Play, NetEnt, Evolution and Nolimit City. Gates of Olympus and Starburst are both here, though the total count is lower than a standalone casino. Where Lottoland genuinely stands out is the lottery betting: EuroMillions, PowerBall, MegaMillions and about forty others, and the jackpot sizes can be staggering. Scratchcards and quick games fill out the rest.
The introductory bonus on the platform varies by region: usually a free lottery line or discounted entry. Casino bonuses appear occasionally, although the lotto side gets more attention. The live bonus details can be found at [url=https://egco-inspection.ly/2026/09/23/lottoland-casino-rekisteroityminen-askel-askeleelta-opas-suomalaisille/]lottoland[/url] before placing your first bet. Wagering terms on casino bonuses sit around 30 to 40x.
The deposit floor is friendly: a pound gets you into a draw, ten for the casino. The usual cards plus PayPal are accepted. Cashouts via e-wallet took under twenty-four hours, card payouts took a bit longer. Document check went smoothly — ID check passed on the first attempt.
Mobile works through a dedicated app, and it loads quickly. Lottery draws update in real time, and the casino games play fine on mobile too. Customer service responds on chat, replies come within a few minutes. Licensed by the Gibraltar Gambling Commissioner and UK Gambling Commission, so there is genuine oversight. Worth considering if the lottery side interests you.
Jeffreyanync
September 26, 2026, at 4:37 amHeld my interest from the opening line through to the closing thought, and a stop at brightharborvault did the same, content that earns sustained attention in an environment full of distractions is doing something right and this site is clearly doing several things right rather than just one or two which I really appreciate.
FrankGEr
September 26, 2026, at 4:38 amкупить Гашиш, Бошки, Марихуану купить трамадол в городе
NkrutkaTG833Ler
September 26, 2026, at 4:56 amПодскажите контору накрутку реакций на канал. Оптом. Смотрел несколько, остановился на этом: [url=https://nakrutka-reakcij-v-tg-1682.ru]nakrutka-reakcij-v-tg-1682.ru[/url]. Реакции держатся. Работу принял без вопросов.
playf_lfMl
September 26, 2026, at 4:58 amIch bin mittlerweile seit etwa fuenf Monaten bei Play Fortuna unterwegs, also kann ich inzwischen ein ehrliches Urteil abgeben. Bin ueber einen Forenpost darauf gestossen, weil mich das Spielangebot angesprochen hat.
Die Spieleauswahl auf der Plattform geht in die Tausende: Pragmatic, NetEnt und Nolimit City stellen den Grossteil. Die bekannten Hits sind natuerlich dabei, aber die Megaways-Slots machen mir am meisten Spass. Evolution betreibt die Live-Tische: Roulette, Blackjack und Baccarat mit deutschen Dealern. Deutschsprachige Dealer gibt es in der Hauptzeit.
Das Startpaket bei Play Fortuna liegt bei 100 Prozent bis 500 Euro, dazu Freispiele die ueber mehrere Tage verteilt werden. Der Rollover betraegt 40-fach, was hoch ist aber nicht ungewoehnlich. Aktuelle Codes und Angebote stehen bei [url=https://vhaiyen.vn/play-fortuna-was-sie-wissen-mussen/]fortuna casino app[/url] am besten vorher checken. Aktionen kommen laufend nach.
Man kann ab 10 Euro starten. Karten und E-Wallets funktionieren, Bitcoin wird ebenfalls angenommen. Per Wallet ging es in unter 24 Stunden, Kartenauszahlungen brauchten zwei bis drei Tage. Dokumente wurden schnell geprueft — ging beim ersten Versuch durch.
Mobil spiele ich ueber den Browser, die Seite laedt schnell. Kundenservice spricht Deutsch Antworten kommen zuegig. Reguliert wird ueber Curacao, also keine deutsche GGL-Lizenz. Mein Geld kam bisher immer an.
FrankGEr
September 26, 2026, at 4:58 amкупить Гашиш, Бошки, Марихуану Купить Бошки, Шишки, Мефедрон, Кокаин
MatthewLon
September 26, 2026, at 5:06 amhraci automaty zdarma kajot volne tocenia za registraciu 10 euro deposit bonus Automaty online hrat hop n pop free slot malina casino no deposit bonus
NakrutkaTG1050Royaw
September 26, 2026, at 5:18 amПодскажите кто делает накрутку реакций в телеграм быстро. Нужны были эмодзи на канал. Вот сервис: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-1050.ru[/url]. Оплатил — без нареканий. Норм вариант.
rever_pgKl
September 26, 2026, at 5:57 amI have been using this casino since around Easter, so the first impression stage is well past. A mate at work mentioned it, because my old one kept delaying withdrawals. The catalogue at Revery Play is decent, with a good mix of slots, table games and live dealer.
Software comes from Pragmatic Play, NetEnt, Play’n GO, Red Tiger and a few boutique studios. Book of Dead and Reactoonz are easy to find, although the Megaways games are my go-to. Live casino is Evolution, which covers roulette, blackjack and the wheel games. Tables are staffed day and night, but low stake tables get busy in the evening.
The welcome bonus at Revery Play is a 100 percent match up to 200 pounds with free spins. The playthrough sits at 35x, which is reasonable for a UK facing site. The latest promotions are worth looking at on [url=https://www.bimcc.net/reveryplay-security-guide-licensing-player-protection-responsible-gambling/]revery play[/url] before you commit funds. Cashback and free spin drops appear regularly.
Minimum deposit is ten pounds. The standard UK payment methods are accepted. Withdrawals to PayPal landed within a day, card withdrawals took two to three working days. Verification was the standard KYC — passed on the first attempt.
I use the mobile site on my phone and it runs well. There is no native app to install, which I prefer anyway. Support responds on live chat in English and wait times are short. Regulation is Curacao based, so not UKGC, which is worth knowing. The main thing is withdrawals have been honoured.
BryannIc
September 26, 2026, at 7:03 amНаличие обратной связи позволяет быстро отправить запрос
https://redmetsplav.ru/store/magniy-i-ego-splavy/zarubezhnye-splavy-2/magniy-mag-14—bs-2970/folga-magnievaya-mag-14—bs-2970/
karkasnyy_tqKt
September 26, 2026, at 7:05 amЕсли вы ищете надёжный и быстрый способ построить уютное жильё, обратите внимание на [url=https://karkasnye-doma-spb13.ru]каркасный дом под ключ в спб[/url].
Этот тип жилья отличается высокой скоростью возведения и экономичностью.
MatthewLon
September 26, 2026, at 7:11 amruleta naЕѕivo online hracie automaty zdarma americky poker hrace automati zdarma kajot Retro spiny online casino 1 euro deposit casino hold em
EmeryQuoni
September 26, 2026, at 7:12 amHighly recommend to anyone looking for a sensible take on this topic without the usual marketing nonsense, and a look at dunebrookartisanmart kept that grounded approach going, sites that stay focused on serving readers rather than monetising every click are rare and this is clearly one of those rare ones I really appreciate finding.
Cassidyarips
September 26, 2026, at 7:23 amGranted I am giving this site more credit than I usually give new finds, and a look at oliveorchardvault continued earning that credit, the calibration of how much trust to extend after limited exposure is something I do carefully and this site has earned more trust on shorter exposure than most due to consistent quality across.
FrankGEr
September 26, 2026, at 7:23 amкупить Гашиш, Бошки, Марихуану заказать коноплю
Isaiahdwend
September 26, 2026, at 7:23 amReading this prompted a brief but useful conversation with a colleague who happened to walk by, and a stop at cloudcoveoutpost extended that conversational seed, content that becomes a starting point for in person discussion rather than ending in solitary reading is content with social generative energy and this site has plenty of it apparently.
MatthewLon
September 26, 2026, at 7:24 amomnia casino bonus casino bonus bez poДЌiatoДЌnГ©ho vkladu casino sk bonus bez vkladu Casino registracia bonus free spiny pre registrovanГЅch klasicke hracie automaty
FrankGEr
September 26, 2026, at 7:45 amкупить Гашиш, Бошки, Марихуану Купить Кокаин, Мефедрон, Бошки, Марихуану
FrankGEr
September 26, 2026, at 8:05 amкупить Гашиш, Бошки, Марихуану наркошоп купить
MatthewLon
September 26, 2026, at 8:18 amcasino 5 € deposit automaty ke stazeni zdarma stiahnut zdarma hracie automaty Turbo automaty hry online casino admiral casino vstupný bonus
Jamalcok
September 26, 2026, at 8:33 amNow noticing the post fit a particular gap in my reading without my having articulated the gap before, and a look at orchardstonegalleria extended that gap filling effect, content that meets needs I had not consciously formulated is content with reader insight and this site has clearly developed that anticipatory editorial sense across many pieces.
Octavioheene
September 26, 2026, at 8:43 amTop notch writing, every paragraph carries weight and nothing feels like filler, and a stop at kettlestonegalleria reflected that same care, a rare thing on the open web these days where most pages exist for clicks rather than actual reader value or anything close to that which is honestly a real shame.
JeffreyFup
September 26, 2026, at 8:52 amОфис в Екатеринбурге работает четко, забирали самовывозом — складская логистика на высоте.
https://xn--80aeedb0bfzeok.xn--p1ai/catalog/latunnye-naruzhnye-stopornye-koltsa-po-din/latunoe-naruzhnoe-stopornoe-pruzhinnoe-koltso-m107-98kh4-mm-lts40mts1-5-din-471/
RichardOdots
September 26, 2026, at 9:04 amКазино Вавада поддерживает несколько валют счёта на выбор пользователя и работает по международной лицензии Curacao с прозрачной публикацией номера в подвале сайта. Средний RTP по всей библиотеке слотов держится в диапазоне 96-97% на протяжении последних лет работы площадки. Актуальный адрес площадки: vavada казино – https://vavada-air.com Такая мелкая, но полезная деталь заметно ускоряет типовые сценарии и экономит время постоянных игроков.
MarlonRap
September 26, 2026, at 9:32 amPicked up something useful for a side project, and a look at iciclebrookartisanshop added another piece I will incorporate, content that connects to specific projects I am working on is content with practical utility and the practical utility of this site is showing up across multiple posts I have read in the last hour or so.
rolle_tqmi
September 26, 2026, at 9:49 amSigned up at this casino since late spring, enough time to see the real picture. Came across it while comparing promo codes, because my old bookmaker took ages to pay. The Rolletto lobby covers a lot of ground, although I rotate between a handful of favourites.
Providers include the usual suspects: Pragmatic Play, NetEnt, Play’n GO, Hacksaw and Red Tiger. Sweet Bonanza and Gates of Olympus are in the top row, but the Megaways section is what keeps me coming back. Evolution powers the live section, so you get Crazy Time, Lightning Roulette and all the game shows. Betting on football and tennis is another option, which is convenient if you do both.
The sign-up bonus here is a multi-stage offer: a combined match of around 1500 euros with spins on top. The rollover sits at 40x, standard for a crypto-friendly casino. The live codes for this month can be checked on [url=https://explicacontabil.com.br/2026/09/23/rolletto-promo-code-2026-full-uk-guide-to-claiming-your-welcome-bonus/]rolletto[/url] before you deposit. Reload offers and free spin drops come through often, meaning ongoing value if you stay active.
You can start from as little as ten euros. Card payments work, though Bitcoin and the alt coins are where Rolletto shines: Bitcoin, Ethereum, Litecoin, Tether and more. Payouts to the wallet arrived the same evening, card withdrawals took two to three working days. Document check took a single attempt — uploaded ID and a utility bill, cleared overnight.
Mobile play is through the browser and it works well. There is no native app, so no storage concerns. The chat team is available around the clock and the agents seem to actually read the question. Licence is Curacao, so factor that into your decision. Bottom line, payouts have always come through.
lotto_bhMa
September 26, 2026, at 10:12 amI have been using Lottoland for about four months, so I have had enough time to form a real opinion. A friend recommended it for the lotto products, and then discovered the casino section. The game library goes deeper than you would think, combining lotto draws with slots and table games.
Providers on the casino side include Pragmatic Play, NetEnt, Evolution and Nolimit City. The top titles are easy to find, though the selection is not as vast as a pure casino site. Where Lottoland genuinely stands out is the lottery betting: you can bet on the outcome of dozens of international lotteries, including some enormous jackpot pools. Instant win titles round things off.
The sign-up deal on the platform varies by region: usually a free lottery line or discounted entry. Casino bonuses appear occasionally, though the lottery promos are more frequent. The live bonus details can be found at [url=https://cbd-oljy.com]lottoland online[/url] before you sign up. Playthrough on the casino side is in the standard range.
You can start with as little as a pound: a pound gets you into a draw, ten for the casino. Payment methods include cards, PayPal and prepaid options. PayPal payouts landed quickly, card withdrawals were two to three days. Verification was straightforward — ID check passed on the first attempt.
The app is available on both iOS and Android, and it loads quickly. Lottery draws update in real time, with the casino accessible from the same app. Support is available via live chat and email, replies come within a few minutes. Dual licensed, Gibraltar and UK, so there is genuine oversight. A reliable option for lottery and light casino play.
playf_oqMl
September 26, 2026, at 10:13 amSpiele jetzt seit dem Fruehling bei Play Fortuna angemeldet, genug Zeit also um aus eigener Erfahrung berichten. Bin ueber einen Forenpost darauf gestossen, da die Slotauswahl vielversprechend aussah.
Das Angebot an Spielen auf der Plattform ist groesser als erwartet: Pragmatic, NetEnt und Nolimit City sind alle vertreten. Gates of Olympus und Sweet Bonanza sind natuerlich dabei, die Nolimit-Titel sind fuer mich das Highlight. Live Casino laeuft ueber Evolution: alle bekannten Tischspiele plus die Showformate. Deutsche Tische sind abends verfuegbar.
Der Willkommensbonus bei Play Fortuna bietet eine Verdopplung bis 500 Euro, plus Free Spins die ueber mehrere Tage verteilt werden. Wagering liegt bei 40x, was hoch ist aber nicht ungewoehnlich. Gueltige Bonusbedingungen findet man auf [url=https://earthmint.in/2026/09/23/fortuna-casino-app-test-registrierung-bonus-sicherheit-mobile-erlebnis/]fortuna casino app[/url] lohnt sich vorher zu lesen. Cashback und Turniere laufen regelmaessig.
Die Untergrenze liegt bei zehn Euro. Karten und E-Wallets funktionieren, Krypto ist auch moeglich. Skrill-Auszahlungen waren am naechsten Tag da, Bankueberweisungen dauerten laenger. KYC war unkompliziert — Ausweis und Adressnachweis, fertig am selben Tag.
Auf dem Handy nutze ich die mobile Webseite, die Seite laedt schnell. Kundenservice spricht Deutsch und reagiert innerhalb weniger Minuten. Reguliert wird ueber Curacao, was man wissen sollte. Auszahlungen wurden nie verweigert.
RichardRiday
September 26, 2026, at 10:24 amblackjack online casino fortuna promo kГіd kajot hry zdarma automaty Hranie o skutocne peniaze valcove automaty hry zdarma nine casino vstupny bonus
ThomasCip
September 26, 2026, at 10:26 amWorth flagging that the post handled an angle of the topic I had not seen elsewhere, and a look at coastharborgoodsstore extended that fresh treatment, content that finds underexplored corners of well covered subjects is genuinely valuable and this site has demonstrated that exploratory editorial approach across multiple pieces in my reading sessions today.
FrankGEr
September 26, 2026, at 10:30 amкупить Гашиш, Бошки, Марихуану купить марихуана питер
RichardRiday
September 26, 2026, at 10:38 amWhat sites give free spins no deposit casino za vklad automaty online vklad za 2 Free spiny automaty blackjack online arkadium casino bonus za registraciu 2026
rolle_mymi
September 26, 2026, at 10:43 amI have been playing on this casino for roughly half a year, so I have a decent feel for how things work. Came across it while comparing promo codes, mainly because I was looking for a platform with fast cashouts. The catalogue at Rolletto is bigger than I expected, though I personally stick to maybe twenty titles.
The software side is well covered: Pragmatic Play, NetEnt, Play’n GO, Nolimit City and Hacksaw Gaming. The popular titles are all present, although the crash games are surprisingly fun too. Evolution powers the live section, which means twenty-four hour coverage with English and Spanish speaking dealers. Betting on football and tennis is another option, which is convenient if you do both.
The sign-up bonus at Rolletto covers the first four deposits: deposit bonuses that stack up to a decent total. The rollover sits at 40x, a bit steep but manageable with the right games. The live codes for this month can be checked on [url=https://millenniumcarllc.site/2026/09/23/rolletto-promo-code-security-guide-for-uk-players/]rolletto[/url] before you deposit. Weekly cashback and tournament entries pop up regularly, meaning ongoing value if you stay active.
You can start from as little as ten euros. Visa and Mastercard go through without problems, but the real strength is crypto: BTC, ETH, USDT and several others. Payouts to the wallet arrived the same evening, bank transfers ran a few days longer. Verification was painless — the whole thing was over in twenty-four hours.
Mobile play is through the browser and performance is solid. You do not need to download anything, which suits me fine. Support responds in English on live chat and the agents seem to actually read the question. Regulation is Curacao based, which is worth knowing before you sign up. What matters is the money arrives when you ask for it.
BryannIc
September 26, 2026, at 10:46 amУказан физический адрес в Екатеринбурге, что повышает доверие
https://redmetsplav.ru/store/molibden-i-ego-splavy/molibden-mv30-1/list-molibdenovyy-mv30/
rever_fpKl
September 26, 2026, at 10:51 amI have been using this casino for a few months now, so I have a fair idea of how it runs. Came across it while looking for a new UK casino, mainly because the bonus terms elsewhere were ridiculous. The game selection here is solid without being overwhelming, combining slots with a respectable live section.
Providers include Pragmatic Play, NetEnt, Play’n GO, Evolution for the live side. Book of Dead and Reactoonz are easy to find, but I gravitate toward the high volatility section. Live casino is Evolution, which covers roulette, blackjack and the wheel games. Tables are staffed day and night, though the cheap seats fill up after dinner.
The introductory package here comes with a deposit match and a batch of free spins. The playthrough sits at 35x, not the worst but not a gift either. Current offers and promo codes are listed at [url=https://bosk.uk]revery play[/url] since these change monthly. They run ongoing promotions beyond the welcome deal.
You can start from a tenner. Cards and PayPal all work without issues. PayPal payouts arrived quickly, debit card payouts were the usual two to three days. Identity verification went smoothly — driving licence and a utility bill, cleared in a few hours.
I use the mobile site on my phone and it runs well. You play through the site, so no download required. The chat team replies within minutes and the agents are helpful. Regulation is Curacao based, so be aware of that going in. Payouts have always come through for me.
FrankGEr
September 26, 2026, at 10:53 amкупить Гашиш, Бошки, Марихуану трамадол 50 мг купить
playf_mbMl
September 26, 2026, at 11:04 amSpiele jetzt seit ungefaehr einem halben Jahr bei Play Fortuna angemeldet, genug Zeit also um ein ehrliches Urteil abgeben. Ein Kollege hat es empfohlen, hauptsaechlich wegen der Spielauswahl.
Das Angebot an Spielen hier ist groesser als erwartet: Pragmatic Play, NetEnt, Play’n GO liefern die Titel. Book of Dead und Starburst stehen ganz oben, aber die Megaways-Slots machen mir am meisten Spass. Live Casino laeuft ueber Evolution: alle bekannten Tischspiele plus die Showformate. Dealer sprechen Deutsch zu bestimmten Zeiten.
Die Willkommenspromo bei Play Fortuna liegt bei 100 Prozent bis 500 Euro, und Gratisdrehungen die stueckweise freigegeben werden. Der Rollover betraegt 40-fach, was hoch ist aber nicht ungewoehnlich. Aktuelle Codes und Angebote stehen bei [url=https://iisrar.com/?p=3513]play fortuna[/url] vor der Einzahlung pruefen. Aktionen kommen laufend nach.
Die Untergrenze liegt bei zehn Euro. Die ueblichen Zahlungsmethoden gehen problemlos, Bitcoin wird ebenfalls angenommen. Skrill-Auszahlungen waren am naechsten Tag da, Auf die Karte waren es drei Werktage. Verifizierung lief glatt — Personalausweis hochgeladen und in Stunden bestaetigt.
Mobil spiele ich ueber den Browser, funktioniert einwandfrei. Kundenservice spricht Deutsch und reagiert innerhalb weniger Minuten. Es gilt eine Curacao-Lizenz, also keine deutsche GGL-Lizenz. Mein Geld kam bisher immer an.
lotto_akMa
September 26, 2026, at 11:06 amSigned up at Lottoland for a few months now, so I have had enough time to form a real opinion. I found it because of the lottery betting, and then discovered the casino section. The game library is surprisingly large, combining lotto draws with slots and table games.
The casino side runs on games from Pragmatic Play, NetEnt, Evolution and Nolimit City. Gates of Olympus and Starburst are both here, though the total count is lower than a standalone casino. The real draw is the lottery product: you can bet on the outcome of dozens of international lotteries, with jackpots sometimes exceeding a billion. Instant win titles round things off.
The welcome offer on the platform is region specific: typically a discounted first bet on a lottery draw. Deposit matches for the casino show up now and then, though the lottery promos are more frequent. The live bonus details can be found at [url=https://aovamos.com/lottoland-casino-kaikki-mita-suomalaisen-pelaajan-tulee-tietaa/]lottoland[/url] since they rotate regularly. Playthrough on the casino side is in the standard range.
Minimum deposit is low: a pound gets you into a draw, ten for the casino. Visa, Mastercard, PayPal and Paysafecard all work. Cashouts via e-wallet took under twenty-four hours, card payouts took a bit longer. Verification was straightforward — passport photo cleared within the day.
There is a proper app for phone and tablet, and it loads quickly. Draw results appear as they happen, with the casino accessible from the same app. The help team is reachable through live chat, replies come within a few minutes. Licensed by the Gibraltar Gambling Commissioner and UK Gambling Commission, which gives proper regulatory backing. A reliable option for lottery and light casino play.
FrankGEr
September 26, 2026, at 11:13 amкупить Гашиш, Бошки, Марихуану где купить героин
rolle_aymi
September 26, 2026, at 11:18 amBeen using Rolletto for roughly half a year, enough time to see the real picture. Found it through a recommendation, because my old bookmaker took ages to pay. The game library here covers a lot of ground, although I rotate between a handful of favourites.
Providers include the usual suspects: Pragmatic Play, NetEnt, Play’n GO, Evolution for live tables and Big Time Gaming for Megaways. The popular titles are all present, although the crash games are surprisingly fun too. The live dealer area is Evolution, so you get Crazy Time, Lightning Roulette and all the game shows. There is a full sports section alongside the casino, a nice extra for those who like to mix it up.
The welcome package at Rolletto is a multi-stage offer: a combined match of around 1500 euros with spins on top. Wagering is 40x on the bonus, a bit steep but manageable with the right games. Updated bonus terms and any active promotions are worth verifying at [url=https://test-pantheon.smarterreporting.org/2026/09/23/rolletto-promo-codes-uk-payment-methods-fast-withdrawals-bonus-guide/]rolletto promo code 2026[/url] before committing money. There are reload bonuses every week, so it is not just the welcome deal.
Minimum deposit is 10 euros or equivalent in crypto. Visa and Mastercard go through without problems, although the crypto options are the quickest route: BTC, ETH, USDT and several others. Crypto cashouts came through within hours, fiat payouts were slower as expected. Document check took a single attempt — sent the passport photo and proof of address, done in a day.
I play on the phone via the site and it works well. You do not need to download anything, so no storage concerns. Live chat replies within a few minutes and wait times are short. Licence is Curacao, so factor that into your decision. Bottom line, payouts have always come through.
JacobFix
September 26, 2026, at 11:31 am888 live casino hold em poker online hracie automaty strategia Online ruleta hracie automaty free ruleta online casino gratis
playf_efMl
September 26, 2026, at 11:39 amIch bin mittlerweile seit ungefaehr einem halben Jahr bei Play Fortuna angemeldet, also kann ich inzwischen ein ehrliches Urteil abgeben. Habe es beim Vergleich von Anbietern gefunden, weil mich das Spielangebot angesprochen hat.
Der Spielkatalog auf der Plattform ist groesser als erwartet: Pragmatic, NetEnt und Nolimit City sind alle vertreten. Gates of Olympus und Sweet Bonanza findet man sofort, die High-Volatility-Spiele sind fuer mich das Highlight. Evolution betreibt die Live-Tische: Roulette, Blackjack und Baccarat mit deutschen Dealern. Deutschsprachige Dealer gibt es in der Hauptzeit.
Das Startpaket bei Play Fortuna umfasst einen Match-Bonus plus Freispiele, plus Free Spins die ueber mehrere Tage verteilt werden. Der Rollover betraegt 40-fach, im oberen Bereich aber machbar. Die laufenden Promotionen stehen bei [url=https://fachtierarztpraxis-dr-trombach.de]fortuna casino app[/url] lohnt sich vorher zu lesen. Aktionen kommen laufend nach.
Mindesteinzahlung sind 10 Euro. Die ueblichen Zahlungsmethoden gehen problemlos, Crypto geht auch. Skrill-Auszahlungen waren am naechsten Tag da, Auf die Karte waren es drei Werktage. KYC war unkompliziert — ging beim ersten Versuch durch.
Am Smartphone laeuft alles im Browser, die Seite laedt schnell. Kundenservice spricht Deutsch Antworten kommen zuegig. Lizenz ist Curacao, also keine deutsche GGL-Lizenz. Unterm Strich stimmt die Zahlungsmoral.
lotto_lrMa
September 26, 2026, at 11:40 amBeen playing on Lottoland Casino since the start of summer, so I have had enough time to form a real opinion. I found it because of the lottery betting, though the slots pulled me in too. The gaming section is surprisingly large, combining lotto draws with slots and table games.
Software comes from Pragmatic Play, NetEnt, Evolution and Nolimit City. The top titles are easy to find, though the selection is not as vast as a pure casino site. What makes it different is the lotto side: results from lotteries around the world are covered, including some enormous jackpot pools. Scratchcards and quick games fill out the rest.
The welcome offer here is region specific: often a free bet plus some bonus funds. Casino bonuses appear occasionally, though the lottery promos are more frequent. The live bonus details should be verified at [url=https://redwolfmoonprints.com/2026/09/23/lottoland-casino-rekisteroityminen-askeleet-ja-vinkit-suomalaisille-pelaajille/]lottoland[/url] before placing your first bet. Wagering terms on casino bonuses sit around 30 to 40x.
Minimum deposit is low: one pound for lottery bets, ten for casino. Visa, Mastercard, PayPal and Paysafecard all work. Cashouts via e-wallet took under twenty-four hours, card withdrawals were two to three days. KYC was quick — ID check passed on the first attempt.
Mobile works through a dedicated app, and it loads quickly. Draw results appear as they happen, with the casino accessible from the same app. Support is available via live chat and email, response times are reasonable. Licensed by the Gibraltar Gambling Commissioner and UK Gambling Commission, so there is genuine oversight. Overall a solid platform.
rever_bcKl
September 26, 2026, at 11:44 amI have been using Revery Play since around Easter, so the first impression stage is well past. A mate at work mentioned it, mainly because the bonus terms elsewhere were ridiculous. The game selection here is decent, combining slots with a respectable live section.
The games are supplied by Pragmatic Play, NetEnt, Play’n GO, Nolimit City and Hacksaw Gaming. The usual suspects sit at the top, although the Megaways games are my go-to. Evolution handles the live dealer area, which covers roulette, blackjack and the wheel games. English speaking dealers around the clock, although peak hours can be crowded.
The welcome bonus here offers a matched deposit plus spins. The playthrough sits at 35x, which is reasonable for a UK facing site. The latest promotions can be checked on [url=https://mymadison.uk]revery play[/url] since these change monthly. Cashback and free spin drops appear regularly.
The floor is ten pounds. Visa, Mastercard, PayPal and Paysafecard all work without issues. E-wallet cashouts came through same day, bank transfers ran a couple of days. Verification was the standard KYC — passed on the first attempt.
I use the mobile site on my phone and it runs well. No app needed, which honestly suits me. The chat team replies within minutes and wait times are short. Regulation is Curacao based, so be aware of that going in. Bottom line, my money has arrived every time.
LouisDuM
September 26, 2026, at 11:50 amhttps://intercom.help/bestpromo/en/articles/16588474-melbet-promo-code-benin-2027-fan200-welcome-bonus-f500f-sports-f500f-or-casino-f7500f
DonaldKiLla
September 26, 2026, at 12:13 pmШирокий выбор нержавеющей стали различных марок позволяет использовать продукцию в строительстве и пищевой промышленности.
https://rms-ekb.ru/catalog/ugolok-stalnoi/ugolok-iz-konstruktsionnoi-stali-50kh30kh5-mm-40nicr6-din-59370/
rever_uxKl
September 26, 2026, at 12:18 pmSigned up with Revery Play for a few months now, enough time to see the patterns. A mate at work mentioned it, because my old one kept delaying withdrawals. The Revery Play lobby covers the main bases, enough variety to keep things fresh.
Software comes from Pragmatic Play, NetEnt, Play’n GO, Evolution for the live side. Book of Dead and Reactoonz are easy to find, although the Megaways games are my go-to. The live tables run on Evolution, meaning all the major game shows and table games. Tables are staffed day and night, though the cheap seats fill up after dinner.
The sign-up offer at Revery Play offers a matched deposit plus spins. Rollover is thirty-five times the bonus, not the worst but not a gift either. Current offers and promo codes can be checked on [url=https://sandybrown-termite-451260.hostingersite.com/reveryplay-bonus-guide-up-to-ps200-welcome-match-free-spins-and-wagering-terms/]revery play[/url] before you commit funds. There are weekly reload offers.
Minimum deposit is ten pounds. The standard UK payment methods go through smoothly. PayPal payouts arrived quickly, card withdrawals took two to three working days. Identity verification went smoothly — uploaded ID and it was approved overnight.
I use the mobile site on my phone and it runs well. You play through the site, so no download required. The chat team replies within minutes and the agents are helpful. They hold a Curacao licence, meaning no UK Gambling Commission oversight. Payouts have always come through for me.
RichardOdots
September 26, 2026, at 12:21 pmКазино Вавада поддерживает несколько валют счёта на выбор пользователя и работает по международной лицензии Curacao с прозрачной публикацией номера в подвале сайта. Редакционная подборка «Автомат недели» обновляется по понедельникам с пояснением, почему выбран именно этот релиз. Свежая ссылка на ресурс: вавада казино Такая техническая грамотность в работе с сетевым слоем заметно расширяет доступность площадки в разных регионах.
Scotthow
September 26, 2026, at 1:37 pmfree spiny zdarma jen za registraci české automaty online ruleta online 3d Fortuna free spiny dnes tusk casino 5 € zadarmo spiny za registraciu
LarryGoano
September 26, 2026, at 1:39 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
RichardOdots
September 26, 2026, at 1:49 pmТурнирная сетка Vavada обновляется еженедельно, а призовой фонд делится между лидерами таблицы по объёму ставок. Список доверенных устройств освобождает личный смартфон или ноутбук от повторного ввода 2FA-кода в течение месяца. Переходите на площадку по ссылке: vavada casino – https://vavada-air.com Такая работа с сообществом формирует ощущение живого проекта, где мнение аудитории учитывается в продуктовых решениях.
Scotthow
September 26, 2026, at 1:50 pmjackpot city flash hracГ automaty stГЎhnout zdarma hracie automaty 2026 Automaty na peniaze hrat automaty bez registrace online doxxbet live casino
ChadVog
September 26, 2026, at 2:01 pmBetter signal to noise ratio than most places I check on this kind of topic, and a look at rivervendor kept that going, every paragraph here carries something worth reading rather than padding out the page to hit some arbitrary length target that search engines reward but readers ignore as soon as they notice it.
LarryGoano
September 26, 2026, at 2:01 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
LarryGoano
September 26, 2026, at 2:21 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
ph55vip777
September 26, 2026, at 2:33 pmFeeling like a total VIP here. The rewards program at ph55vip777 is honestly the best in the market.
NkrutkaTG833Ler
September 26, 2026, at 2:34 pmКто делает накрутку эмодзи телеграм. Без бана канала. Смотрел несколько, взял тут: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в телеграм[/url]. Результат ок. Работу принял без вопросов.
Scotthow
September 26, 2026, at 2:44 pmhot spin deluxe stГЎhnout automaty zdarma ako zГskaЕҐ free spiny bez vkladu Kasino online bonus za zaloЕѕenie ГєДЌtu 2026 casino bonus bez vkladu 10€
AntonioNug
September 26, 2026, at 2:57 pmNow adjusting my mental model of how the topic fits into the broader landscape, and a look at riverharborgoodsstore extended that adjustment, content that affects my structural understanding rather than just my factual knowledge is content with deeper impact and this site is providing those structural updates at a meaningful rate consistently across topics.
Ricardourine
September 26, 2026, at 3:13 pmNow adjusting my mental list of reliable sites for this topic, and a stop at quickstoneemporium reinforced the adjustment, the small ongoing curation work of maintaining trusted sources is one of the actual practical activities of careful reading and this site has earned a permanent place on my list for this particular subject.
NkrutkaTG833Ler
September 26, 2026, at 3:17 pmПодскажите контору накрутку эмодзи телеграм. Быстро и недорого. Смотрел несколько, остановился на этом: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в телеграм[/url]. Можно брать. Работу принял без вопросов.
NakrutkaTG1050Royaw
September 26, 2026, at 3:22 pmИщу кто делает накрутку реакций телеграм недорого. Нужны были живые реакции без ботов. Вот сервис: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-474.ru[/url]. Оплатил — цена адекватная. Буду ещё брать.
NakrutkaTG1050Royaw
September 26, 2026, at 3:55 pmПосоветуйте сервис накрутку реакций на посты в тг оптом на канал. Нужны были реакции на несколько постов. Посоветовали: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-1050.ru[/url]. Заказал — сделали нормально. Буду ещё брать.
LarryGoano
September 26, 2026, at 4:46 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 26, 2026, at 4:50 pmcasino no deposit 10 € sk casino guru zeus vs hades demo Kasino online urobiť hru ruleta online zadarmo ruleta online free
Scotthow
September 26, 2026, at 5:04 pmonline vyherne automaty vlt automaty online zdarma ceske online casino bonus bez vkladu Free spin hry blackjack online poДЌГtanie kariet legalne automaty online
LarryGoano
September 26, 2026, at 5:09 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
RichardOdots
September 26, 2026, at 5:22 pmВывод средств на Казино Вавада обрабатывается от нескольких минут до суток в зависимости от выбранного платёжного метода. Ежедневные квесты балансируются под уровень активности игрока: новички не получают невыполнимых задач, опытный сегмент видит челленджи посерьёзнее. Условия бонусной программы описаны на странице: [url=https://vavada-air.com]вавада вход[/url] Такой подход делает возвращение на площадку интересным даже в те дни, когда нет активных бонусов и крупных турниров.
LarryGoano
September 26, 2026, at 5:29 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
Peteroblic
September 26, 2026, at 5:34 pmNow planning a longer reading session for the archives, and a stop at echobrookoutpost confirmed the archives are worth that longer commitment, sites with archives I want to read deliberately rather than just sample are rare and this one has clearly earned that level of interest based on the consistency of what I have already read.
Larrytheof
September 26, 2026, at 5:38 pmMahadev Ticket is India’s premier goal in support of secure betting IDs, room cricket, IPL, football & casino games. Trusted past 10L+ users — 24/7 strengthen, fast withdrawals, best odds.
Meta Keywords: Mahadev Paperback, Mahadev Books, Mahadev Online Tome, Mahadev Betting, Mahadev Work Login, MahadevBook Login, Mahadev Words ID, Mahadev Betting ID
Scotthow
September 26, 2026, at 5:57 pmdeposit poker bonus penny slots strategy online casino bez registracie Automaty na peniaze hrat online casino 1 € automaty turbo gold zdarma
PrestonEdume
September 26, 2026, at 6:21 pmPicked up on several small touches that suggest a careful editor, and a look at chestnutstoneemporium suggested the same hand at work across the broader site, editorial consistency at a granular level is one of the strongest signs that an operation is serious rather than just hobbyist and this site reads as serious throughout.
crazy_mjMt
September 26, 2026, at 6:43 pmBazzico su Crazy Time ormai da quattro o cinque mesi, quindi tanto vale scrivere due righe visto che qui si chiedeva. Non voglio fare il papiro da blog, solo quello che ho visto io.
Quello che mi ha convinto all’inizio e la sezione con i croupier veri. Trovi gli show, roulette con dealer in italiano dalle 18 in poi, e chiaramente la ruota con i bonus round. Lato slot parliamo di 1.800 giochi: i soliti Pragmatic tipo Gates of Olympus e Sweet Bonanza, Play’n GO con Book of Dead, NetEnt, Betsoft e Yggdrasil. Non e un catalogo infinito, pero c’e quello che serve.
Il pacchetto di benvenuto che offre Crazy Time quando mi sono iscritto era 100% fino a 500€ piu 150 free spin distribuiti nei giorni successivi. Il rigiro e 35x, cosa che non e regalato pero e nella media del mercato. Girava anche dei free spin senza deposito ma le condizioni cambiano, quindi tanto vale verificare i termini attuali sul [url=https://ruralnevadanews.com]maggiori informazioni[/url] prima di depositare.
Si parte da 10€, registrazione con documento d’identita — a me hanno verificato in un giorno, a un tizio che conosco tre. Carte vanno senza problemi, Skrill e Neteller sono i piu rapidi in uscita, hanno aggiunto anche le crypto ma non l’ho provato. I prelievi fatti su Crazy Time sono arrivati entro il secondo giorno con Skrill, in banca si va a 4 giorni lavorativi.
La cosa che mi ha dato fastidio: non c’e un’app vera, c’e la versione mobile web. Va bene sul telefono, ma con qualche titolo ha fatto i capricci e ho ricaricato la pagina. Il supporto di Crazy Time risponde in italiano 24 ore su 24, tempi di 3-5 minuti, pero la prima risposta e quasi sempre preconfezionata. Lato licenza c’e la MGA — per noi in Italia e una cosa da sapere, ognuno si regola.
JosephBem
September 26, 2026, at 7:47 pmReading this gave me material for a conversation I needed to have anyway, and a stop at cottonmeadowvault added even more talking points, content that connects to upcoming social or professional needs rather than just being interesting in the abstract is the kind that earns priority placement in my attention these days routinely.
LarryGoano
September 26, 2026, at 7:54 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
crazy_dkMt
September 26, 2026, at 8:04 pmBazzico su Crazy Time da quattro o cinque mesi, per cui tanto vale scrivere due righe siccome qui si chiedeva. Non e la recensione perfetta, giusto la mia esperienza.
Quello che mi ha convinto all’inizio e stata la parte live. Girano i soliti game show, roulette con dealer in italiano in fascia serale, e ovviamente la ruota con i quattro bonus. Sulle slot siamo intorno ai 2.500 e passa slot: Pragmatic Play con Gates of Olympus e Sweet Bonanza, il vecchio Book of Dead di Play’n GO, un po’ di NetEnt, Big Time Gaming per chi ama i Megaways. Non e un catalogo infinito, pero non ti annoi.
Il pacchetto di benvenuto di Crazy Time al momento e il classico 100% fino a 300€ con in aggiunta 150 free spin dati un po’ alla volta. Il wagering e il solito 35x, cosa che non e regalato pero e nella media del mercato. Ho beccato pure un piccolo no deposit ma le condizioni cambiano, quindi meglio controllare le condizioni aggiornate sul https://openinternet.it/uncategorized/crazy-time-app-guida-completa-alla-verifica-dell-account/ se ti interessa.
Deposito minimo 10€, la registrazione con SPID e documento — nel mio caso ci e voluto un giorno, a un tizio che conosco due. Visa e Mastercard vanno senza problemi, Neteller e Skrill escono in giornata, accettano pure crypto ma non l’ho provato. Gli incassi su Crazy Time sono arrivati entro il secondo giorno via e-wallet, sul bonifico si va a 4 giorni lavorativi.
Quello che non mi e piaciuto: niente app da scaricare, solo il sito da browser. Funziona bene sul telefono, ma con qualche titolo si e bloccato e ho ricaricato la pagina. La chat di casa Crazy Time ti risponde in italiano ed e attiva h24, attese sui 5 minuti, pero il primo messaggio e quasi sempre preconfezionata. Come licenza e indicata la MGA — per un giocatore italiano va tenuto presente, ognuno si regola.
Scotthow
September 26, 2026, at 8:04 pmCan you play free casino games on your phone Which online casino pays instantly spin city no deposit bonus Kasino s vkladom od 20 eur minimum hrat automaty zdarma mega joker hrat automaty zdarma sizzling
Scotthow
September 26, 2026, at 8:17 pmbonusy casino dnes bet ring vstupnГЅ bonus live casino play for fun Minimalny vklad 5 eur v kasine online casino s licenci banco casino live
LarryGoano
September 26, 2026, at 8:17 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
BrianAlaws
September 26, 2026, at 8:23 pmhttps://intercom.help/welcome-bonus/en/articles/17083409-1xbet-welcome-bonus-code-2026-win88kk-bonus-130-eur
LouisDuM
September 26, 2026, at 8:23 pmhttps://intercom.help/welcome-bonus/en/articles/17052950-1xbet-kampanjkod-vid-registrering-sverige-2026-win88kk-125
Bradleyetema
September 26, 2026, at 8:24 pmhttps://intercom.help/welcome-bonus/en/articles/17040997-1xbet-Ш§ШіЩѕЩ€Ш±Щ№Ші-Ъ©Щ€Ъ€-ШµШ§Ш±ЩЃ-Щ…Ш№Ш§Щ€Щ†ШЄ-win88kk
Danielsuive
September 26, 2026, at 8:29 pmhttps://intercom.help/welcome-bonus/en/articles/17074075-Ш§Щ„Щ„ЩЃШ§ШЄ-Ш§Щ„Щ…Ш¬Ш§Щ†ЩЉШ©-Щ€ШіШ§Ш¦Щ„-Ш§Щ„ШЇЩЃШ№-1xbet-Щ…ШµШ±-2026-win88kk
RichardOdots
September 26, 2026, at 8:29 pmСлужба поддержки Vavada отвечает в чате в среднем за пару минут и работает на русском, английском, казахском и узбекском языках. Список доверенных устройств освобождает личный смартфон или ноутбук от повторного ввода 2FA-кода в течение месяца. Переходите на площадку по ссылке: [url=https://vavada-air.com]https://vavada-air.com[/url] Такая глубокая локализация встречается не у каждого международного оператора и особенно ценится аудиторией региона СНГ.
SimonGam
September 26, 2026, at 8:35 pmIf you asked me to point to a recent positive sign for the open web this site would be near the top, and a stop at elmmeadowvendorworks reinforced that designation, the few sites that serve as evidence the web can still produce quality independent content are precious and this one has clearly become one for me.
LarryGoano
September 26, 2026, at 8:37 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
RustyMen
September 26, 2026, at 8:45 pmReading this gave me a small mental break from the heavier reading I had been doing, and a stop at nightcoveartisanmarket extended that lighter feel, content that provides relief without becoming trivial is harder to produce than people realise and this site has clearly figured out how to be light without being shallow at all.
Terrybal
September 26, 2026, at 9:08 pmFelt like the post had been edited rather than just drafted and published, and a stop at dunecoveoutlet suggested the same care across the site, the difference between edited and unedited content is enormous for the reader and this site has clearly invested in the editing pass that most blogs skip entirely which really does show up.
Scotthow
September 26, 2026, at 9:10 pmhracie arkadove automaty automaty za reГЎlne peniaze automaty zdarma sizzling stГЎhnout Sk casino free spiny online casino euro zoznam online kasin
Jesusininy
September 26, 2026, at 9:35 pmExcellent execution from start to finish, the post never loses its rhythm and the points stay sharp, and a quick stop at jasperstonecourtyard kept the same level going, consistency like this across a site is the marker of a serious operation rather than a casual side project running on autopilot somewhere else.
KalenAwaRe
September 26, 2026, at 9:37 pmHonestly impressed by how much useful content sits in such a small post, and a stop at caramelcovevault confirmed the rest of the site packs a similar punch, density without confusion is a hard balance to strike and this site has clearly cracked the code on it across many different topic areas covered.
Nealanype
September 26, 2026, at 9:50 pmA slim post with substantial content per word, and a look at nightorchardmarketplace maintained the same density, the content per word ratio is something I track informally and this site scores high on that ratio compared to most sources I read regularly which is a quiet indicator of careful editorial work behind the scenes.
RichardOdots
September 26, 2026, at 9:58 pmКешбэк на Vavada начисляется еженедельно реальными деньгами без обязательного отыгрыша на большинстве статусов программы лояльности. Шифрованные DNS-протоколы DoH и DoT помогают обойти блокировку на уровне провайдера без потери скорости соединения. Все детали доступны по адресу: vavada регистрация – https://vavada-air.com Такая полнота данных особенно ценна для тех, кто ведёт собственный подробный учёт результатов на длинной дистанции.
LarryGoano
September 26, 2026, at 11:02 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 26, 2026, at 11:16 pmfree spiny sk casino automaty na online hry online automaty bonus za registraci Fortuna free spiny na dnes hracie automaty bez stahovania online zdarma sizzling urobiЕҐ ruletu online
LarryGoano
September 26, 2026, at 11:25 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 26, 2026, at 11:29 pmavalon gold slot online casino bonus bez vkladu 2026 automaty admiral online zdarma Najlepsie kasino casino bonus 100 casina na slovensku
LarryGoano
September 26, 2026, at 11:45 pmМефедрон, Гашиш, Бошки, Альфа-ПВП
AlbertBox
September 27, 2026, at 12:00 amNow understanding why someone recommended this site to me a while back, and a stop at amberbrookstonebazaar explained the recommendation, sometimes recommendations make sense only after experience and this site has finally clicked into place as the kind of resource I now understand was being recommended for sound editorial reasons by my friend.
EganPap
September 27, 2026, at 12:15 amBookmark folder reorganised slightly to make this site easier to find, and a look at pineharborvault earned the same accessibility upgrade, the small organisational moves I make for sites I expect to return to often are themselves a signal of how much I trust them and this site triggered those moves naturally.
Clintonmut
September 27, 2026, at 12:18 amThis filled in a gap in my understanding that I had not even noticed was there, and a stop at coastharborcollective did the same, the kind of post that gives you more than you expected when you first clicked through from somewhere else, a real find for anyone curious about the area covered here.
Scotthow
September 27, 2026, at 12:23 ammobile kasГno slovenskГЅ slot v casino no deposit bonus poker hracie automaty zdarma bez registrace Vyskusaj free spiny bez vkladu dobit casino cez sms casino bonus 5 euro
NkrutkaTG833Ler
September 27, 2026, at 1:09 amКто делает реакции на посты в тг. На постоянку. Смотрел несколько, взял тут: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в телеграм[/url]. Повторно заказывал. Для постов хватило.
NakrutkaTG1050Royaw
September 27, 2026, at 1:58 amПосоветуйте сервис накрутку реакций в телеграм качественно. Нужны были реакции на несколько постов. Работают тут: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-474.ru[/url]. Оплатил — реакции встали быстро. Для канала зашло.
LarryGoano
September 27, 2026, at 2:09 amМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 27, 2026, at 2:29 amhracie automaty zdarma sizzling hot deluxe casino online slot machine kde hraЕҐ ruletu online Casino sms holdem poker game automaty turbo gold zdarma
LarryGoano
September 27, 2026, at 2:31 amМефедрон, Гашиш, Бошки, Альфа-ПВП
AbrahamOming
September 27, 2026, at 2:32 amThis one is staying open in a tab for the rest of the day so I can come back and re read certain parts, and a look at echostoneoutpost suggests I will be doing the same with a few more pages here too, this is going to be a deep dive over the coming hours.
Rolandodiale
September 27, 2026, at 2:34 amMost of the time I feel the open web is in decline and then I find a site like this, and a stop at snowtrailartisanoutlet reinforced that mood lift, the cumulative effect of finding occasional excellent independent content versus the cumulative effect of finding mostly mediocre content is real for the long term reader maintaining web habits today.
Scotthow
September 27, 2026, at 2:42 am21 blackjack online game casino grand mondial 7 € bonus casino slovensko Vyskusaj free spiny bez vkladu spiny za registraciu 2026 What sites give free spins no deposit
LarryGoano
September 27, 2026, at 2:51 amМефедрон, Гашиш, Бошки, Альфа-ПВП
AviTwire
September 27, 2026, at 3:34 amLooking at this from the perspective of someone tired of generic content the contrast is striking, and a look at cloudmeadowcollectivemart maintained that distinctive feel, sites with strong editorial identity stand out against the bland background of algorithmic content and this one has clearly developed an identity worth recognising through careful attention.
Scotthow
September 27, 2026, at 3:35 ampoker slovensko 2026 online online casino slots strategy casino bonusy k narozeninam Mobilne kasino 10 eur bonus casino za penize nove slovenske kasina
LandynNok
September 27, 2026, at 4:17 amPass this along to colleagues if the topic comes up, the framing here is sensible, and a stop at skyharborcollective adds more useful angles to share, the kind of content that improves conversations rather than just feeding them is what makes a resource genuinely valuable in professional contexts going forward over time and across project boundaries too.
LarryGoano
September 27, 2026, at 5:16 amМефедрон, Гашиш, Бошки, Альфа-ПВП
LarryGoano
September 27, 2026, at 5:38 amМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 27, 2026, at 5:41 amlive casino slovensko sk online casino hodnotenie automatu asena Kasino slovensko online casina slovensko vulkanbet 25 euro no deposit
Scotthow
September 27, 2026, at 5:54 amhracie automaty zdarma supra hot automaty zdarma frozen casino pre slovakov Casina na slovensku casino 5 eur za registrГЎciu hracie automaty online zadarmo sizzling
LarryGoano
September 27, 2026, at 5:58 amМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 27, 2026, at 6:48 amremember gulag slot live dealer online casino hry online automaty Zadarmo hracie automaty online free spiny za aktivitu coral live casino
LarryGoano
September 27, 2026, at 8:22 amМефедрон, Гашиш, Бошки, Альфа-ПВП
IsaacBoamn
September 27, 2026, at 8:24 amProbably going to mention this site in a write up I am working on later this month, and a stop at uplandridgecollectivemart provided more material for that potential mention, content worth referencing in my own published work rather than just personal reading is content with the highest endorsement level and this site has earned that endorsement.
Konnorfriem
September 27, 2026, at 8:31 amReading this with my morning coffee turned into reading the related posts with my morning coffee, and a stop at ravendockartisanbazaar stretched the morning further, content that pulls breakfast into a reading session rather than just accompanying it is content that has earned a higher claim on my attention than the average article does.
GavinLof
September 27, 2026, at 8:43 amA piece that left me thinking I had been undercaring about the topic, and a look at silverbrookvendorfoundry reinforced that mild concern, content that raises the appropriate weight of a subject without being preachy about it is doing important work and this site is providing that gentle elevation of attention for me consistently.
LarryGoano
September 27, 2026, at 8:45 amМефедрон, Гашиш, Бошки, Альфа-ПВП
Scotthow
September 27, 2026, at 8:53 amvolne spiny dnes da vinci slot monopoly live casino Hrat automaty za peniaze live casino 888 nove casino bonus bez vkladu
RobertCef
September 27, 2026, at 9:05 amнарко шоп тг трамадол таблетки купить купить Бошки, Гашиш, Мефедрон, Альфа-ПВП купить метадон купить метадон
Scotthow
September 27, 2026, at 9:06 amjoker hracie automaty nine casino recenzie hraci automaty za penize Kasino od 1 eur vklad nove online casino slovensko hracie automaty znacky
NkrutkaTG833Ler
September 27, 2026, at 9:08 amНужна накрутка накрутку реакций тг. Оптом. Смотрел несколько, взял тут: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в тг[/url]. Результат ок. Для постов хватило.
playf_nbMl
September 27, 2026, at 9:12 amSpiele jetzt seit dem Fruehling bei Play Fortuna angemeldet, also kann ich inzwischen aus eigener Erfahrung berichten. Ein Kollege hat es empfohlen, weil mich das Spielangebot angesprochen hat.
Die Spieleauswahl bei Play Fortuna ist wirklich umfangreich: Pragmatic, NetEnt und Nolimit City liefern die Titel. Gates of Olympus und Sweet Bonanza stehen ganz oben, die High-Volatility-Spiele machen mir am meisten Spass. Der Live-Bereich kommt von Evolution: alle bekannten Tischspiele plus die Showformate. Deutsche Tische sind abends verfuegbar.
Das Startpaket hier liegt bei 100 Prozent bis 500 Euro, dazu Freispiele in Tagesraten. Der Rollover betraegt 40-fach, streng aber branchenueblich. Die laufenden Promotionen sind nachzulesen auf [url=https://afc.gwx.temporary.site/play-fortuna-casino-sicherheit-im-uberblick/]play fortuna[/url] lohnt sich vorher zu lesen. Reload-Boni gibt es woechentlich.
Man kann ab 10 Euro starten. Visa, Mastercard und Skrill werden akzeptiert, Krypto ist auch moeglich. Auszahlungen ueber E-Wallet kamen innerhalb eines Tages, Auf die Karte waren es drei Werktage. Dokumente wurden schnell geprueft — Personalausweis hochgeladen und in Stunden bestaetigt.
Am Smartphone laeuft alles im Browser, funktioniert einwandfrei. Support antwortet auf Deutsch im Chat Antworten kommen zuegig. Es gilt eine Curacao-Lizenz, das sollte man bedenken. Auszahlungen wurden nie verweigert.
NkrutkaTG833Ler
September 27, 2026, at 9:44 amПосоветуйте кто ставит накрутку реакций тг. Без бана канала. Смотрел несколько, посоветовали этот: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в тг[/url]. Результат ок. На канал пойдёт.
LyleTus
September 27, 2026, at 9:53 amNow recognising the editorial wisdom of letting some questions remain open at the end, and a look at crystalharbortradehouse continued that intellectual honesty, content that does not force closure on contested questions is content that respects the limits of knowledge and this site has clearly developed the maturity to know when to leave space.
lotto_fbMa
September 27, 2026, at 9:55 amSigned up at Lottoland since the start of summer, enough sessions to see how it actually works. Originally came for the lottery side, but ended up staying for the casino as well. The game library goes deeper than you would think, combining lotto draws with slots and table games.
Providers on the casino side include Pragmatic Play, NetEnt, Play’n GO and Blueprint. Gates of Olympus and Starburst are both here, though the total count is lower than a standalone casino. The real draw is the lottery product: results from lotteries around the world are covered, and the jackpot sizes can be staggering. Instant win titles round things off.
The welcome offer here depends on where you are: often a free bet plus some bonus funds. The casino side gets its own promotions from time to time, although the lotto side gets more attention. Current promotions and terms should be verified at [url=https://alabsaudio.com]lottoland[/url] before you sign up. Rollover requirements are typical for the industry.
You can start with as little as a pound: one pound for lottery bets, ten for casino. Payment methods include cards, PayPal and prepaid options. Cashouts via e-wallet took under twenty-four hours, bank transfers ran the usual few days. Verification was straightforward — ID check passed on the first attempt.
Mobile works through a dedicated app, and it loads quickly. Draw results appear as they happen, with the casino accessible from the same app. Customer service responds on chat, wait times are short. Holds licences from Gibraltar and the UKGC, so there is genuine oversight. Overall a solid platform.
Scotthow
September 27, 2026, at 9:59 ampoker texas holdem casino bonus promo code recenze online casina Fortuna dnesne free spiny daЕ€ za nevГЅhernГ© hracie automaty bet blackjack online
NakrutkaTG1050Royaw
September 27, 2026, at 10:14 amИщу кто делает накрутку реакций в тг быстро. Нужны были эмодзи на канал. Нашёл: [url=https://nakrutka-reakcij-v-tg-1050.ru]накрутка реакций телеграм[/url]. Оплатил — без нареканий. Буду ещё брать.
GerardoSkess
September 27, 2026, at 10:37 amWorth saying that the prose reads naturally without straining for style, and a stop at lanternorchardoutpost maintained the same unforced quality, writing that achieves elegance without effort is the highest tier and this site has clearly worked out how to land that effortless quality consistently rather than only on the writers best days.
NakrutkaTG1050Royaw
September 27, 2026, at 10:45 amПодскажите кто делает накрутку эмодзи в тг быстро. Нужны были эмодзи на канал. Вот сервис: [url=https://nakrutka-reakcij-v-tg-1050.ru]накрутка реакций телеграм[/url]. Заказал — без нареканий. Норм вариант.
Wilfordruila
September 27, 2026, at 10:50 amBookmark earned and the bookmark feels like a permanent addition rather than a maybe, and a look at alpinestoneoutpost confirmed that permanent status, the difference between durable bookmarks and ephemeral ones is something I have learned to feel quickly and this site triggered the durable feeling almost immediately during my first read here.
RichardOdots
September 27, 2026, at 11:18 amКаталог провайдеров Вавада пополняется еженедельно, а новинки попадают в отдельную витрину с датой релиза и указанием RTP. Фильтры каталога по провайдеру, механике и уровню волатильности сохраняются между сессиями в виде именованных пресетов. Актуальный адрес площадки: вавада казино – https://vavada-air.com Такая прозрачность работы формирует базовый уровень доверия с первого визита и снимает главные страхи новичков.
RobertCef
September 27, 2026, at 11:29 amкупить амф купить экстази бошки гашиш в эмиратах купить Бошки, Гашиш, Мефедрон, Альфа-ПВП купить кокаин онлайн амфетамин кокаин купить
Rufuston
September 27, 2026, at 11:31 amLiked how the post handled an objection I was forming as I read, and a stop at flintstonegalleria similarly anticipated where my thinking was going next, the rare writer who can predict reader concerns and address them in advance is doing something most online content fails to do despite that being basic editorial work.
RobertCef
September 27, 2026, at 11:52 amсорта конопли купить заказать лирика 300 купить Бошки, Гашиш, Мефедрон, Альфа-ПВП закладки меф купить наркотики мефедрон
Scotthow
September 27, 2026, at 12:04 pmsynot hracГ automaty online otГЎДЌky zdarma za registraciu roulette game online free Dnesne free spiny bez vkladu automaty online bonus zdarma 888 casino code new casino free signup bonus
Donnytreni
September 27, 2026, at 12:09 pmA particular pleasure to read this with a fresh coffee, and a look at hazelharborcollectivemart extended the pleasure across more pages, content that pairs well with quiet morning rituals is something I have come to value highly and this site has the kind of energy that fits naturally into a calm reading routine.
RobertCef
September 27, 2026, at 12:11 pmкупить меф куплю закладки соли купить Бошки, Гашиш, Мефедрон, Альфа-ПВП Купить Бошки, Шишки, Мефедрон, Кокаин трамадол купить без рецепта
Scotthow
September 27, 2026, at 12:17 pmfree spiny fortuna 5 € bonus bez vkladu 2026 automati hri zdarma hrat Kasino hry online casino bez vkladu bonus sms casino online
DevinLeami
September 27, 2026, at 12:25 pmThanks for putting in the work to make this approachable, plenty of sites cover the same ground but most do it badly, and a quick visit to rainharborcollective confirmed this one stands apart, simple language and useful examples without anyone trying to sell me anything along the way which I really appreciated.
Sylvestertroff
September 27, 2026, at 12:47 pmA clear case of writing that does not try to do too much in one post, and a look at rosecovevault maintained the same scoped discipline, posts that try to cover too much end up covering nothing well and this site has clearly chosen scope discipline as a core editorial principle which shows up clearly in what I read.
LelandFiesy
September 27, 2026, at 12:51 pmIf I were grading sites on this topic this one would receive high marks, and a stop at glassbrookartisanmart continued earning those high marks, the informal grading I do mentally for content sources is something I take seriously even though it is informal and this site has been receiving consistent high marks across multiple sessions today.
Scotthow
September 27, 2026, at 1:09 pmotГЎДЌky zdarma za registraciu hracie automaty kolko percent dava vyhry slovenske online blackjack Ruleta s vyhrou realnych penazi Which online casino actually pays real money live blackjack online
Connorbog
September 27, 2026, at 1:18 pmSolid information that lines up with what I have been hearing from other reliable sources, and after my visit to hazelharborvendoratelier I was even more certain of that, this site checks out which is something I value highly when so many places online play loose with the facts to chase a quick click.
Edmundler
September 27, 2026, at 1:36 pmFound this via a link from another piece I was reading and the click was worth it, and a stop at pearldockartisanhouse extended the value across more material, the open web still rewards clicking through citations when the underlying writers care about each other work and this site clearly belongs to that network.
Lelandsag
September 27, 2026, at 1:53 pmTook me back a step or two on an assumption I had been making, and a stop at securebuyingstore pushed that reconsideration further, writing that gently corrects the reader without being aggressive about it is a rare diplomatic skill and the team here clearly knows how to land critical points without turning readers off.
RichardOdots
September 27, 2026, at 1:57 pmПриветственный пакет Казино Вавада активируется автоматически после первого депозита без ручного ввода промокода. Настройки интерфейса синхронизируются между устройствами через профиль, поэтому переход с ноутбука на смартфон не требует перенастройки. Переходите на площадку по ссылке: vavada казино – https://vavada-air.com Такая техническая грамотность в работе с сетевым слоем заметно расширяет доступность площадки в разных регионах.
Gabrielpef
September 27, 2026, at 2:01 pmReading this on a difficult day was a small bright spot, and a stop at crystalcovevault extended that brightness, content that improves a hard day is content that has earned a particular kind of place in my reading habits and this site is occupying that uplifting role for me today which I appreciate clearly.
Wileyreedy
September 27, 2026, at 2:21 pmPicked a friend mentally as the audience for this and decided to send the link, and a look at plumcoveartisanoutlet confirmed the send was the right choice, choosing whom to share content with is a small act of curation that I take more seriously than the public sharing most platforms encourage these days online.
HarryCrync
September 27, 2026, at 2:46 pmEasy to recommend, the content speaks for itself without needing additional praise from me, and a stop at elmwillowemporium only adds more reasons to send people this way, the kind of generous resource that benefits its readers without demanding anything in return is increasingly rare and worth recognising clearly today across the broader open internet.
ClydeHok
September 27, 2026, at 2:59 pmNow setting up a small reminder to revisit the site on a slow day, and a stop at timbercovegoodsstore confirmed the reminder was a good idea, planning return visits is a small organisational act that signals trust in ongoing quality and this site has earned that planned return through consistent performance across the pieces I have read so far.
Scotthow
September 27, 2026, at 3:15 pmfortuna online casino vstupne bonusy casino ceske casino bonus za registraci bez vkladu Postup ako hrat automaty 40 euro no deposit bonus automaty hry zdarma 81
Scotthow
September 27, 2026, at 3:28 pmnajlepsie slovenske kasino kajot 5 eur bonus promo kod free spiny zdarma Tipy ako hrat automaty automaty zdarma online sazka hracie automaty zdarma bezregistrace
luchshie_obSr
September 27, 2026, at 3:38 pmЕсли вы хотите продвинуть свой сайт, обязательно изучите опыт [url=https://workspace.ru/blog/samye-izvestnye-seo-specialisty-rossii-kogo-chitat-slushat-i-u-kogo-uchitsya-v-2026-godu/]рейтинг seo специалистов[/url], чтобы выбрать надежного эксперта.
Деятельность SEO-экспертов выходит за рамки технических аспектов.
Michaeldib
September 27, 2026, at 3:47 pmhttps://intercom.help/welcome-bonus/en/articles/17065468-1xbet-ipl-promo-code-egypt-2026-win88kk-100-bonus
LouisDuM
September 27, 2026, at 3:47 pmhttps://intercom.help/bonuscode/en/articles/17035700-melbet-бћ”-бћљбћ¶бћЂ-бћљбћ„-бћњбћ¶бћ“-бћЉбћ¶бћЂ-бћ”-бћљбћ¶бћЂ-бћЉбџ†бћ”бћјбћ„-бћЂбћ-бћ–бћ»бћ‡бћ¶-wap200-100-up-to-130
DarrellPrack
September 27, 2026, at 3:47 pmhttps://intercom.help/bonuscode/en/articles/16572224-chicken-road-separating-real-strategy-from-wishful-thinking
DonaldPes
September 27, 2026, at 3:48 pmhttps://intercom.help/bonuscode/en/articles/17177079-мелбет-промокод-без-депозита-2026-bro888
Scotthow
September 27, 2026, at 4:21 pm21 blackjack online blackjack online game star joker slot Kajot automaty online 800 casino bonus What are the top 10 casino apps
LutherTussy
September 27, 2026, at 4:35 pmExcellent execution from start to finish, the post never loses its rhythm and the points stay sharp, and a quick stop at timbermarket kept the same level going, consistency like this across a site is the marker of a serious operation rather than a casual side project running on autopilot somewhere else.
Edgartot
September 27, 2026, at 4:50 pmA clear cut above the usual noise on the subject, and a look at seacoveoutpost only made that gap wider in my view, the kind of place that earns its visitors through quality rather than through aggressive marketing or sponsored placements which is increasingly the only way most sites stay afloat across the modern web.
Knoxpak
September 27, 2026, at 4:57 pmFound a small mental shift after reading this, the framing here is just a bit different from the standard takes online, and a look at alpinegrovegoodsstore extended that fresh perspective across more material, the rare site whose voice actually changes how you think about something rather than just confirming existing beliefs.
QuinnZen
September 27, 2026, at 5:09 pmNice to see a post that does not try to overcomplicate the basics for the sake of looking smart, and once I looked at stoneharboroutpost the same direct tone was there too, which honestly makes a difference when you are short on time and want answers without long pointless intros.
Heathduemi
September 27, 2026, at 5:13 pmWorth saying this site reads better than most paid newsletters I have tried, and a stop at mintorchardvault confirmed that comparison, the bar for free content is often lower than for paid but this site clears the paid bar consistently and that says something about the editorial approach behind the work being published here regularly.
ZionFew
September 27, 2026, at 5:15 pmMy friends would appreciate a few of these posts and I will be sending links accordingly, and a look at echoharborcollectivemart added more pages to my share queue, content that earns shares to specific people in specific contexts is content with social utility and this site is generating those targeted shares from me consistently lately.
Gregoryacout
September 27, 2026, at 5:20 pmClosed several other tabs to focus on this one as I read, and a stop at crowncovevault held my undivided attention the same way, content that earns full focus in an attention environment full of competing pulls is content doing something genuinely well and the team behind it deserves recognition for that achievement consistently.
Xaviercig
September 27, 2026, at 5:21 pmWithout overstating it this is a quietly excellent post, and a look at plumcovegallery extended that quiet excellence, content that earns superlatives without demanding them through marketing language is content that has truly earned them through the substance and this site has clearly produced work in that earned excellence category today.
Tonyavali
September 27, 2026, at 5:24 pmIf quality blog writing is dying as people sometimes claim then this site is one piece of evidence that it has not died yet, and a look at ravensummitcollective extended that evidence, the broader cultural question about online writing has empirical answers in specific sites and this one is contributing to a more optimistic answer overall.
JoelJemia
September 27, 2026, at 6:20 pmPicked this up between two other things I was doing and got drawn in completely, and after fernbrookvendorfoundry my original tasks were completely forgotten for a while, content that derails a workflow in a positive way by being more interesting than what you were already doing is rare and worth recognising clearly.
Scotthow
September 27, 2026, at 6:24 pmfruit shake automaty zdarma live casino 2026 king casino bonus mfortune free bonus Online hry online casina na slovensku golden star casino
Scotthow
September 27, 2026, at 6:37 pmcasino hry free games play vyherni automaty zdarma gg bet casino bonus za registraciu bez vkladu 2026 Online automaty kajot casina vstupne bonusy hraci automaty zdarma ultra hot
Davenop
September 27, 2026, at 7:03 pmStarted forming counter examples to test the claims and the post handled most of them implicitly, and a look at woodtrailartisanhouse continued that anticipatory style, writers who think two steps ahead of the critical reader save themselves from a lot of follow up work and this writer has clearly internalised that habit consistently.
Jeanbeavy
September 27, 2026, at 7:23 pmBetter than the average post on this subject by some distance, and a look at skymeadowtradehouse reinforced that, you can tell within the first paragraph that the writer here actually cares about the topic rather than just covering it for the sake of having something to publish that week or that day.
Eugenehes
September 27, 2026, at 7:30 pmpractice blackjack online free 5e no deposit bonus hracie automaty sturovo Slovenske kasino automaty ruleta zdarma category valcove hracie automaty fortuna
Franklinfloat
September 27, 2026, at 7:35 pmFollowing the post through to the end without my attention drifting once, and a look at canyonharborgoodsstore earned the same uninterrupted attention, content that holds attention without manipulating it is content with substantive pull and this site has demonstrated that substantive pull across multiple pieces in a single reading session reliably here today.
Thomasgek
September 27, 2026, at 7:55 pm[url=https://novobancpt.com/]NOVO BANCO LOGIN[/url]
A página do NOVO BANCO LOGIN tem uma estrutura objetiva e apresenta indicações claras para localizar o acesso aos serviços digitais.
NkrutkaTG833Ler
September 27, 2026, at 8:19 pmПодскажите контору реакции в телеграм. Быстро и недорого. Смотрел несколько, остановился на этом: [url=https://nakrutka-reakcij-v-tg-1682.ru]nakrutka-reakcij-v-tg-1682.ru[/url]. Претензий нет. На канал пойдёт.
Angelojepsy
September 27, 2026, at 8:39 pmThis stands out compared to similar posts I have read recently, less noise and more substance, and a look at sagedockartisanbazaar kept that gap going, you can really feel the difference between content made by someone who cares versus content made to fill a publishing schedule for an algorithm trying to keep growing somehow.
GilbertNoige
September 27, 2026, at 8:43 pmA piece that exhibited the kind of patience that good writing requires, and a look at birchharboroutpost continued that patient quality, hurried writing is easy to spot and this site reads as having been written without time pressure which produces a different feel than the rushed content that dominates much of the modern blog space.
NakrutkaTG1050Royaw
September 27, 2026, at 8:51 pmИщу кто делает накрутку реакций телеграм оптом на канал. Нужны были реакции на несколько постов. Вот сервис: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-1050.ru[/url]. Заказал — реакции встали быстро. Для канала зашло.
KyleCok
September 27, 2026, at 9:19 pmReading this confirmed that the topic deserves more careful attention than it usually gets, and a stop at oceanoutfitters extended that elevated framing, content that raises the appropriate weight of a subject without being preachy about it is serving a quiet but important editorial function for the broader cultural conversation about it.
JordanAdvah
September 27, 2026, at 9:23 pmNow appreciating that I did not feel exhausted after reading, and a stop at rainharboroutpost extended that energising quality, content that leaves me with more attention than it consumed is rare and the gap between draining and energising content is real over the course of a typical day spent reading widely online.
Andresuele
September 27, 2026, at 9:27 pmThanks for putting in the work to make this approachable, plenty of sites cover the same ground but most do it badly, and a quick visit to granitestoneexchange confirmed this one stands apart, simple language and useful examples without anyone trying to sell me anything along the way which I really appreciated.
Ernestsuify
September 27, 2026, at 9:35 pmonline casina recenze hracie automaty bez registracii What casino gives you free spins for signing up Retro spiny blackjack online slovensko online automaty zadarmo
Josephacest
September 27, 2026, at 9:45 pmNow recognising that this site has earned a place in the small group of resources I treat as authoritative, and a stop at coastcoveartisanmarket confirmed that placement, the difference between resources I trust and resources I just consume is real and this site has clearly moved into the trusted category through consistent quality over time.
KaiAsype
September 27, 2026, at 9:48 pmNow appreciating that the post left me with enough to say in a follow up conversation, and a look at amberharborstudio added more material for those follow ups, content that prepares me for related conversations rather than just informing me alone is content with social utility and this site provides that social armament reliably for me.
IgnaciogeabE
September 27, 2026, at 10:26 pmCame back to this an hour later to reread a specific section, and a quick visit to valevendor also drew a second look, content that pulls you back rather than letting you move on permanently is the kind I want to fill my browser bookmarks with in 2026 and beyond as the open internet evolves.
Ernestsuify
September 27, 2026, at 10:40 pmkajot 5 eur automaty online vklad sms casino za registrГЎciu bonus Ruleta za peniaze hracia automaty online top mobile spigo casinos
Davonclesk
September 27, 2026, at 10:43 pmA genuine compliment to the writer for keeping the post focused on what mattered, and a look at rainharbortrading continued that disciplined focus, focus is a editorial choice that compounds across many small decisions and this site has clearly made those small decisions consistently across what I have read so far this week here.
ChaseBob
September 27, 2026, at 11:58 pmReading this slowly to give it the attention it deserved, and a stop at maplestoneemporium earned the same slow read, choosing to read slowly is a small act of respect for content quality and very few sites earn that respect from me but this one did so without any explicit ask which is the cleanest way.
karkasnyy_pnSr
September 27, 2026, at 11:59 pmЕсли вы хотите быстро и качественно оформить [url=https://karkasnye-doma-spb12.ru]каркасный дом под ключ в спб[/url], обращайтесь к проверенным специалистам.
Для возведения каркасного дома применяется прежде всего древесина.
reyting_cuMi
September 27, 2026, at 11:59 pmЕсли вы хотите выбрать качественное обучение, обязательно ознакомьтесь с [url=https://vc.ru/education/3144210-chestnyy-reyting-kursov-po-seo]рейтинг курсов seo[/url], чтобы найти оптимальные варианты.
Четвертый раздел рейтинга содержит отзывы и оценки участников.
rever_xfKl
September 28, 2026, at 12:15 amSigned up with Revery Play since around Easter, so the first impression stage is well past. Found it through a comparison site, mainly because the bonus terms elsewhere were ridiculous. The game selection here is decent, with a good mix of slots, table games and live dealer.
Providers include Pragmatic Play, NetEnt, Play’n GO, Evolution for the live side. The usual suspects sit at the top, though I spend more time on the newer releases. Live casino is Evolution, so Lightning Roulette, Crazy Time, blackjack and baccarat. Dealers are on twenty-four seven, although peak hours can be crowded.
The introductory package at Revery Play offers a matched deposit plus spins. Rollover is thirty-five times the bonus, fairly standard for this market. Current offers and promo codes can be checked on [url=https://studiosvaria.com/revery-play-review-uk-casino-bonus-payments-mobile-app-overview/]revery play[/url] before you commit funds. Cashback and free spin drops appear regularly.
You can start from a tenner. Visa, Mastercard, PayPal and Paysafecard are accepted. PayPal payouts arrived quickly, card withdrawals took two to three working days. Identity verification went smoothly — passed on the first attempt.
Mobile is browser based and performance is smooth. You play through the site, so no download required. Support responds on live chat in English and they read the question before answering. They hold a Curacao licence, so be aware of that going in. Bottom line, my money has arrived every time.
Jamalunare
September 28, 2026, at 12:16 amA piece that handled a controversial angle without becoming heated, and a look at caramelbrookvendorfoundry continued that calm engagement, content that can address contested topics without inflaming them is doing rare diplomatic work and this site has clearly developed the editorial maturity to handle sensitive material with the appropriate temperature of writing throughout.
karkasnyy_ifKt
September 28, 2026, at 12:32 amЕсли вы ищете надёжный и быстрый способ построить уютное жильё, обратите внимание на [url=https://karkasnye-doma-spb13.ru]строительство каркасных домов под ключ[/url].
Каркас обшивается панелями, благодаря чему формируются стены и крыша.
KeenanSot
September 28, 2026, at 12:42 amAppreciate the work that went into laying this out so clearly, every section earns its place without filler, and a look at woodharborgoodsstore confirmed the same care, definitely the kind of place that deserves a return visit when the topic comes up again later in the future or for any related question.
Ernestsuify
September 28, 2026, at 12:45 amhracie automaty na slovensku ice casino 25 euro bonus online automaty free spiny Najnovsie kasino na slovensku hrat automaty zdarma diamanty zan zo casino
Ernestsuify
September 28, 2026, at 12:58 amdouble star casino n1bet casino bonus How to claim 200 bonus on 888 casino Postup ako hrat automaty casino bonus bez vkladu za registraciu blek end white 81 automaty zdarma wildove
TerrenceMex
September 28, 2026, at 1:21 amSpeaking from the perspective of having read widely on the topic this site offers something distinct, and a look at stoneharborcollectivemart reinforced that distinctness, the rare site that contributes something genuinely original to a saturated topic is the rare site worth following carefully and this one has demonstrated that original contribution capability today.
MicahPloks
September 28, 2026, at 1:39 amNow adding a small note in my reading log that this site is one to watch, and a look at wavemeadowtradehouse reinforced the watch status, the few sites I track deliberately rather than encounter accidentally are sites I expect ongoing returns from and this one has cleared the bar for that elevated tracking based on what I read.
Ernestsuify
September 28, 2026, at 1:52 amkasГna s minimГЎlnym vkladom 20 eur promo kГіdy casino bez vkladu casino na sms Kasino 20 eur vip lounge casino zahranicne kasina pre slovakov
Jaybak
September 28, 2026, at 1:56 amIf you scroll past this site without looking carefully you will miss something, and a stop at gladeharbortrading extended that mild warning, the surface of the site does not advertise its quality loudly which means careful attention is required to recognise what is being offered here which is itself a kind of editorial signal.
TodFub
September 28, 2026, at 2:09 amClosed three other tabs to focus on this one and never opened them again, and a stop at brightharborcollectivemart similarly held attention exclusively, content that crowds out other reading from working memory is content with real density and this site has demonstrated that density across multiple pages I have visited so far this morning.
Juliodug
September 28, 2026, at 2:19 amDecent post that improved my afternoon a small amount, and a look at mossharboroutpost added a bit more to that, sometimes the small wins online add up over time and a useful site like this one is the kind of place that contributes consistently to those small wins for me lately across many different topics I follow.
ArnoldBup
September 28, 2026, at 3:44 amFelt no urge to argue with the conclusions even though I started the post slightly skeptical, and a look at skyharboroutpost maintained that pattern, writing that earns agreement through clarity of argument rather than rhetorical pressure is the kind I find most persuasive and the kind I want to read more of these days.
Ernestsuify
September 28, 2026, at 3:56 amautomaty zdarma online hry ako hraЕҐ ruletu online a vyhraЕҐ fortune double demo Novootvorene kasino na slovensku nove casino na slovensku blackjack online with friends
Todtuh
September 28, 2026, at 4:08 amBeats most of the alternatives on the topic by a noticeable margin, and a look at apricotharbortrading did not change that at all, this is one of the better corners of the open internet for this kind of content and I am glad I clicked through rather than skipping past quickly like I usually do.
Ernestsuify
September 28, 2026, at 4:10 aminfinite blackjack online hracie automaty na stiahnutie zadarmo do mobilu casino min deposit 1 € Slovenske online casina najvacsie kasГno na slovensku gametwist kasino slots hracie automaty zdarma funstage
Franklintiz
September 28, 2026, at 4:19 amReading this prompted me to subscribe to my first newsletter in months, and a stop at ivorycrate confirmed the subscribe was the right call, content that earns a newsletter signup is content that has cleared a higher trust bar than a casual visit and this site has clearly earned that level of commitment from me.
DannyBof
September 28, 2026, at 4:30 amAppreciate that you did not pad this with fluff to hit a word count, the post says what it needs to say and stops, and a look at elmharborgalleria did the same, brevity here feels intentional not lazy which is a distinction many writers miss completely sometimes when they are working under deadlines.
Ernestsuify
September 28, 2026, at 5:03 amWhat casino gives you free spins for signing up hracie automaty kolko percent dava vyhry peniaze za hry Free spin na hracich automatoch ako hrat blackjack automaty zdarma online sazka
CesarLulky
September 28, 2026, at 5:39 amStands apart from similar pages by actually being useful, that is high praise these days, and a look at berrycovevault kept that standard going, you can tell when a site is built around the reader versus around metrics and this one clearly belongs to the first category for sure based on what I read.
EarlPhify
September 28, 2026, at 6:07 amNow adjusting my expectations upward for the topic based on this post, and a stop at ferncovecommercehub continued that bar raising effect, content that resets what I think is possible on a subject is doing real work in shaping my standards and this site is providing those bar raising experiences at a notable rate during sessions.
DomenicDup
September 28, 2026, at 6:07 amReally clear writing, the kind that makes you want to share the link with someone who has been asking about the topic, and a quick browse through acornstonegalleria only made me more sure of that, the information here stays useful long after the first read is done which says a lot.
Zachariahritty
September 28, 2026, at 6:10 amWorth recognising that the post handled a familiar topic without reaching for any of the obvious hot takes, and a stop at flintridgecollectivemart continued that fresh treatment, sites that find new angles on subjects others have exhausted are sites worth following carefully and this one has clearly developed that exploratory instinct through patient practice.
x777newlink
September 28, 2026, at 6:23 amGlad I found the updated link. The games are exciting and the bonuses are actually fair. Keep it up x777newlink!
EthanDealp
September 28, 2026, at 6:28 amLiked that the post left some questions open rather than pretending to settle everything, and a stop at quickstonegalleria continued that intellectual honesty, content that respects the limits of its own claims is more trustworthy than content that overreaches and this site has clearly figured out which positions it can defend confidently.
Jettthola
September 28, 2026, at 6:30 amMost of my reading time goes to a small number of trusted sources and this one is now joining that group, and a stop at seacovegallery reinforced the group membership, the few sites that earn a place in my regular rotation are sites I expect ongoing returns from and this one has earned that elevated position consistently.
BertVop
September 28, 2026, at 6:34 amNow thinking about whether the writer might publish a longer form work I would buy, and a look at plumridgegoodsstore suggested the same depth would translate, content that makes me want to pay for related work in other formats is content that has earned commercial trust as well as attention trust and this site has both clearly.
CesarBoath
September 28, 2026, at 6:44 amHonest reaction is that this is the kind of writing I would defend in a conversation about good blog content, and a look at dawnridgeemporium reinforced that, the rare site whose work I would actively recommend rather than just tolerate is the kind I want to support through return visits regularly.
Emersonchups
September 28, 2026, at 6:49 amComfortable reading experience throughout, no jarring tone shifts and no awkward formatting, and a look at auroracoveoutpost kept that smooth feel going, the kind of editorial polish that goes unnoticed when present but glaring when absent is something this site has clearly invested in across the broader content as well which deserves recognition.
rever_quKl
September 28, 2026, at 7:04 amBin da jetzt etwa einem halben Jahr aktiv, angefangen durch Zufall bei der Suche nach was Neuem. Der Grund warum ich bei Play Fortuna geblieben bin, war schlicht die Spielauswahl. Grob 4000 Spiele findest du, Play’n GO, Yggdrasil und Pragmatic sind am starksten vertreten. Ich hange meistens an Gates of Olympus, Sweet Bonanza ab und zu wenn die Laune stimmt.
Live-Tische sind fast nur Evolution, womit ich gut leben kann. Tische mit deutschen Dealern sind vorhanden zu den ublichen Zeiten, Crazy Time plus die ublichen Gameshows nehme ich fur die Abwechslung. Nicht gelogen: ab und zu hakt der Stream, kann aber auch mein Router sein.
Zum Bonus: 100 Prozent auf die erste Einzahlung plus Freispiele habe ich bekommen. 40x Wagering — nicht super, aber Standard. Es gab auch mal Aktionen ohne Einzahlung, da muss man dran sein. Welche Codes gerade gultig sind schaust du besser direkt bei [url=https://hashkar.com/2026/09/23/play-fortuna-casino-mobile-app-nutzung-registrierung-bonus-sicherheit-fur-deutsche-spieler/]play fortuna casino[/url] nach, bevor du einzahlst.
Einzahlen geht ab 10 Euro, bei mir lauft es uber Neteller. Visa, Mastercard, die ublichen E-Wallets und Bitcoin sind alle da. Meine Auszahlungen bei Play Fortuna waren nach ein bis zwei Tagen da — beim ersten Mal dauerte es langer, Ausweis und Rechnung hochladen, dann war Ruhe.
Der Account ging fix, Mail, Passwort, Wahrung wahlen. Am Handy lauft alles im Browser und lauft auf dem Android sauber. Der Support antwortet im Chat nach wenigen Minuten, deutsch, wirkt aber teils nach Textbaustein. Was mich argert: die Lizenz von Play Fortuna kommt aus Curacao, also keine Regulierung nach deutschem Glucksspielstaatsvertrag — wer hier aus Deutschland spielt sollte das wissen. Ich nehme dafur die fehlende 5-Sekunden-Regel in Kauf, aber das ist Geschmackssache.
rever_epKl
September 28, 2026, at 7:05 amHab mich vor ein paar Monaten dort angemeldet, also rede ich nicht komplett ins Blaue. Crypto Control hat eine echt volle Lobby — weit uber 2000 Slots, hab ehrlich gesagt nicht nachgezahlt. Pragmatic Play und Betsoft sind reichlich dabei, Book of Dead ist mein Dauerbrenner.
Das Startpaket war offen gesagt der Ausloser, warum ich mich registriert hab. 100% bis 500 Euro plus 200 Freispiele, aufgeteilt uber mehrere Tage. Der Haken dabei: man muss 35-fach umsetzen, das ist branchenublich, aber kein Selbstlaufer. Es gab auch mal 20 Freispiele ohne Einzahlung, die Promos andern sich aber laufend.
Was gerade lauft, steht direkt auf [url=https://grandsuite.santachiarahotel.com/blog/2026/09/23/solana-casino-bonus-guide-alles-zu-willkommensbonus-und-umsatzbedingungen/]solana casino[/url] , kurz die AGB uberfliegen schadet nie. Eingezahlt werden mussen mindestens 20€, das Anmelden war in zwei Minuten durch.
Was das Abheben angeht lief es besser als gedacht: per Krypto ging’s in unter zwei Stunden, uber Neteller etwa einen Werktag. Mit Visa oder Mastercard geht’s genauso, da wurde ich aber mit zwei bis drei Tagen rechnen. Die Verifizierung bei Crypto Control war nervig — Ausweis, Selfie, Adressnachweis, das volle Programm.
Abends hang ich meistens im Live-Bereich rum. Evolution liefert da ab, Crazy Time zieht mich immer wieder rein, und naturlich jede Menge Roulettevarianten. Fur uns aus Deutschland sind ein paar deutschsprachige Tische dabei, langst nicht uberall, aber besser als nichts.
Mobil nutze ich einfach den Browser, App fehlt, stort mich ehrlich gesagt kaum. Der Support von Crypto Control antwortet im Chat auf Deutsch, meistens innerhalb von funf Minuten, manchmal muss man halt zweimal nachhaken. Die Lizenz kommt aus Curacao, sprich kein deutscher Erlaubnisschein — muss man wissen.
rever_jwKl
September 28, 2026, at 7:05 amSto su Slot Shopper dallo scorso inverno e dopo un po’ di giri posso dire due cose sensate. La libreria e bella grossa, circa 2.000 titoli se non ho contato male, con Pragmatic Play che domina un po’ tutto. Gates of Olympus resta il mio solito punto di partenza, poi ci sono Big Time Gaming e Microgaming per chi vuole volatilita alta.
Il settore live gira su Evolution, quindi sai gia cosa aspettarti: croupier veri, tavoli in italiano in certe fasce orarie, e ovviamente Crazy Time e compagnia sempre pieni di sera. L’unica cosa che mi ha infastidito: in 4G debole il flusso perde colpi, magari e la mia rete, non voglio dare colpe a caso.
Sul pacchetto iniziale: su Slot Shopper il primo bonus e circa 150% fino a 200€ piu 100 free spin, spalmati su qualche giorno. Il wagering e 35x sul bonus, nella norma per il mercato italiano. Ci sono anche dei giri senza deposito ogni tanto, e comunque conviene guardare le promo aggiornate su [url=https://new.hribacademy.com/slotshopper-cosa-devi-sapere-prima-di-scegliere-un-casino-online/]slotshopper[/url] prima di metterci soldi.
Deposito minimo 20€, registrazione veloce con documento da caricare per il KYC. Io deposito con Skrill con accredito in un giorno e mezzo. Carte, Skrill, Neteller, bonifico e qualche opzione in Bitcoin, quindi scegli tu. Il primo prelievo e stato piu lento per la verifica.
Da telefono va tutto dal browser, si comporta bene anche su schermo piccolo, nulla di spettacolare ma funzionale. Il supporto di Slot Shopper risponde in italiano in chat, di solito entro dieci minuti, mi hanno sistemato un bonus bloccato senza discussioni. La licenza e Malta Gaming Authority, e sinceramente questo mi tranquillizza piu delle promo.
rever_ouKl
September 28, 2026, at 7:08 amBeen playing at Trino Casino for about four months now, usually in the evenings, so read this for what it’s worth. Signed up because of a mate’s recommendation, and sign-up took under five minutes — email, password, done, though they did want ID later, which is normal.
The lobby is deeper than I thought — roughly 3,000+ slots and tables last time I looked. Pragmatic Play is everywhere, so you get the obvious ones — Gates of Olympus sitting right at the top. Play’n GO brings Book of Dead, and there’s a decent amount of NetEnt, Yggdrasil and Big Time Gaming knocking about. My go-to is Big Time Gaming stuff when I’ve got the bankroll for it.
The welcome offer on Trino Casino was 100% up to ?500 plus 200 free spins, spread over a few deposits. Wagering is 40x, and that’s neither great nor awful. Min deposit sits at ?20. There’s a no-deposit spins offer now and then — it rotates, so it’s worth a check the live promos over on [url=https://caelumcapital.net/?p=14145]casino trino[/url] before you commit.
Cashouts are the bit that matters, and here Trino Casino has behaved. Cashed out ?420 to Skrill last week and it landed the same evening. Visa and Mastercard work, Skrill and Neteller are faster, and they take crypto if that’s your thing. The one thing that annoyed me: bank transfers dragged on for nearly a week the first time.
Live chat is 24/7 and the people there aren’t just copy-pasting scripts, but getting a human can take a good quarter of an hour on a Saturday night. The live section is all Evolution, so actual dealers, decent blackjack and roulette tables, and Crazy Time and Lightning Roulette if you like the game show stuff — I don’t, much. No app, only a browser version, and it loads quick enough but occasionally logs me out mid-spin.
Ernestsuify
September 28, 2026, at 7:09 amhrat automaty zdarma sizzling bonus bez vkladu za registraciu automaty online free Hry o peniaze kajot automaty hrat zdarma 5 € casino
Ernestsuify
September 28, 2026, at 7:22 amcasino olympic eurovea best mobile spigo casino vstupne bonusy casino Online casino za peniaze fortuna hracie automaty jak obelstit hraci automaty
playf_djMl
September 28, 2026, at 7:22 amSpiele jetzt seit dem Fruehling bei Play Fortuna angemeldet, daher laesst sich mittlerweile eine realistische Einschaetzung zu geben. Ein Kollege hat es empfohlen, weil mich das Spielangebot angesprochen hat.
Der Spielkatalog auf der Plattform geht in die Tausende: die ueblichen grossen Anbieter sind alle vertreten. Book of Dead und Starburst stehen ganz oben, die High-Volatility-Spiele machen mir am meisten Spass. Live Casino laeuft ueber Evolution: Crazy Time, Lightning Roulette und die Game Shows. Deutschsprachige Dealer gibt es in der Hauptzeit.
Der Willkommensbonus bei Play Fortuna liegt bei 100 Prozent bis 500 Euro, und Gratisdrehungen in Tagesraten. Umsatzbedingung ist 40x, im oberen Bereich aber machbar. Die laufenden Promotionen stehen bei [url=https://uro.pharmprosvet.ru/fortuna-casino-app-konto-verifizierung-leicht-erklart/]play fortuna[/url] vor der Einzahlung pruefen. Aktionen kommen laufend nach.
Mindesteinzahlung sind 10 Euro. Die ueblichen Zahlungsmethoden gehen problemlos, Krypto ist auch moeglich. Per Wallet ging es in unter 24 Stunden, Kartenauszahlungen brauchten zwei bis drei Tage. KYC war unkompliziert — Personalausweis hochgeladen und in Stunden bestaetigt.
Mobil spiele ich ueber den Browser, die Seite laedt schnell. Der Live-Chat ist auf Deutsch verfuegbar Wartezeit liegt bei drei bis fuenf Minuten. Es gilt eine Curacao-Lizenz, das sollte man bedenken. Auszahlungen wurden nie verweigert.
lvaaullet
September 28, 2026, at 7:33 am[url=https://copywalletvuitton.blogo.jp title=コピー 財布 ヴィトン]コピー 財布 ヴィトン[/url] [url=https://lvsalenew.livedoor.blog title=ヴィトン 財布 コピー]ヴィトン 財布 コピー[/url] 代金引換 送料無料
Yorkhug
September 28, 2026, at 7:42 amFelt the post had been written without using a single buzzword, and a look at auroraharbortradehouse continued that clean vocabulary, content free of jargon and trendy phrases reads better and ages better and this site has clearly committed to a vocabulary that will not feel dated in three years which is impressive editorially.
Alfredoupsed
September 28, 2026, at 7:50 amNow feeling the small relief of finding writing that does not condescend, and a stop at juniperharbortraders extended that respect for readers, content that treats its audience as capable adults rather than as people to be managed produces a different reading experience and this site has clearly chosen the respectful approach across all pieces.
Jamesbiats
September 28, 2026, at 7:54 amReally like that the writer trusts the reader to follow simple logic without restating every previous point, and a stop at trailharborvault kept that respect going, treating an audience as capable adults rather than as people who need constant hand holding makes a noticeable difference in the reading experience for me.
Ernestsuify
September 28, 2026, at 8:15 amWhat are gambling games bingo no deposit bonus automaty hry zdarma kajot Online casina na slovensku nike 50 spinov zadarmo casino bez rodneho cisla
wowrtZex
September 28, 2026, at 8:34 amA few minutes of comparison pays off for years.
The best time to level up was yesterday; the next best is now.
A vehicle history report is a must for any used car.
Consolidating high-interest debt can cut your monthly costs.
Knowledge is the only real edge in this market.
Start with one habit and build from there.
Review your coverage yearly as your life changes.
Employer matching is free money — never leave it on the table.
Understanding deductions is the key to a bigger refund.
Technology moves fast — the right tools keep you ahead.
Source:
[url=https://wjk777.skin]open bank account online
[/url]
healthy meal plans
MarcusWiB
September 28, 2026, at 8:58 amGoing to share this with a friend who has been asking the same questions for a while now, and a stop at rainmeadowcollectivemart added a few more pages I will pass along too, this is the kind of generous information that earns a small thank you from me right now and again later this week.
MatthewGyday
September 28, 2026, at 9:05 amТурниры Vavada стартуют еженедельно, а призовой фонд распределяется между лидерами таблицы по объёму сделанных ставок. Личный кабинет собирает всё в одном месте: касса, активные бонусы, история ставок, верификация и настройки безопасности. Проверить актуальный адрес можно тут: вавада казино онлайн – https://indodarts.com Такая мелкая деталь экономит несколько кликов в каждой сессии и заметно ускоряет привычные сценарии.
MatthewGyday
September 28, 2026, at 9:30 amПриложение Vavada для Android и iOS открывает кабинет по отпечатку пальца или Face ID одним касанием экрана. Отчёты независимых аудиторов iTech Labs и eCOGRA публикуются в открытом доступе с ежеквартальным обновлением показателей. Ознакомиться с разделом можно здесь: https://indodarts.com Такая мелкая деталь экономит несколько кликов в каждой сессии и заметно ускоряет привычные сценарии.
JettThula
September 28, 2026, at 9:38 amReally like the way the post resists reaching for cliches that would have made it feel generic, and a quick visit to junipercovegalleria kept that fresh feel going, original phrasing and unexpected metaphors are signs that the writer is actually thinking rather than just stitching together familiar phrases into the appearance of content.
Jaceclema
September 28, 2026, at 9:47 amSolid post, the structure is easy to follow and the language stays simple even when the topic gets a bit more involved, and a look at mapletrailartisanbazaar kept that same standard going, so I left feeling like the time spent here was actually worth something for once which is rare lately.
MatthewGyday
September 28, 2026, at 9:58 amПлощадка Вавада присутствует на рынке онлайн-развлечений с 2017 года и давно перестала быть нишевым проектом для узкого круга игроков. Доверенные устройства освобождают личный смартфон и ноутбук от повторного ввода 2FA-кода в течение месяца. Все детали доступны по адресу: [url=https://indodarts.com]vavada сайт[/url] Такая работа с сообществом формирует ощущение живого проекта, где обратная связь влияет на продуктовые решения.
SaulZep
September 28, 2026, at 10:01 amReading this in segments because the day was busy, and the post survived the fragmented attention well, and a stop at oliveorchardcollective held up similarly under interrupted reading, content that can withstand modern distracted reading patterns rather than requiring a perfect block of focused time is increasingly the kind I prefer.
Wilfredvag
September 28, 2026, at 10:06 amWill be back, that is the simplest way to say it, and a quick visit to meadowharborvault reinforced the decision, this site has earned a spot in my regular rotation alongside a few other reliable places I check when I want something genuinely informative without all the usual modern web noise getting in the way.
Rexlam
September 28, 2026, at 10:11 amMost attempts at writing on this topic feel like they are missing something and this post finally identified what was missing, and a look at jasperjunction extended that diagnostic clarity, content that names what is wrong with adjacent treatments while doing better itself is content with both critical and constructive value and this site has both.
RafaelTenry
September 28, 2026, at 10:21 amcaptain cook casino slovensko How many types of gambling games are there automaty zdarma sizzling Automaty s free spinmi hracie automaty free spin fortuna bonus casino
MatthewGyday
September 28, 2026, at 10:32 amLive-раздел Vavada с живыми крупье от Evolution, Ezugi и Playtech работает круглосуточно без технических пауз. Доверенные устройства освобождают личный смартфон и ноутбук от повторного ввода 2FA-кода в течение месяца. Переходите на площадку по ссылке: [url=https://indodarts.com]https://indodarts.com[/url] Такая полнота статистики ценна для игроков, которые ведут собственный учёт результатов на длинной дистанции.
RafaelTenry
September 28, 2026, at 10:34 am365 live casino mГґЕѕete hraЕҐ blackjack online na slovensku automaty zdarma sizzling hot turbo Hry o skutocnu vyhru bavime automati zdarma online poker herne slovensko
Olivervency
September 28, 2026, at 11:08 amPicked up something useful for a side project, and a look at calmmeadowvendorworks added another piece I will incorporate, content that connects to specific projects I am working on is content with practical utility and the practical utility of this site is showing up across multiple posts I have read in the last hour or so.
JulianMic
September 28, 2026, at 11:25 amEven on a quick first read the substance of the post comes through, and a look at trailstoneemporium reinforced that immediate quality, content that does not require a slow careful read to demonstrate value but rewards one anyway is content with real depth and this site has produced work of that demanding depth class.
RafaelTenry
September 28, 2026, at 11:27 amhry zdarma automaty sizzling najlepЕЎie mastercard kasГna wazamba casino vip Retro automaty bez poplatku automaty vГЅhra 2026 blackjack online software
BlakeSceks
September 28, 2026, at 11:39 amAppreciate that you did not pad this with fluff to hit a word count, the post says what it needs to say and stops, and a look at dawnharbormarketplace did the same, brevity here feels intentional not lazy which is a distinction many writers miss completely sometimes when they are working under deadlines.
SaulVom
September 28, 2026, at 12:07 pmFound the use of subheadings really helpful for scanning back through the post later, and a stop at harborstonevendorcollective kept that reader friendly approach going, navigation is something many blog writers ignore but small structural choices make a noticeable difference for someone returning to find a specific point again days or weeks later.
rever_wwKl
September 28, 2026, at 12:08 pmGioco su Slot Shopper da fine primavera e a questo punto posso farmi un’idea. Il catalogo e bella grossa, intorno ai 3.000 giochi se non ho contato male, con Pragmatic Play che fa il grosso del lavoro. Book of Dead lo trovi subito in evidenza, poi ci sono Big Time Gaming e Microgaming per chi cerca cose piu cattive.
Il live e gestita da Evolution, quindi non ci sono sorprese: croupier reali, qualche tavolo con dealer italiano, e ovviamente Crazy Time e compagnia che la sera si riempiono. Quello che non mi e piaciuto: su connessione mobile scarsa il video scatta, magari e la mia rete, non voglio dare colpe a caso.
Sul bonus: il benvenuto di Slot Shopper gira intorno al 100% fino a 300€ piu 200 spin gratuiti, distribuiti in piu tranche. Si parla di un rollover 35x solo sul bonus, non sul deposito, nella norma per il mercato italiano. Girano pure dei giri senza deposito se ti iscrivi alla newsletter, in ogni caso ti consiglio di controllare i termini attuali su [url=https://88aa-game.com/verifica-account-su-slotshopper-come-completare-la-procedura/]slotshopper[/url] prima di metterci soldi.
Si parte da 10 euro, signup rapido pero il KYC va fatto, non si scappa. Uso Skrill e i soldi sono rientrati in circa due giorni. Visa, Mastercard, i soliti e-wallet e anche crypto tipo Bitcoin, nessun problema di metodi. La prima volta pero ho aspettato piu del previsto per la verifica.
Da telefono non serve nessuna app, si comporta bene anche su schermo piccolo, nulla di spettacolare ma funzionale. Il supporto di Slot Shopper risponde in italiano in chat, di solito entro dieci minuti, per un problema su un free spin mi hanno risposto con calma e risolto. Operano con licenza Malta Gaming Authority, e sinceramente questo mi tranquillizza piu delle promo.
playf_oiMl
September 28, 2026, at 12:10 pmBin inzwischen seit dem Fruehling auf Play Fortuna aktiv, genug Zeit also um ein ehrliches Urteil abgeben. Habe es beim Vergleich von Anbietern gefunden, da die Slotauswahl vielversprechend aussah.
Die Spieleauswahl auf der Plattform ist groesser als erwartet: die ueblichen grossen Anbieter stellen den Grossteil. Book of Dead und Starburst findet man sofort, die Nolimit-Titel halten mich am laengsten. Live Casino laeuft ueber Evolution: Crazy Time, Lightning Roulette und die Game Shows. Deutschsprachige Dealer gibt es in der Hauptzeit.
Die Willkommenspromo bei Play Fortuna bietet eine Verdopplung bis 500 Euro, dazu Freispiele in Tagesraten. Der Rollover betraegt 40-fach, was hoch ist aber nicht ungewoehnlich. Aktuelle Codes und Angebote findet man auf [url=https://awo-ufr.org]play fortuna[/url] lohnt sich vorher zu lesen. Aktionen kommen laufend nach.
Man kann ab 10 Euro starten. Karten und E-Wallets funktionieren, Bitcoin wird ebenfalls angenommen. Per Wallet ging es in unter 24 Stunden, Auf die Karte waren es drei Werktage. Dokumente wurden schnell geprueft — Personalausweis hochgeladen und in Stunden bestaetigt.
Am Smartphone laeuft alles im Browser, funktioniert einwandfrei. Der Live-Chat ist auf Deutsch verfuegbar Antworten kommen zuegig. Reguliert wird ueber Curacao, also keine deutsche GGL-Lizenz. Mein Geld kam bisher immer an.
rever_ypKl
September 28, 2026, at 12:11 pmHab mich vor ein paar Monaten dort angemeldet, also kann ich schon was dazu sagen. Crypto Control hat eine echt volle Lobby — irgendwas um die 3000 Titel, hab ehrlich gesagt nicht nachgezahlt. Play’n GO und Yggdrasil sind reichlich dabei, Book of Dead ist mein Dauerbrenner.
Die Begru?ungsaktion war offen gesagt der Ausloser, warum ich es probiert hab. 100 Prozent auf die erste Einzahlung bis 500€ und dazu 200 Free Spins, die Freispiele kommen portionsweise. Kleiner Wermutstropfen: 35x Umsatz, schaffbar, aber nichts fur nebenbei. Es gab auch mal 20 Freispiele ohne Einzahlung, die Promos andern sich aber laufend.
Was gerade lauft, steht direkt auf [url=https://www.bimcc.net/solana-casino-review-und-uberblick-fur-deutsche-spieler/]solana casino[/url] , ich les die Bedingungen inzwischen immer vorher durch. Ab 20 Euro geht’s los, Registrierung dauerte bei mir keine drei Minuten.
Was das Abheben angeht kann ich nicht meckern: per Krypto ging’s in unter zwei Stunden, bei Skrill und Neteller hat’s einen Tag gedauert. Visa und Mastercard gehen naturlich auch, dauert aber gefuhlt ewig langer. Die Verifizierung bei Crypto Control war nervig — Dokumente hoch, warten, nochmal hoch.
Am Abend lande ich fast immer bei den Live-Tischen. Das lauft uber Evolution, Crazy Time ist bei mir Pflichtprogramm, und naturlich jede Menge Roulettevarianten. Deutschsprachige Croupiers gibt’s an einigen Tischen, nicht an allen, aber immerhin.
Auf dem Smartphone geht’s uber den Browser, keine native App, ist mir aber wumpe. Beim Support von Crypto Control bekommt man auf Deutsch Antwort, meistens innerhalb von funf Minuten, auch wenn man teils Textbausteine bekommt. Die Lizenz kommt aus Curacao, also nicht nach deutschem Glucksspielstaatsvertrag reguliert, das sollte einem klar sein.
rever_lkKl
September 28, 2026, at 12:14 pmSpiele dort seit gut vier Monaten unterwegs, drauf gesto?en weil ein Kumpel es empfohlen hat. Was mich bei Play Fortuna gehalten hat, ist ehrlich gesagt das Portfolio. Grob 4000 Spiele stehen da rum, Play’n GO, Yggdrasil und Pragmatic dominieren klar. Meine Dauerbaustelle ist Gates of Olympus, Sweet Bonanza nebenbei wenn ich Abwechslung brauche.
Beim Live-Zeug ist es zum gro?ten Teil Evolution, und das ist mir wichtig. Deutschsprachige Tische gibt es zu den ublichen Zeiten, Crazy Time, Monopoly Live und Blackjack nehme ich fur die Abwechslung. Muss man sagen: die Streams ruckeln manchmal, liegt aber wohl an meiner Leitung.
Was den Bonus angeht: 100% bis 500 Euro plus 100 Freispiele standen zur Auswahl. 40x Wagering — nicht super, aber Standard. Manchmal findest du Gratis-Spins ohne Deposit, die sind schnell weg. Die aktuellen Konditionen siehst du am besten auf [url=https://lumpemedia.com/fortuna-casino-app-der-komplette-guide-fur-deutsche-spieler/]play fortuna casino[/url] nach, bevor du einzahlst.
Minimum sind 10€, ich nutze Visa und ab und zu Skrill. Kreditkarte, E-Wallets, teils Krypto kannst du nutzen. Meine Auszahlungen bei Play Fortuna waren nach ein bis zwei Tagen da — beim ersten Mal dauerte es langer, KYC halt, danach kein Thema mehr.
Der Account war in zwei Minuten durch, Mail, Passwort, Wahrung wahlen. Keine App, aber die mobile Seite ist ordentlich was mir aber genugt. Der Support antwortet im Chat nach wenigen Minuten, auf Deutsch — teilweise etwas holprig. Was mich wirklich stort: die Lizenz von Play Fortuna kommt aus Curacao, kein deutsches Siegel — wer hier aus Deutschland spielt sollte das wissen. Ich nehme dafur die fehlende 5-Sekunden-Regel in Kauf, aber das ist Geschmackssache.
MiltonDug
September 28, 2026, at 12:26 pmGlad to have another reliable bookmark for this topic, and a look at tealstoneoutpost suggested several more pages I will be marking too, building a personal library of trustworthy resources is one of the actual rewards of careful browsing and this site is earning a place on my permanent shortlist for the topic.
Keithjoype
September 28, 2026, at 12:38 pmNow adding the writer to a small mental list of voices I want to follow, and a look at sunmeadowvendorworks reinforced that follow intention, the few writers whose work I actively track are writers who have demonstrated sustained quality and this writer has clearly demonstrated that sustained quality across the pieces I have sampled here today.
playf_mwMl
September 28, 2026, at 12:57 pmIch bin mittlerweile seit etwa fuenf Monaten bei Play Fortuna unterwegs, daher laesst sich mittlerweile ein ehrliches Urteil abgeben. Habe es beim Vergleich von Anbietern gefunden, da die Slotauswahl vielversprechend aussah.
Das Angebot an Spielen auf der Plattform ist wirklich umfangreich: die ueblichen grossen Anbieter liefern die Titel. Die bekannten Hits stehen ganz oben, die High-Volatility-Spiele sind fuer mich das Highlight. Live Casino laeuft ueber Evolution: alle bekannten Tischspiele plus die Showformate. Dealer sprechen Deutsch zu bestimmten Zeiten.
Die Willkommenspromo bei Play Fortuna bietet eine Verdopplung bis 500 Euro, und Gratisdrehungen in Tagesraten. Wagering liegt bei 40x, was hoch ist aber nicht ungewoehnlich. Aktuelle Codes und Angebote stehen bei [url=https://childrensacademykamachha.com/fortuna-casino-app-zahlungs-und-auszahlungsmethoden-im-uberblick/]fortuna casino app[/url] lohnt sich vorher zu lesen. Reload-Boni gibt es woechentlich.
Die Untergrenze liegt bei zehn Euro. Die ueblichen Zahlungsmethoden gehen problemlos, Krypto ist auch moeglich. Skrill-Auszahlungen waren am naechsten Tag da, Auf die Karte waren es drei Werktage. Dokumente wurden schnell geprueft — Ausweis und Adressnachweis, fertig am selben Tag.
Am Smartphone laeuft alles im Browser, Performance ist gut. Kundenservice spricht Deutsch Wartezeit liegt bei drei bis fuenf Minuten. Es gilt eine Curacao-Lizenz, das sollte man bedenken. Unterm Strich stimmt die Zahlungsmoral.
rever_jjKl
September 28, 2026, at 1:01 pmBazzico su Slot Shopper dallo scorso inverno e dopo un po’ di giri posso farmi un’idea. Di roba ce n’e davvero ampia, intorno ai 3.000 giochi piu o meno, con NetEnt che fa il grosso del lavoro. Sweet Bonanza resta il mio solito punto di partenza, e poi ci sono Yggdrasil e Betsoft per chi vuole volatilita alta.
La parte live gira su Evolution, quindi sai gia cosa aspettarti: dealer in carne e ossa, qualche tavolo con dealer italiano, e ovviamente Crazy Time e compagnia sempre pieni di sera. Quello che non mi e piaciuto: su connessione mobile scarsa il video scatta, pero forse e piu un problema della mia linea.
Riguardo al benvenuto: il benvenuto di Slot Shopper gira intorno al 150% fino a 200€ piu 100 spin gratuiti, spalmati su qualche giorno. Il requisito di puntata sta sul 40x solo sul bonus, non sul deposito, che non e regalato ma e nella media. Danno anche 20 free spin senza deposito se ti iscrivi alla newsletter, e comunque le condizioni esatte le trovi su [url=https://honchomovers.org/slotshopper-guida-alla-sicurezza-per-i-casino-online/]slotshopper[/url] prima di depositare.
Si parte da 10 euro, iscrizione in pochi minuti con documento da caricare per il KYC. Io deposito con Neteller e i soldi sono rientrati in un giorno e mezzo. Ci sono carte, e-wallet, bonifico e anche cripto, c’e abbondanza. La prima volta pero ho aspettato piu del previsto colpa della verifica iniziale.
Su smartphone non serve nessuna app, il sito si adatta bene, semplice e senza intoppi. La chat di Slot Shopper e in italiano via live chat, tempi sui 5-10 minuti, una volta mi hanno risolto un giro non accreditato senza fare storie. La licenza e MGA, e sinceramente questo mi tranquillizza piu delle promo.
rever_odKl
September 28, 2026, at 1:01 pmSpiele dort mittlerweile seit etwa einem halben Jahr, also rede ich nicht komplett ins Blaue. Crypto Control hat eine echt volle Lobby — irgendwas um die 3000 Titel, hab ehrlich gesagt nicht nachgezahlt. NetEnt und Betsoft sind stark vertreten, Gates of Olympus und Sweet Bonanza laufen bei mir am meisten.
Der Willkommensbonus war ehrlich gesagt der Grund, warum ich es probiert hab. 100% bis 500 Euro plus 200 Freispiele, aufgeteilt uber mehrere Tage. Was man wissen sollte: 35x Umsatz, fair genug, trotzdem nicht geschenkt. Es gab auch mal 20 Freispiele ohne Einzahlung, aber die Aktionen wechseln standig.
Die jeweils gultigen Angebote stehen bei [url=https://sevende.fi/solana-casino-konto-verifizierung-schritt-fur-schritt-guide-fur-deutsche-spieler/]solana casino[/url] — lohnt sich vor der Anmeldung kurz reinzulesen. Eingezahlt werden mussen mindestens 20€, das Anmelden war in zwei Minuten durch.
Was das Abheben angeht war ich positiv uberrascht: uber BTC waren es keine 90 Minuten, bei Skrill und Neteller hat’s einen Tag gedauert. Visa und Mastercard gehen naturlich auch, dauert aber gefuhlt ewig langer. Das KYC bei Crypto Control hat mich am meisten genervt — Perso plus Stromrechnung, das ubliche Theater.
Live-Dealer ist bei mir Standardprogramm geworden. Das lauft uber Evolution, an Crazy Time komme ich selten vorbei, plus reichlich Roulette und Blackjack. Fur uns aus Deutschland sind ein paar deutschsprachige Tische dabei, nicht flachendeckend, trotzdem nett.
Mobil nutze ich einfach den Browser, App fehlt, stort mich ehrlich gesagt kaum. Beim Support von Crypto Control bekommt man auf Deutsch Antwort, meistens innerhalb von funf Minuten, auch wenn man teils Textbausteine bekommt. Lizenziert ist der Laden auf Curacao, also keine deutsche GGL-Lizenz, das muss jeder fur sich bewerten.
rever_fjKl
September 28, 2026, at 1:05 pmBin da jetzt gut vier Monaten unterwegs, reingestolpert uber einen Tipp aus einem anderen Thread. Hangen geblieben bin ich bei Play Fortuna, ist vor allem die Lobby. Grob 4000 Spiele findest du, Pragmatic Play und Play’n GO sind am starksten vertreten. Meine Dauerbaustelle ist Gates of Olympus, Big Bass Bonanza zwischendurch zur Auflockerung.
Der Livebereich ist komplett Evolution, womit ich gut leben kann. Deutschsprachige Tische sind vorhanden abends zuverlassig, Crazy Time, Monopoly Live und Blackjack sind mein Ding. Muss man sagen: die Streams ruckeln manchmal, aber das lag vermutlich an mir.
Zum Bonus: 100 Prozent auf die erste Einzahlung plus Freispiele standen zur Auswahl. Der Umsatz liegt bei 40x — nicht super, aber Standard. Manchmal findest du No-Deposit-Spins uber den Newsletter, da muss man dran sein. Welche Codes gerade gultig sind schaust du besser direkt bei [url=https://notes.wheelofconsentbook.com/play-fortuna-in-deutschland-kompletter-guide-zu-casino-bonus-sportwetten/]play fortuna[/url] nach — lohnt sich vor der Anmeldung.
Minimum sind 10€, ich nehme meistens Skrill. Karte, Skrill, Neteller, Crypto sind alle da. Meine Auszahlungen bei Play Fortuna waren nach ein bis zwei Tagen da — nur die allererste hing wegen der Verifizierung, Dokumente prufen lassen und fertig.
Das Anmelden dauert keine funf Minuten, Mail, Passwort, Wahrung wahlen. Eine App gibt es nicht, mobil geht uber den Browser und lauft auf dem Android sauber. Der Livechat reagiert nach wenigen Minuten, auf Deutsch, aber merklich ubersetzt. Was mich argert: Play Fortuna lauft unter Curacao-Lizenz, also keine Regulierung nach deutschem Glucksspielstaatsvertrag — das muss jeder fur sich entscheiden. Mir waren die hoheren Limits und die gro?ere Auswahl das wert, jedem das Seine.
rever_nbKl
September 28, 2026, at 1:11 pmI’ve been messing about at Trino for a good few months, usually late at night, so take this as a regular player’s take. Joined because of a thread on another forum, and the whole thing took maybe three minutes — just email and a password, although they did want docs later, standard stuff with a UKGC licence.
Game selection is genuinely big — somewhere north of 3,000 titles by my rough count. Pragmatic is everywhere, so expect the usual — Gates of Olympus sitting right at the top. Play’n GO supplies Book of Dead and Reactoonz, plus a decent chunk of NetEnt and Microgaming in there too. I tend to live in high-volatility slots if I’ve got a bit of budget to burn.
The welcome offer at Trino Casino is 100% up to ?500 plus 200 free spins, spread over your first two top-ups. Playthrough is 35x on the bonus, and that’s about average, not amazing. Min deposit sits at ?20. There’s a small no deposit thing if you sign up to emails — it comes and goes, so it’s worth a check the latest offers over on [url=https://seteconsultoria.com.br/2026/09/trino-casino-in-the-uk-complete-guide-to-bonuses-payments-mobile-security/]casino trino[/url] before you commit.
Cashouts are honestly the part that matters, and on this front Trino Casino hasn’t messed me around. Cashed out ?280 via Skrill last week and it landed in about six hours. Cards are there, e-wallets are quicker, plus there’s Bitcoin and a couple of altcoins for anyone who bothers. What did wind me up: bank transfers took four working days the first time.
Support runs round the clock and the people there aren’t just copy-pasting scripts, though getting a human took a while on a Saturday night. Live dealer runs on Evolution, so real croupiers, proper blackjack and roulette tables, plus Crazy Time for the game-show crowd — I don’t, much. No app, only the mobile site, and it works fine on my Pixel though sometimes logs me out mid-spin.
playf_jsMl
September 28, 2026, at 1:32 pmSpiele jetzt seit etwa fuenf Monaten auf Play Fortuna aktiv, genug Zeit also um eine realistische Einschaetzung zu geben. Habe es beim Vergleich von Anbietern gefunden, hauptsaechlich wegen der Spielauswahl.
Die Spieleauswahl hier ist groesser als erwartet: Pragmatic, NetEnt und Nolimit City sind alle vertreten. Gates of Olympus und Sweet Bonanza stehen ganz oben, aber die Megaways-Slots sind fuer mich das Highlight. Evolution betreibt die Live-Tische: Roulette, Blackjack und Baccarat mit deutschen Dealern. Dealer sprechen Deutsch zu bestimmten Zeiten.
Das Startpaket bei Play Fortuna bietet eine Verdopplung bis 500 Euro, und Gratisdrehungen die ueber mehrere Tage verteilt werden. Wagering liegt bei 40x, was hoch ist aber nicht ungewoehnlich. Aktuelle Codes und Angebote sind nachzulesen auf [url=https://www.staycactus.lk/fortuna-casino-app-kontoverifizierung-einfach-erklart/]play fortuna casino[/url] lohnt sich vorher zu lesen. Aktionen kommen laufend nach.
Die Untergrenze liegt bei zehn Euro. Visa, Mastercard und Skrill werden akzeptiert, Krypto ist auch moeglich. Skrill-Auszahlungen waren am naechsten Tag da, Bankueberweisungen dauerten laenger. KYC war unkompliziert — ging beim ersten Versuch durch.
Am Smartphone laeuft alles im Browser, die Seite laedt schnell. Kundenservice spricht Deutsch Antworten kommen zuegig. Es gilt eine Curacao-Lizenz, also keine deutsche GGL-Lizenz. Auszahlungen wurden nie verweigert.
RafaelTenry
September 28, 2026, at 1:33 pmbig circus demo best bally wulff slot sites automaty online tipsport Free spiny dnes online poker slovensko poker automaty zdarma
rever_pnKl
September 28, 2026, at 1:38 pmGioco su Slot Shopper dallo scorso inverno e a questo punto posso parlarne senza sparare fesserie. Il catalogo e piuttosto vasta, circa 2.000 titoli a occhio, con Play’n GO che fa il grosso del lavoro. Gates of Olympus resta il mio solito punto di partenza, poi ci sono Big Time Gaming e Microgaming per chi cerca cose piu cattive.
Il settore live e tutta Evolution, per cui non ci sono sorprese: dealer in carne e ossa, qualche tavolo con dealer italiano, e ovviamente Crazy Time e compagnia che la sera si riempiono. Quello che non mi e piaciuto: su connessione mobile scarsa il video scatta, magari e la mia rete, non voglio dare colpe a caso.
Sul bonus: il benvenuto di Slot Shopper gira intorno al 150% fino a 200€ e ci mette 100 spin gratuiti, spalmati su qualche giorno. Il requisito di puntata sta sul 35x solo sul bonus, non sul deposito, nella norma per il mercato italiano. Ci sono anche 20 free spin senza deposito in certi periodi, e comunque le condizioni esatte le trovi su [url=https://dongphucdieplong.com.vn/slotshopper-guida-ai-metodi-di-pagamento-rapidi-e-sicuri/]slotshopper[/url] prima di metterci soldi.
Il minimo per iniziare 10 euro, iscrizione in pochi minuti pero il KYC va fatto, non si scappa. Io deposito con la carta Visa con accredito in un giorno e mezzo. Carte, Skrill, Neteller, bonifico e qualche opzione in Bitcoin, c’e abbondanza. Il primo prelievo e stato piu lento perche stavano verificando i documenti.
Da mobile non serve nessuna app, il sito si adatta bene, semplice e senza intoppi. Slot Shopper ha l’assistenza in italiano in chat, di solito entro dieci minuti, una volta mi hanno risolto un giro non accreditato senza fare storie. Sono regolati con licenza MGA, cosa che per me conta piu del bonus.
rever_azKl
September 28, 2026, at 1:38 pmSpiele dort mittlerweile seit etwa einem halben Jahr, deswegen mal mein ehrlicher Senf dazu. Crypto Control hat eine echt volle Lobby — grob 2500 bis 3000 Spiele, genaue Zahl wei? ich nicht. NetEnt und Betsoft sind stark vertreten, Book of Dead ist mein Dauerbrenner.
Der Willkommensbonus war so ziemlich der Hauptgrund, warum ich uberhaupt angefangen hab. 100% bis 500 Euro plus 200 Freispiele, die Spins tropfeln uber ein paar Tage rein. Was man wissen sollte: man muss 35-fach umsetzen, das ist branchenublich, aber kein Selbstlaufer. Einen kleinen No-Deposit-Teil mit 20 Spins gab’s auch, das rotiert allerdings dauernd.
Die jeweils gultigen Angebote stehen bei [url=https://edisonjulianoti.com.br/solana-casino-schritt-fur-schritt-registrierung-und-verifizierung-fur-deutsche-spieler/]solana casino[/url] , kurz die AGB uberfliegen schadet nie. Die Mindesteinzahlung liegt bei 20 Euro, Registrierung dauerte bei mir keine drei Minuten.
Bei den Auszahlungen war ich positiv uberrascht: uber BTC waren es keine 90 Minuten, bei Skrill und Neteller hat’s einen Tag gedauert. Visa und Mastercard gehen naturlich auch, da wurde ich aber mit zwei bis drei Tagen rechnen. Bei Crypto Control musste ich fur die Verifizierung dreimal nachreichen — Ausweis, Selfie, Adressnachweis, das volle Programm.
Am Abend lande ich fast immer bei den Live-Tischen. Die Tische kommen von Evolution, Crazy Time zieht mich immer wieder rein, dazu die ublichen Blackjack- und Roulette-Tische. Fur uns aus Deutschland sind ein paar deutschsprachige Tische dabei, nicht an allen, aber immerhin.
Auf dem Smartphone geht’s uber den Browser, eine eigene App gibt’s nicht, vermisse ich aber nicht. Der Support von Crypto Control antwortet im Chat auf Deutsch, Wartezeit war bei mir selten uber zehn Minuten, wobei die Standardantworten manchmal an der Frage vorbeigehen. Lizenziert ist der Laden auf Curacao, also keine deutsche GGL-Lizenz, das muss jeder fur sich bewerten.
rever_gsKl
September 28, 2026, at 1:42 pmBin da jetzt gut vier Monaten aktiv, drauf gesto?en uber einen Tipp aus einem anderen Thread. Der Grund warum ich bei Play Fortuna geblieben bin, ist vor allem die Lobby. Grob 4000 Spiele stehen da rum, Play’n GO, Yggdrasil und Pragmatic machen den Gro?teil aus. Gates of Olympus lauft bei mir am haufigsten, Sweet Bonanza ab und zu wenn die Laune stimmt.
Der Livebereich ist komplett Evolution, was fur mich Pflicht ist. Deutsche Croupiers gibt es zu den ublichen Zeiten, Crazy Time plus die ublichen Gameshows sind mein Ding. Ehrlich: bei schlechtem WLAN bricht der Stream weg, kann aber auch mein Router sein.
Was den Bonus angeht: 100 Prozent auf die erste Einzahlung plus Freispiele standen zur Auswahl. 40x Wagering — schon happig, aber branchenublich. Manchmal findest du No-Deposit-Spins uber den Newsletter, da muss man dran sein. Welche Codes gerade gultig sind siehst du am besten auf [url=https://iisrar.com/?p=3513]play fortuna[/url] an, das andert sich ofter.
Minimum sind 10€, bei mir lauft es uber Neteller. Kreditkarte, E-Wallets, teils Krypto stehen zur Verfugung. Meine Auszahlungen bei Play Fortuna waren nach ein bis zwei Tagen da — nur die allererste hing wegen der Verifizierung, Dokumente prufen lassen und fertig.
Der Account ging fix, E-Mail und Passwort, das war’s. Eine App gibt es nicht, mobil geht uber den Browser und lauft auf dem Android sauber. Der Support antwortet im Chat nach wenigen Minuten, deutsch, wirkt aber teils nach Textbaustein. Was mich argert: die Lizenz von Play Fortuna kommt aus Curacao, keine deutsche GGL-Genehmigung — damit muss man klarkommen. Fur mich uberwiegen die Limits ohne 1-Euro-Deckel, andere sehen das anders.
Jorgemaino
September 28, 2026, at 1:44 pmIf I had to summarise the editorial sensibility of this site in a few words it would be careful and human, and a look at autumnridgegoodsstore extended that summary feeling, capturing the essence of a sites approach in brief is hard but this site has a clear enough identity that the summary comes naturally enough.
RafaelTenry
September 28, 2026, at 1:46 pmhry zdarma automaty kartove blackjack stratГ©gia pre zaДЌiatoДЌnГkov casino bonusy za vklad Free spiny fortuna dnes kajot online casino sk casino online fortuna
AlecVak
September 28, 2026, at 1:55 pmWorth marking this site as one to come back to deliberately rather than by accident, and a stop at dumbbelldrift reinforced that intention, the difference between sites I find again by chance and sites I return to on purpose is meaningful and this one has clearly moved into the deliberate return category for me.
rever_koKl
September 28, 2026, at 2:09 pmI’ve been playing at Trino Casino since roughly the spring, mostly on the commute home, so read this as a regular player’s take. Signed up after a thread on another forum, and the whole thing took under five minutes — just email and a password, although you do need verification before the first payout, which I expected.
The lobby is deeper than I thought — around 3,500 games by my rough count. Pragmatic is everywhere, so you get the obvious ones — Gates of Olympus and Sweet Bonanza pinned to the popular tab. Play’n Go brings Book of Dead, plus a decent amount of NetEnt and Microgaming in there too. My go-to is Big Time Gaming stuff if I’ve got the bankroll for it.
The welcome offer at Trino Casino is a 100% match to ?300 with 150 spins, split across a few deposits. Playthrough is 35x on the bonus, which is fair enough by 2026 standards. Min deposit is ?10. They also run a no-deposit spins offer if you sign up to emails — it’s not always live, so you can see the latest offers over on [url=https://funcasolinternacional.org/casino-trino-account-verification-guide-for-uk-players/]trino casino[/url] rather than trusting my numbers.
Cashouts are honestly the part I care about most, and here Trino has been fine. Cashed out ?280 via Skrill a fortnight ago and it cleared in about six hours. Debit cards work, e-wallets are quicker, plus there’s Bitcoin and a couple of altcoins for anyone who bothers. My gripe: card withdrawals were painfully slow the first time.
Support is 24/7 and the people there answered properly, but the first reply can take a while on a Saturday night. The live section is all Evolution, so real croupiers, proper table limits for UK players, plus Crazy Time if you like the game show stuff — I don’t, much. There’s no dedicated app, only a browser version, and it is fine on iPhone though sometimes logs me out mid-spin.
CarmeloBuh
September 28, 2026, at 2:18 pmComfortable reading experience throughout, no jarring tone shifts and no awkward formatting, and a look at plumstoneoutlet kept that smooth feel going, the kind of editorial polish that goes unnoticed when present but glaring when absent is something this site has clearly invested in across the broader content as well which deserves recognition.
RafaelTenry
September 28, 2026, at 2:40 pmkajot hry zdarma automaty casino live dealer vГЅhernГ© automaty zadarmo Automaty na hranie online vyherne hracie automaty zdarma Are “no-deposit” free spins really free
rever_wgKl
September 28, 2026, at 2:42 pmBeen playing at Trino for about four months now, mostly on the commute home, so take this for what it’s worth. Joined because of a random Twitter post, and the whole thing took about two minutes — just email and a password, though they did want verification before the first payout, which I expected.
Game selection is genuinely big — roughly 3,000+ slots and tables by my rough count. Pragmatic Play is everywhere, so expect the obvious ones — Gates of Olympus and Sweet Bonanza sitting right at the top. Play’n GO brings Book of Dead and Reactoonz, plus a decent amount of NetEnt, Yggdrasil and Big Time Gaming knocking about. I tend to live in the Megaways section when I’ve got the bankroll for it.
The bonus on Trino Casino was 100% up to ?500 plus 200 free spins, spread over your first two top-ups. Playthrough is 35x, and that’s neither great nor awful. Minimum is ?10. There’s a small no deposit thing sometimes — it comes and goes, so you can see the live promos at [url=https://www.xxl-kuechenstudio.de/2026/09/23/trino-casino-what-uk-players-need-to-know-about-bonuses-payments-mobile-app-security/]trino casino[/url] rather than trusting my numbers.
Withdrawals are the bit that matters, and on this front Trino Casino has behaved. Cashed out a few hundred to Neteller a fortnight ago and it cleared next morning. Cards are there, e-wallets are quicker, plus there’s crypto for anyone who bothers. What did wind me up: bank transfers dragged on for nearly a week initially.
Live chat runs round the clock and the agents aren’t just copy-pasting scripts, but the first reply took a while during peak hours. The live section is all Evolution, so actual dealers, proper table limits for UK players, and Crazy Time for the game-show crowd — I don’t, much. No app, just a browser version, and it works fine on my Pixel but occasionally logs me out mid-spin.
Zionboymn
September 28, 2026, at 2:53 pmHalfway through I knew I would finish the post, and a stop at forestcovegalleria also held me through to the end, content that signals its quality early and then sustains it is content with real internal consistency and this site has clearly figured out how to maintain quality from opening sentence through to closing thought.
Danielfrire
September 28, 2026, at 3:14 pmИнтересует сертификация продукции? [url=https://www.certif-test.ru]https://www.certif-test.ru[/url] Сертификация продукции — важный этап для законного производства, импорта и реализации товаров. Поможем определить необходимые разрешительные документы, оформить сертификат или декларацию соответствия, организовать испытания продукции и пройти процедуру с учетом действующих требований. Сопровождаем процесс от консультации до получения готовых документов.
Mitchellbit
September 28, 2026, at 3:35 pmGenerally I am cautious about recommending sites on first encounter but this one warrants the exception, and a look at linenstonegalleria reinforced the exception making, the rare site that justifies breaking my normal cautious approach is the rare site worth flagging early and this one has prompted exactly that early flagging response from me.
YaleCusly
September 28, 2026, at 3:41 pmJust want to flag that this was useful and not bury the appreciation in caveats, and a look at trailmeadowtradehouse earned the same direct praise, recognising good work without hedging it with criticism is something I try to practice because over qualified compliments tend to read as backhanded and miss the point sometimes.
LarryMug
September 28, 2026, at 4:01 pmchido77
CordellEscon
September 28, 2026, at 4:03 pmPicked a friend mentally as the audience for this and decided to send the link, and a look at jasperstonegalleria confirmed the send was the right choice, choosing whom to share content with is a small act of curation that I take more seriously than the public sharing most platforms encourage these days online.
Omarreelm
September 28, 2026, at 4:14 pmQuality writing that respects the reader’s intelligence without overloading them, and a quick look at indigovendor reflected that approach, a balanced thoughtful site that earns trust by being consistent rather than by shouting about how trustworthy it is which is the usual approach online sadly across most content categories.
DevinArbib
September 28, 2026, at 4:24 pmNow adding the homepage to my regular check rotation rather than waiting for individual links to find me, and a stop at apricottrailartisanmarket confirmed the rotation upgrade, the move from passive discovery to active checking is a vote of confidence in a sites ongoing quality and this site has earned that active engagement clearly.
RafaelTenry
September 28, 2026, at 4:46 pmspiny za registraciu 2026 free spiny zdarma jen za registraci kajot casino 5 eur bonus Zarobit peniaze v online hrach hazardne hry online automaty zdarma sk
Larrymyday
September 28, 2026, at 5:30 pmmasterbets365.co
RafaelTenry
September 28, 2026, at 5:53 pme gaming bonus play blackjack online no money ruleta ЕЎЕҐastia online hra Free spiny fortuna dnes best live casino sk automaty zdarma bez obmedzenГ
JeanBaF
September 28, 2026, at 6:14 pmSkipped the social share buttons but might come back to actually use one later, and a stop at honeycovecommerceatelier extended that share urge, content that triggers genuine sharing impulses rather than performative ones is content that has actually moved me and not many posts in a typical week do that for me actually.
Bestchange
September 28, 2026, at 6:37 pm[url=https://bestchange.com.co/]Compare crypto exchange rates live[/url]
Tracealits
September 28, 2026, at 6:47 pmNow thinking about how to apply some of this to a project I have been planning, and a look at pinemeadowtradehouse added more material for the planning, content that connects to my actual creative work rather than just being interesting in the abstract is the kind that earns priority placement in my reading rotation consistently going forward.
BartholomewAdvaf
September 28, 2026, at 6:56 pmGenuine reaction is that this site clicked with how I like to read, and a look at maplecresttrading kept that comfortable fit going, sometimes you find a place online whose editorial decisions just align with your preferences and when that happens it is worth recognising and supporting through repeat engagement consistently going forward.
Lesterplave
September 28, 2026, at 8:11 pmClosed the post with a small satisfied sigh, and a stop at embergladecraftmarket produced the same gentle exhale, content that ends well is content that respects the rhythm of reading and the writers here have clearly thought about how their pieces close rather than just trailing off when they run out of things to say.
RafaelTenry
September 28, 2026, at 8:12 pmruleta online za peniaze fresh casino bonus nine casino recenzie Bonus 10 eur hri automati zdarma hracie automaty 5-vГЎlcovГ© zdarma
Jakewiz
September 28, 2026, at 8:14 pmThank you for keeping the writing honest and the points easy to verify against your own experience, and a stop at suntrailartisanhouse reflected the same approach, no exaggeration just steady useful content that I can take with me into my own work without second guessing every sentence I happen to read here.
EzekielDEF
September 28, 2026, at 8:37 pmEven on a quick first read the substance of the post comes through, and a look at mossstoneoutpost reinforced that immediate quality, content that does not require a slow careful read to demonstrate value but rewards one anyway is content with real depth and this site has produced work of that demanding depth class.
ReedKix
September 28, 2026, at 8:51 pmFelt the writer respected the topic without being precious about it, and a look at juniperharbortrading continued that respectful but unfussy treatment, finding the right register for serious topics is hard and this site has clearly figured out how to take the topic seriously while still being readable for casual visitors regularly.
RafaelTenry
September 28, 2026, at 9:05 pmautomati hri hraj zdarma paysafecard casino sk hry o peniaze online Hry v casine za peniaze hrГЎt automaty zdarma bez registrace 81 stГЎhnout automaty zdarma
Blakeraids
September 28, 2026, at 9:10 pmReading this slowly to give it the attention it deserved, and a stop at mooncoveartisanhouse earned the same slow read, choosing to read slowly is a small act of respect for content quality and very few sites earn that respect from me but this one did so without any explicit ask which is the cleanest way.
ArthuremboN
September 28, 2026, at 9:28 pmReading this fit naturally into my afternoon walk because I was reading on my phone, and a stop at solarorchardoutpost continued well in that walking format, content that survives mobile reading without becoming awkward is content with format flexibility and this site has clearly thought about how it reads across different devices today.
Luisetell
September 28, 2026, at 9:32 pmGoing to share this with a friend who has been asking the same questions for a while now, and a stop at sagestoneoutpost added a few more pages I will pass along too, this is the kind of generous information that earns a small thank you from me right now and again later this week.
Rossdes
September 28, 2026, at 10:31 pmAppreciate the thoughtful approach, the writer clearly took time to make this readable for someone who is not already an expert, and a look at lavenderharborvault kept that going nicely, easy on the eyes and easy on the brain which is always a winning combination when reading on a busy day.
RafaelTenry
September 28, 2026, at 11:11 pmonline casino slot spigo online slots automaty zdarma 5 valcove Kasina s vkladom od 20 eur american blackjack online free bonus bez vkladu za registraciu
AshtonBioni
September 28, 2026, at 11:20 pmFound a small mental shift after reading this, the framing here is just a bit different from the standard takes online, and a look at baystonegalleria extended that fresh perspective across more material, the rare site whose voice actually changes how you think about something rather than just confirming existing beliefs.
RafaelTenry
September 28, 2026, at 11:24 pmcasino hry hracie automaty kasino online automaty slovenskГ© online kasГna Automaty online hrat hracie automaty 5 valcove zdarma live casino online blackjack
Tristanabnom
September 28, 2026, at 11:26 pmA piece that prompted a small mental rearrangement of how I order related ideas, and a look at coastharborvault extended that rearranging effect, content that affects the structure of my thinking rather than just adding to it is content with the deepest kind of impact and this site is reaching that depth for me today.
Ashtonedify
September 28, 2026, at 11:49 pmGlad the writer kept this short rather than padding it out, the points stand on their own without needing extra context, and a look at crowncoveartisanexchange kept the same approach going, brevity is a sign of confidence in the substance and the team here clearly trusts their content to land without filler.
Rodolfotof
September 28, 2026, at 11:52 pmProbably one of the more reliable sources I have found for this kind of careful coverage, and a look at moneymagnolia reinforced the reliability, the small group of sources I would describe as reliable for a given topic is curated carefully and this site has earned a place in that small group through consistent performance.
RafaelTenry
September 29, 2026, at 12:18 ammonaco bet free spin novГ© casino 2026 5 free spin za registraci Slovenske online casina 4 club casino casino online bonus sk
Josephwal
September 29, 2026, at 12:39 amIf I were grading sites on this topic this one would receive high marks, and a stop at oliveharbortraders continued earning those high marks, the informal grading I do mentally for content sources is something I take seriously even though it is informal and this site has been receiving consistent high marks across multiple sessions today.
NashInwam
September 29, 2026, at 12:39 amLiked the natural conversational tone throughout, never stiff and never overly casual either, and a stop at gladecoveartisanhouse kept that comfortable middle ground going, finding a tone that respects the reader without becoming distant or overly familiar is harder than it sounds and this site nails that balance consistently across many different pieces.
Amariwinly
September 29, 2026, at 12:55 amReading this felt productive in a way most internet reading does not, and a look at stoneharborvault continued that productive feeling, sometimes the open web feels like a waste of time but sites like this remind me why I still bother to look around rather than retreating to old reliable sources for everything I need.
WinstonTah
September 29, 2026, at 1:07 amA piece that did not require external context to follow, and a look at juniperstoneoutpost maintained the same self contained quality, content that stands alone without forcing readers to chase prerequisites is more accessible and this site has clearly thought about how each piece can serve a fresh visitor rather than only existing members.
DennisDof
September 29, 2026, at 1:12 amNow thinking I want more sites built on this kind of editorial foundation, and a stop at oakstoneemporium extended that wish into a broader hope, sites built on substance and care rather than on metrics and growth are the kind of sites I want to see more of and this one is a small example worth supporting.
inyono7777
September 29, 2026, at 1:26 amReally impressed with the bonus offers here. It feels like they actually care about the players. I am sticking with inyono7777 from now on.
RafaelTenry
September 29, 2026, at 2:24 amjackpot giant slot automaty zdarma kajot 81 automaty kojot zdarma Retro automaty zadarmo stiahnuЕҐ automaty zdarma casino online legal
WarnerToubs
September 29, 2026, at 2:25 amhttps://spinay1.com/
GingerAcime
September 29, 2026, at 2:28 amHonest reaction is that this is the kind of writing I would defend in a conversation about good blog content, and a look at driftridgeartisanhouse reinforced that, the rare site whose work I would actively recommend rather than just tolerate is the kind I want to support through return visits regularly.
ByronGlunc
September 29, 2026, at 2:29 amFelt the writer respected the topic without being precious about it, and a look at seameadowvendorworks continued that respectful but unfussy treatment, finding the right register for serious topics is hard and this site has clearly figured out how to take the topic seriously while still being readable for casual visitors regularly.
RafaelTenry
September 29, 2026, at 2:37 amplay blackjack online for real money legalne casino online automaty online o penize Retro automaty zdarma na skusku ruleta hra online zadarmo blackjack online slovakia
TommyDap
September 29, 2026, at 2:37 amReally like the way the post resists reaching for cliches that would have made it feel generic, and a quick visit to olivecovecommerceatelier kept that fresh feel going, original phrasing and unexpected metaphors are signs that the writer is actually thinking rather than just stitching together familiar phrases into the appearance of content.
LeonardJen
September 29, 2026, at 2:41 amGoing to come back when I have more time to read carefully, the post deserves more than a quick scan, and a stop at nightstonecollective reinforced that, this is the kind of site that rewards a slower read which is hard to find in this fast paced corner of the internet but really worthwhile.
EmmettFuh
September 29, 2026, at 2:43 amGranted my mood today might be elevating my reading experience but I still think this is genuinely good, and a stop at jewelcoveartisanmarket reinforced that even discounted assessment, controlling for the mood adjustment that affects content perception this site still reads as substantively above average across multiple pieces I have read carefully today.
Kaifew
September 29, 2026, at 2:59 amCame away with some new perspectives I had not considered before, and after opalriveremporium those ideas felt more complete, the kind of content that stays with you a little while after reading rather than slipping out the moment you switch tabs and move on with your day to whatever comes next.
Jeremiaharern
September 29, 2026, at 3:07 amBetter than most of the writing I have come across on this topic recently, simpler and more direct, and a look at quickharboroutpost continued in that same way, a real outlier in a crowded space full of repetitive content that says little while taking up a lot of reader time today which is unfortunate.
RafaelTenry
September 29, 2026, at 3:31 amsceptre of cleo echtgeld hracie automaty admiral zdarma online casino bez nutnosti vkladu Sk free spiny casino bonus deposit double star casino bonus code
Michaelreods
September 29, 2026, at 3:46 amcasino Banzai
SlonPsymn
September 29, 2026, at 3:52 amВ УКАЗАННОЙ СТАТЬЕ СОБРАНЫ САМЫЕ АКТУАЛЬНЫЕ ССЫЛКИ И ПЕРЕХОДНИКИ НА ПЛОЩАДКУ КРАКЕН ЧЕРЕЗ ТОР.
СПИСОК ВСЕХ ДОСТУПНЫХ ССЫЛОК ДЛЯ ВХОДА НА [url=https://captcha-slon1.cc]KRAKЕN[/url]
РЕКОМЕНДУЕМ СОХРАНИТЬ СПИСОК К СЕБЕ, ТАК КАК СООБЩЕНИЯ ПОСТОЯННО УДАЛЯЮТ!
1) Официальная ссылка (взята из инструкции с площадки КРАКEН):
[url=https://captcha-slon1.cc]slon17.cc[/url]
2) Официальное зеркалo КРАКЕH:
[url=https://captcha-slon1.cc]slon9.to[/url]
3) Резервное зеркалo КРАКЕH:
[url=https://captcha-slon1.cc]slon17.cc[/url]
4) Запасная ссылка, если первая не работает (с использованием VPN):
https://captcha-slon1.cc
5) ТОР:
[url=https://captcha-slon1.cc]kraken2tradskbgfdhsuireorekg437hgksol.onion[/url]
Вот несколько рекомендаций, которые помогут вам быстро и безопасно попасть на сайт КРАКЕН:
1. Скачайте TOR браузер
Для доступа к даркнет-ресурсам, включая Кракен, вам потребуется специальный браузер, поддерживающий Onion-сайты. Самым популярным выбором является Tor браузер. Вот как его установить:
Перейдите на oфициальный сайт Tor проекта.
Скачайте установочный файл для вашей операционной системы.
Установите браузер, следуя инструкциям на экране.
2. Запустите Tor браузер
После установки откройте Tor браузер. Он автоматически начнет процесс подключения к сети Tor, что может занять несколько минут. Дождитесь завершения подключения.
3. Перейдите по актуальной ссылке
Используйте актуальную ссылку для доступа к сайту Кракен: Вставьте эту ссылку в адресную строку Tor браузера и нажмите Enter. Это перенаправит вас на главную страницу маркетплейса.
4. Создайте учетную запись
Если у вас еще нет аккаунта на Кракене, вам нужно будет зарегистрироваться. Процесс регистрации включает следующие шаги:
На главной странице Кракена найдите кнопку “Регистрация” и нажмите на нее.
Заполните форму регистрации, указав необходимую информацию, такую как логин, пароль и адрес электронной почты.
Используйте надежный пароль и включите двухфакторную аутентификацию для дополнительной безопасности.
5. Зарегистрируйтесь на сайте
После регистрации войдите в свой личный кабинет, используя указанные при регистрации логин и пароль. Убедитесь, что вы используете только актуальные ссылки и проверенные источники для доступа к Кракену.
Меры безопасности при использовании Кракена?
Пользуясь даркнет-маркетплейсами, важно соблюдать меры предосторожности. Вот несколько советов, которые помогут вам обезопасить себя:
Обновляйте ссылки! И сохраните последние АКТУАЛЬНЫЕ
[url=https://captcha-slon1.cc]slon6.at[/url]
Даркнет-сайты часто меняют свои адреса из-за соображений безопасности. Регулярно проверяйте актуальные ссылки на форумах и официальных источниках, чтобы быть уверенными в правильности используемой ссылки.
Используйте VPN!
Для дополнительной анонимности и безопасности рекомендуется использовать VPN-сервис. Он скроет ваш IP-адрес и сделает ваше пребывание в интернете более безопасным.
Будьте осторожны!
кракен сайт
кракен официальный сайт
кракен сайт kr2connect co
кракен сайт магазин
ссылка на сайт кракен
кракен зеркало сайта
moment
кракен сайт даркнет
сайт кракен тор
кракен рабочий сайт
кракен сайт маркетплейс
kraken даркнет
kraken официальный сайт
ссылка кракен
кракен ссылка
kraken top
кракен ссылка
kraken официальный сайт
kraken даркнет
кракен onion
flea
kraken площадка
kraken onion link
kraken даркнет onion
кракен сайт даркнет
кракен официальный
сайт кракен
даркнет кракен
shop
кракен ссылка зеркало
кракен сайт ссылка
сайт кракен top
kraken onion
onion сайты
kraken сайт
даркнет-рынок сайт
ссылки на даркнет
площадка кракен
ссылка на кракен в top
кракен даркнет ссылка
ссылки даркнет
даркнет сайт
кракен ссылка даркнет
kraken onion ссылка
кракен сайт тор ссылка
кракен onion
kraken ссылка onion
кракен ссылка на сайт
кракен ссылка top
кракен сайт
kraken вход
кракен торговая площадка
кракен даркнет
kraken магазин
сайты даркнет ссылки
даркнет рынок сайты
ссылка на кракен даркнет
кракен вход
кракен площадка
orca
hydra marketplace
кракен даркнет маркет
кракен площадка ссылка
даркнет сайт
rhfrty
кракен магазин наркотиков
даркнет зайти
кракен площадка даркнет
гидра кракен
kraken гидра
кракин
даркнет скачать
реклама гидры
onion сайты
даркнет войти
как войти в даркнет с айфона
даркнет с телефона
kraken hydra
кракен гидра
не заходит в тор
tor ссылки
кракен магазин
поисковики тор ссылки
не грузит тор
как войти в тор
что будет если зайти в даркнет
скачать браузер тор
tor браузер
kraken
поисковые системы тор
гидра ссылка
даркнэт
через какой браузер можно зайти в даркнет
kraken Russia
как работает даркнет
tor даркнет
kracken
тор 2022
кто такой кракен фото
кракены
что есть в даркнете
дарк нет это
открыть ссылку через впн онлайн
кракен купить
как пользоваться tor
гидра магазин
кракен
даркнеи
kraken (даркнет-рынок)
кракен новая гидра
ссылка на кракен
WallaceTus
September 29, 2026, at 5:09 amMost blog writing on this subject reaches for the same handful of arguments and this post avoided them, and a look at garnetridgegoodsstore continued the original treatment, content that finds its own path through territory other writers have flattened is content with real authorial energy and this site has plenty of that distinctive energy.
Thomasgek
September 29, 2026, at 5:34 am[url=https://novobancoptonline.com/]NOVO BANCO EMPRESAS[/url]
O NOVO BANCO apresenta as informações de forma clara e organizada, tornando mais simples conhecer os serviços disponíveis e encontrar os canais adequados de atendimento.
RafaelTenry
September 29, 2026, at 5:36 amvytvoriЕҐ ruletu otГЎzok online kajot zdarma automaty hracie automaty stahuj zdarma Retro automaty zadarmo free spiny pre registrovanГЅch casino free spins bez vkladu
Genevib
September 29, 2026, at 5:49 amIf I am being honest this is the kind of site I quietly hope my own work will someday resemble, and a stop at jasperharborcraftcollective extended that aspirational feeling, finding work that models what I want to produce is part of why I read carefully and this site has been performing that modelling function for me lately consistently.
RafaelTenry
September 29, 2026, at 5:49 amfree spiny na narozeniny casino bonusy k narozeninam ice casino 25€ no deposit Navod ako hrat automaty doxxbet bonus za registraciu online automaty zdarma bez registrace
Zacharyhog
September 29, 2026, at 5:49 amClosed it feeling slightly more competent in the topic than I started, and a stop at suncovegallery reinforced that competence boost, real learning is rare in casual online reading but it does happen sometimes and this site managed to make it happen for me today which is genuinely worth pausing to acknowledge.
PatrickAcelp
September 29, 2026, at 5:55 amDecided to set aside time later to read more carefully, and a stop at autumncoveartisanhouse reinforced that decision, content that earns a calendar entry rather than just a passing read is in a different tier altogether and this site is clearly working at that elevated level which I really do appreciate as a reader today.
Steveglils
September 29, 2026, at 6:31 amHigh quality writing, no marketing speak and no buzzwords that mean nothing, and a stop at kitchenkismet kept that going, simple direct content that actually communicates something is harder to find than it should be and this is one of the rare places that gets it right consistently across many different posts.
RafaelTenry
September 29, 2026, at 6:42 amsazka online automaty blackjack online sk Which is the most trusted online casino Free spiny na sk casine fortune double demo blackjack online poДЌГtanie kariet
CarlWrise
September 29, 2026, at 6:49 amIf a friend asked me where to read carefully on the topic I would send them here without hesitation, and a look at pebbletrailartisanmart confirmed the recommendation strength, the directness of my recommendation reflects how confident I am in the quality and this site has earned undiluted recommendations from me across multiple recent conversations actually.
VernonEmast
September 29, 2026, at 7:24 amMy time on this site has now extended past what I had budgeted, and a stop at brightharbortrading keeps extending it further, content that overstays its budget in my schedule is content that has earned the extra time and this site has been earning extra time across multiple visits to the point where my schedule needs adjustment.
Damiondaday
September 29, 2026, at 8:01 amReading this on the train into work was a better use of the commute than my usual choices, and a stop at snowridgegoodsstore extended that commute reading well, content that improves transit time rather than just filling it is content with practical benefit and this site has earned its place in my morning commute reading rotation.
Stephenquome
September 29, 2026, at 8:24 amblackjack online with friends no money
blackjack online sk nemecke casino bonus bez vkladu casino nove online
online casino vstupnГЅ bonus play fortuna РІС…РѕРґ
Petertib
September 29, 2026, at 8:31 amRecommended without hesitation if you care about careful coverage of this topic, and a stop at ivoryridgeoutpost reinforced the recommendation, the bar I set for unhesitating recommendations is fairly high and this site has cleared it through the cumulative weight of multiple consistently good pieces rather than through any single standout post which is meaningful.
Rufusnuake
September 29, 2026, at 8:42 amNow planning to recommend this site in a context where my recommendations are taken seriously, and a stop at opalstonegalleria confirmed I should make that recommendation soon, the small but real act of recommending content into spaces where my taste matters is something I take seriously and this site is worth the recommendation.
ByronEurog
September 29, 2026, at 8:45 amNow noticing how rare it is to find a site that does not feel rushed, and a look at skycoveartisanmart extended that calm pace, content produced without time pressure has a different quality than content shipped to meet a deadline and this site reads as written without urgency which produces a different and better experience for readers.
Stephenquome
September 29, 2026, at 8:46 amcasino google pay
ДЌeskГ© casino bonus za registraci bez vkladu vlozit peniaze do casina cez mobil hracie automaty zdarma admiral
21 co uk live casino 3valcove automaty zdarma ultra hot
Brucefek
September 29, 2026, at 8:47 amboo casino 5 € hracie automati hrat zadarmo automaty online vstupný bonus Kasino s nizkym vkladom 1 eur What are some classic casino games fruit shake automaty zdarma
Brucefek
September 29, 2026, at 9:00 am5 € zdarma hracie automaty zdarma dolphins pearl online automaty za penГze Registracny bonus 5 eur casino 4 games casino automaty zdarma ruleta
Stephenquome
September 29, 2026, at 9:05 amcasino free spins bez vkladu
hracie automaty bonanza nemecke online casino s bonusom bez vkladu 5 valcove hracie automaty davkou modernosti
ruleta online zdarma hrat o peniaze
CaryFal
September 29, 2026, at 9:47 amProbably this is one of the better quiet successes on the open web at the moment, and a look at silkridgeartisanmarket reinforced that quiet success quality, sites that are doing well without making a noise about doing well are the sites I most respect and this one has clearly chosen the quiet success path consistently throughout.
Brucefek
September 29, 2026, at 9:53 amfree spiny bez registrace hracie automaty 5 vГЎlcovГ© zdarma automaty zdarma za registrГЎciu Dnesne free spiny bez vkladu online casino eu najlepЕЎie mastercard kasГna
Ottocooge
September 29, 2026, at 10:35 amA relief to read something where I did not have to fact check every claim mentally, and a look at jasperharboremporium continued that reliable feeling, sites where I can lower my guard and trust the content are rare and this one is earning that trust paragraph by paragraph through consistent careful work behind the scenes.
Stephenquome
September 29, 2026, at 11:23 ambest spigo online slots
fortuna casino bonusy kasyno w ktorym wystarczy depozyt 10 zl casino haniska pri preЕЎove
automaty na online hry bonusy bez vkladu 2026
Romanploms
September 29, 2026, at 11:32 amA thoughtful read in a week that has been mostly noisy, and a look at lemonlarkartisanexchange carried that thoughtful quality across more pages, finding pockets of considered writing in a week of distractions is one of the small wins of careful curation and this site is providing those pockets at a sustainable rate.
BillyAmomy
September 29, 2026, at 11:42 amBookmark moved to my permanent reference folder rather than the casual maybe later folder, and a look at quickridgeoutletmarket earned the same upgrade, the distinction between casual interest and lasting reference is something I track carefully and very few sites cross that threshold but this one did so without much effort apparently.
Stephenquome
September 29, 2026, at 11:44 amsk casino bonus za registraci
ruleta online na vГЅber wybierz casino online w Polsce automaty hry zdarma ultra hot
hracie automaty zdarma apollo ruleta free online
Brucefek
September 29, 2026, at 11:55 amfree bonus za registraciu 5 stones automat casino vstupny bonus bez vkladu Casino bonus casino ziar nad hronom casino bonus bez vkladu free spiny
NkrutkaTG833Ler
September 29, 2026, at 11:58 amКто уже пользовался накрутку реакций тг. На постоянку. Смотрел несколько, взял тут: [url=https://nakrutka-reakcij-v-tg-1682.ru]nakrutka-reakcij-v-tg-1682.ru[/url]. Результат ок. Для постов хватило.
Stephenquome
September 29, 2026, at 12:03 pmvulkanbet no deposit
bonus za vklad dnes aplikacja mobilna kasyna online online hry automaty zadarmo
casino hry – hracie automaty hracie automaty trenДЌГn
Brucefek
September 29, 2026, at 12:08 pmhracie automaty zdarmaamerikan poker ii grand mondial casino prihlГЎsenie online hry zdarma automaty Automaty s bonusovymi spinmi What are normal casino games automaty hry zdarma online
NkrutkaTG833Ler
September 29, 2026, at 12:25 pmПосоветуйте кто ставит реакции на посты в тг. На постоянку. Смотрел несколько, посоветовали этот: [url=https://nakrutka-reakcij-v-tg-1682.ru]накрутка реакций в тг[/url]. Повторно заказывал. На канал пойдёт.
NakrutkaTG1050Royaw
September 29, 2026, at 12:26 pmИщу кто делает накрутку реакций в телеграм быстро. Нужны были живые реакции без ботов. Посоветовали: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-474.ru[/url]. Оплатил — сделали нормально. Для канала зашло.
GeorgeNak
September 29, 2026, at 12:52 pmhttps://mxcoco-mx.com
NakrutkaTG1050Royaw
September 29, 2026, at 12:55 pmПосоветуйте сервис накрутку реакций телеграм без бана. Нужны были живые реакции без ботов. Посоветовали: [url=https://nakrutka-reakcij-v-tg-1050.ru]nakrutka-reakcij-v-tg-1050.ru[/url]. Оплатил — цена адекватная. Норм вариант.
HughNot
September 29, 2026, at 1:24 pmA welcome contrast to the loud takes that have dominated my feed lately, and a look at silverharborcollective extended that calm voice, content that arrives without yelling has become unusual in the modern attention economy and this site is one of the few places I have found that consistently delivers without raising its voice.
Nashmak
September 29, 2026, at 1:25 pmA genuine compliment to the writer for keeping the post focused on what mattered, and a look at dawnbrookartisanbazaar continued that disciplined focus, focus is a editorial choice that compounds across many small decisions and this site has clearly made those small decisions consistently across what I have read so far this week here.
Emiliones
September 29, 2026, at 1:53 pmBetter than the average post on this subject by some distance, and a look at floraridgeemporium reinforced that, you can tell within the first paragraph that the writer here actually cares about the topic rather than just covering it for the sake of having something to publish that week or that day.
playf_tfMl
September 29, 2026, at 1:56 pmIch bin mittlerweile seit dem Fruehling bei Play Fortuna angemeldet, also kann ich inzwischen aus eigener Erfahrung berichten. Ein Kollege hat es empfohlen, weil mich das Spielangebot angesprochen hat.
Der Spielkatalog bei Play Fortuna ist wirklich umfangreich: Pragmatic, NetEnt und Nolimit City sind alle vertreten. Book of Dead und Starburst findet man sofort, die Nolimit-Titel sind fuer mich das Highlight. Evolution betreibt die Live-Tische: Roulette, Blackjack und Baccarat mit deutschen Dealern. Deutschsprachige Dealer gibt es in der Hauptzeit.
Das Startpaket hier umfasst einen Match-Bonus plus Freispiele, dazu Freispiele in Tagesraten. Wagering liegt bei 40x, im oberen Bereich aber machbar. Aktuelle Codes und Angebote findet man auf [url=https://blogger-ratgeber.com]play fortuna[/url] vor der Einzahlung pruefen. Reload-Boni gibt es woechentlich.
Man kann ab 10 Euro starten. Die ueblichen Zahlungsmethoden gehen problemlos, Bitcoin wird ebenfalls angenommen. Per Wallet ging es in unter 24 Stunden, Bankueberweisungen dauerten laenger. Verifizierung lief glatt — Personalausweis hochgeladen und in Stunden bestaetigt.
Auf dem Handy nutze ich die mobile Webseite, die Seite laedt schnell. Kundenservice spricht Deutsch und reagiert innerhalb weniger Minuten. Es gilt eine Curacao-Lizenz, was man wissen sollte. Unterm Strich stimmt die Zahlungsmoral.
SterlingBen
September 29, 2026, at 2:02 pmLooking through the archives suggests this site has been doing this for a while at this level, and a look at cottongroveemporium confirmed the long term consistency, sites that have maintained quality across years rather than just a recent stretch are sites with serious editorial discipline and this one has clearly been at it for a while.
Jeffreyenarp
September 29, 2026, at 2:17 pmAphrodite Casino
Stephenquome
September 29, 2026, at 2:18 pm1 win bonus casino
kde urobiЕҐ ruletu online polskie casino online ggbet casino 25 euro bonus
eu casino bonus online automaty za peniaze uvitaci bonus bez vkladu
CordellOreft
September 29, 2026, at 2:27 pmProbably one of the more reliable sources I have found for this kind of careful coverage, and a look at ivorycoveartisanmart reinforced the reliability, the small group of sources I would describe as reliable for a given topic is curated carefully and this site has earned a place in that small group through consistent performance.
Mauricewef
September 29, 2026, at 2:28 pmThe whole experience of reading this was pleasant from start to finish, no pop ups and no annoying interruptions, and a look at gildedcovegallery continued that clean experience, technical choices about page design matter for the reader and this site clearly cares about the small details that add up to comfort across multiple visits.
Stephenquome
September 29, 2026, at 2:40 pmplay fortuna официальный сайт вход
casino no deposit bonus slovakia sprawdz najlepsze kasyno online w Polsce fortuna free spiny dnes
hracie automaty online zadarmo kajot star joker slot
pasecRaiff
September 29, 2026, at 2:57 pmLooking for casino game aggregator? Want to bring live games, slots, payment systems, and betting providers together under one unified infrastructure? Check out jackcode.io — we link game providers, PSPs, KYC services, CRMs, and aggregators via a robust, reliable architecture. We also offer turnkey online casino solutions, ranging from White Label platforms to fully turnkey setups that include game providers, payment systems, bonus tools, and back-office functionality.
Stephenquome
September 29, 2026, at 2:58 pm200 bonus casino
kartГЎДЌ casino bonus bez vkladu platnosci w kasynach internetowych online casino na slovensku
abecednГЎ ruleta online automaty zdarma sizzling hot deluxe
Brucefek
September 29, 2026, at 3:01 pmcasino fortuna bonus slovenskГ© casino pro ДЌeskГ© hrГЎДЌe hracie automaty zadarmo na mobil Vklad do casina pomocou sms registracny bonus casino najlepsia hra na automate
Brendankiday
September 29, 2026, at 3:12 pmA piece that prompted a small mental rearrangement of how I order related ideas, and a look at canyonharborvault extended that rearranging effect, content that affects the structure of my thinking rather than just adding to it is content with the deepest kind of impact and this site is reaching that depth for me today.
Brucefek
September 29, 2026, at 3:14 pmautomaty zdarma automaty 4 valcove realne hracie automaty apollon games hracie automaty Hry online za peniaze stiahnut zdarma hracie automaty automaty apollo online
FranklinNOx
September 29, 2026, at 3:22 pmFelt like the writer was speaking directly to someone with my level of curiosity, neither talking down nor showing off, and a stop at solarorchardtrading kept that comfortable matching going, finding writing that meets you where you are rather than asking you to climb up or stoop down feels great every time it happens.
ClydeJex
September 29, 2026, at 3:28 pmNow considering whether the post would translate well into a different form, and a look at pearlharborgoodsstore suggested similar versatility, content that could move into other media without losing its substance is content that has been built around ideas rather than around format and this site reads as idea first throughout posts.
Gordonwrorn
September 29, 2026, at 4:02 pmAppreciated the way each section connected smoothly to the next without abrupt jumps, and a stop at birchstoneoutpost kept that flow going nicely, transitions are something most blog writers ignore but the difference is huge for the reader who is trying to follow a sustained line of thought today across many different topics.
Antoniodeape
September 29, 2026, at 4:02 pmNow considering carefully how to share this site with the right audience rather than broadcasting widely, and a look at zenwillowtrading extended that careful sharing impulse, content worth sharing carefully rather than spamming is content that has earned a higher kind of recommendation and this site has earned that careful shareability throughout pieces.
Evanvomia
September 29, 2026, at 4:04 pmBookmark added with a small mental note that this is a site to keep, and a look at cloudcovevault reinforced the keep status, the verb keep rather than visit captures something about how I think about this kind of site and it is a higher tier of relationship than I have with most places online today.
Brucefek
September 29, 2026, at 4:08 pm1 € casino bonus What is the 1 3 2 6 strategy daň za nevýherné hracie automaty Zahraj si automaty o peniaze hri automati zdarma bes registracie kajot sceptre of cleo echtgeld
rever_erKl
September 29, 2026, at 4:35 pmI’ve been punting at Trino Casino for about four months now, mostly late at night, so take this as a regular player’s take. Registered after a thread on another forum, and the whole thing took under five minutes — just email and a password, although you do need verification before the first payout, which I expected.
The lobby is deeper than I thought — around 3,500 games by my rough count. Pragmatic dominates, so you get the obvious ones — Gates of Olympus and Sweet Bonanza pinned to the popular tab. Play’n GO supplies Book of Dead, and there’s a decent amount of NetEnt in there too. I tend to live in Big Time Gaming stuff when I’ve got patience.
The bonus on Trino Casino is 100% up to ?500 plus 200 free spins, split across your first two top-ups. Playthrough is 35x on the bonus, which is neither great nor awful. Minimum is a tenner. They also run a no-deposit spins offer sometimes — it’s not always live, so it’s worth a see the latest offers over on [url=https://harris.malebe.itvarsitystudent.org/?p=84276]trino casino[/url] before you commit.
Withdrawals are the bit that matters, and on this front Trino hasn’t messed me around. Cashed out a few hundred to Neteller last week and it cleared next morning. Visa and Mastercard are there, Skrill and Neteller are faster, and they take Bitcoin and a couple of altcoins for anyone who bothers. The one thing that annoyed me: bank transfers were painfully slow the first time.
Live chat is 24/7 and the agents aren’t just copy-pasting scripts, though getting a human took a while during peak hours. The live section runs on Evolution, so real croupiers, decent blackjack and roulette tables, plus Crazy Time if you like the game show stuff — I don’t, much. There’s no dedicated app, only a browser version, and it is fine on iPhone but occasionally logs me out mid-spin.
Reggievax
September 29, 2026, at 5:12 pmFound something quietly useful here that I expect to return to, and a stop at iciclemeadowtraders added more of the same, content with quiet utility ages well in a way that flashy hot takes do not and I have learned to weight quiet utility much higher when deciding what to bookmark for later use.
Stephenquome
September 29, 2026, at 5:16 pmblackjack stratГ©gia pre zaДЌiatoДЌnГkov
hracie automaty bonus jak wplacic paysafecard do kasyna nye online casino
hracie automaty cez sms za kredit skГєsenosti s automatom asena
Stephenquome
September 29, 2026, at 5:38 pmcasino bet vip
bedste live casino casino s minimalnym vkladom dvadsat eur hrat hry zdarma automaty
casino hry zdarma automaty egt hracie automaty cez sms online
TobiasImavy
September 29, 2026, at 5:50 pmEasy to recommend, the content speaks for itself without needing additional praise from me, and a stop at jewelbrookvault only adds more reasons to send people this way, the kind of generous resource that benefits its readers without demanding anything in return is increasingly rare and worth recognising clearly today across the broader open internet.
Stephenquome
September 29, 2026, at 5:57 pmonline casino pre zabavu
casino online slot machine kasyno online dla Polakow automaty ke stazeni zdarma
iron bank slot automaty hry zdarma bez registrace bez omezenГ doby
Brucefek
September 29, 2026, at 6:15 pmcasinorewards vip bonus automaty ke stazeni zdarma do mobilu strip blackjack online casino Ako spravne hrat automaty 3 valcove automaty online zdarma casino slot gratis
Bryannah
September 29, 2026, at 6:20 pmPicked up something useful for a side project, and a look at meadowharboroutpost added another piece I will incorporate, content that connects to specific projects I am working on is content with practical utility and the practical utility of this site is showing up across multiple posts I have read in the last hour or so.
Brucefek
September 29, 2026, at 6:28 pmako vyhraЕҐ jackpot na automatoch automaty zdarma szzlГg hot Which game gives real money online Kasina s minimalnym vkladom 20 eur free blackjack online multiplayer ceske casino pre slovakov
EmeryCit
September 29, 2026, at 6:45 pmA particular kind of restraint shows up in the writing, and a look at raintrailartisanmarket maintained the same restraint across pages, knowing what not to say is just as important as knowing what to say and this site has clearly developed strong instincts on both sides of that editorial line throughout pieces I have read.
Hugoeralf
September 29, 2026, at 7:11 pmStarted imagining how I would explain the topic to someone else after reading, and a look at plumcovevault gave me more material for that imagined explanation, content that improves my own ability to discuss a topic is content that has actually transferred knowledge rather than just decorating my screen for a few minutes.
JamalLox
September 29, 2026, at 7:15 pmQuietly the writers approach to the topic differs from the dominant takes I have been encountering, and a stop at mintcovecommerceatelier extended that distinctive approach, content that maintains a different perspective without explicitly arguing against the dominant ones is content with confident editorial identity and this site has that confidence throughout pieces.
Brucefek
September 29, 2026, at 7:22 pmroyal casino live chat automaty online zdarma mega joker ako hraЕҐ automaty Automaty na peniaze hrat hry automati zdarma joker hrat automaty online
Kennypat
September 29, 2026, at 7:45 pmhttps://t.me/KohLantaKrabiThailand/ ко ланта
OwenDep
September 29, 2026, at 7:46 pmReading this confirmed a small detail I had been uncertain about, and a stop at orchardharborvault provided the source for further checking, content that supports verification through citations or links rather than just asserting facts is more trustworthy and this site has clearly built its credibility through that kind of verifiable approach consistently.
OliverHEt
September 29, 2026, at 8:13 pmThe conclusions felt earned rather than tacked on at the end like an afterthought, and a look at tealcoveartisanmart kept that careful structure going, you can tell when a writer has thought about the shape of their post versus just letting it ramble out and hoping for the best at the end which most do.
ThomasKib
September 29, 2026, at 8:16 pmonline automaty za peniaze uvitaci bonus bez vkladu
hracie automaty zdarma hunter’s dicer zagraj w kasynie na prawdziwe pieniadze casino vklad paysafecard
losovanie ruleta online ceske casino bonus bez vkladu
GermanAlbus
September 29, 2026, at 8:19 pmThanks for the practical examples scattered through the post rather than abstract theory only, and a look at crystalcovecraftcollective continued that grounded style, abstract points are easier to remember when paired with concrete situations and the writers here clearly understand how readers actually retain information from blog content reading sessions.
ThomasKib
September 29, 2026, at 8:38 pmblackjack online zadarmo bez registrГЎcie
casino bonus bez vkladu zahranicne bonus bez vkladu v zahranicnom casine najlepsie slovenske kasino
hrat hracie automaty zdarma bez registrace free spiny na narozeniny
ThomasKib
September 29, 2026, at 8:57 pmonline casino vklad sms
live casino rewards login kasyno z depozytem od 20 zl Which gambling sites give free money
5 euro deposit casino nejlepsi online casina
BrentLounc
September 29, 2026, at 9:28 pmWhat is the best no deposit casino casino mimo ДЌr automaty online na psc Mobilne kasino s bonusom 10 eur automaty zdarma fronzy ca online slovensko
BrentLounc
September 29, 2026, at 9:41 pmonline ruleta live blackjack online reviews casino online bonus sk Vklad 20 eur blackjack online betting casino online zadarmo
BartholomewAvecy
September 29, 2026, at 9:59 pmTop notch writing, every paragraph carries weight and nothing feels like filler, and a stop at rivercoveartisanhouse reflected that same care, a rare thing on the open web these days where most pages exist for clicks rather than actual reader value or anything close to that which is honestly a real shame.
BrentLounc
September 29, 2026, at 10:35 pmsynot hracie automaty zadarmo hracГ automaty zdarma online sk olybet sk bonus Kasino s minimalnym vkladom 1 eur hry zdarma hracie automaty casino vklad cez sms orange
Sterlingpounk
September 29, 2026, at 10:47 pmFollowing the post through to the end without my attention drifting once, and a look at lanterncoveartisanmarket earned the same uninterrupted attention, content that holds attention without manipulating it is content with substantive pull and this site has demonstrated that substantive pull across multiple pieces in a single reading session reliably here today.
Liamcob
September 29, 2026, at 10:58 pmConsidered against the flood of similar content this one stands apart in important ways, and a stop at vionessa extended that distinctive feel, sites that find their own corner of a crowded topic and stay there are sites worth following and this one has clearly carved out its own space and committed to defending it carefully.
ThomasKib
September 29, 2026, at 11:16 pmcasino 10 € free
power casino 5 € polskie gry kasynowe online hracie automaty online zdarma bez registrace
bonus casino 2026 spiny zadarmo za registrГЎciu
DarrellAnelp
September 29, 2026, at 11:26 pmPicked this up between two other things I was doing and got drawn in completely, and after goldencoveoutpost my original tasks were completely forgotten for a while, content that derails a workflow in a positive way by being more interesting than what you were already doing is rare and worth recognising clearly.
ThomasKib
September 29, 2026, at 11:38 pmWhat are casino free spins no deposit
casino fortuna sk przeglad najnowszych kasyn online villento casino bonus
casino bonus bez vkladu bez podmienok automaty online hrat zdrma
Carminepex
September 29, 2026, at 11:42 pmLiked the way the post got out of its own way, and a stop at lavenderharborcollectivemart extended that invisible craft, the best writing you barely notice while reading because it is doing its work without drawing attention to itself and this site has clearly mastered that disappearing act across the pieces I have read.
ThomasKib
September 29, 2026, at 11:57 pmcasino hry free games play vyherni automaty zdarma
star casino bonus bez vkladu kasyno z wplata paysafecard online casino free spiny
online casino bez vkladu bonus crazy time live casino
Elijahbus
September 30, 2026, at 12:24 amDecided not to comment because the post said what needed saying, and a stop at windmeadowcollectivemart continued that complete feel, content that does not invite obvious additions or corrections from readers is content that has been carefully considered and this site appears to consistently produce pieces that satisfy rather than provoke unnecessary follow ups.
BrentLounc
September 30, 2026, at 12:41 amsk online casino stare hracie automaty pinball vyherne hry hrat Hracie automaty online zdarma casino bonus 20 euro licencia pre online casino slovensko
JulianbydaY
September 30, 2026, at 12:49 amQuietly impressive in a way that does not announce itself, and a stop at coppercoveartisanexchange extended that quiet impressiveness, the kind of quality that emerges through sustained attention rather than first impressions is the kind I trust more deeply and this site has been earning that deeper trust across multiple sessions over time consistently.
BrentLounc
September 30, 2026, at 12:55 amcasinorewards vip bonus sk casino bonus online casino s licenciou Online hry o peniaze hracie automaty free hra penez online sk
BrentLounc
September 30, 2026, at 1:48 amcasino live sk ruleta zadarmo online Can I play real money on PokerStars Sms vklad casino vklad cez paypal nove casino bez vkladu
rever_tmKl
September 30, 2026, at 1:50 amBin da jetzt seit gut vier Monaten dabei, also rede ich nicht komplett ins Blaue. Die Lobby bei Crypto Control ist ziemlich fett — irgendwas um die 3000 Titel, hab ehrlich gesagt nicht nachgezahlt. NetEnt und Betsoft sind stark vertreten, Gates of Olympus und Sweet Bonanza laufen bei mir am meisten.
Das Startpaket war offen gesagt der Ausloser, warum ich uberhaupt angefangen hab. 100% bis 500 Euro plus 200 Freispiele, aufgeteilt uber mehrere Tage. Kleiner Wermutstropfen: man muss 35-fach umsetzen, fair genug, trotzdem nicht geschenkt. Einen kleinen No-Deposit-Teil mit 20 Spins gab’s auch, das rotiert allerdings dauernd.
Wer sich das anschauen will, findet die aktuellen Konditionen auf [url=https://ieeegit.in/solana-casino-uberblick-und-optionen-fur-deutsche-spieler/]solana casino[/url] , kurz die AGB uberfliegen schadet nie. Ab 20 Euro geht’s los, Konto war fix erstellt.
Was das Abheben angeht lief es besser als gedacht: mit Bitcoin war das Geld nach etwa einer Stunde da, uber Neteller etwa einen Werktag. Kreditkarte klappt ebenfalls, da wurde ich aber mit zwei bis drei Tagen rechnen. Die Verifizierung bei Crypto Control war nervig — Ausweis, Selfie, Adressnachweis, das volle Programm.
Am Abend lande ich fast immer bei den Live-Tischen. Die Tische kommen von Evolution, Crazy Time ist bei mir Pflichtprogramm, dazu die ublichen Blackjack- und Roulette-Tische. Fur uns aus Deutschland sind ein paar deutschsprachige Tische dabei, nicht an allen, aber immerhin.
Auf dem Smartphone geht’s uber den Browser, eine eigene App gibt’s nicht, vermisse ich aber nicht. Beim Support von Crypto Control bekommt man auf Deutsch Antwort, meistens innerhalb von funf Minuten, manchmal muss man halt zweimal nachhaken. Lauft unter Curacao-Lizenz, also nicht nach deutschem Glucksspielstaatsvertrag reguliert, das sollte einem klar sein.
Douglasfaupt
September 30, 2026, at 2:01 amDuring a reading session that included several other sources this one stood out, and a look at elmstoneemporium continued the standout quality, the side by side comparison of sources during research is a useful exercise and this site has been winning those comparisons for me consistently across multiple research sessions during the last week.
ThomasKib
September 30, 2026, at 2:15 am5e no deposit bonus
heat hracie automaty zdarma a bez registrace bonus bez vkladu v zahranicnom casine live casino stream
excel kasГno poprad slovenskГ© casino online
ThomasKib
September 30, 2026, at 2:37 amnГЎhodnГЎ ruleta online hra
golden star casino kasyno online bez KYC 5 € casino
fortuna casino bonus vyber new online casinos
ThomasKib
September 30, 2026, at 2:55 amspigo slot sites
stiahnut hru hracie automaty metody platnosci w kasynach online hot automaty online
hracie automaty za realne peniaze aplikacia chracie automaty zdarma bezregistrace
BrentLounc
September 30, 2026, at 3:55 amhracie automaty triky bep bep casino hracie automaty kajot zdarma Kasino s minimalnym vkladom 1 eur novГ© online casino 2026 hracie automati kajoti zadarmo
BrentLounc
September 30, 2026, at 4:08 amblackjack online betting valcove automaty online zdarma promo akcie kasino Free spiny v sk casine blackjack online zadarmo 5 valcove hracie automaty s davkou modernosti
RustyMen
September 30, 2026, at 4:09 amThanks for keeping the writing direct without losing the warmth that makes content feel human, and a stop at nightcoveartisanmarket carried both qualities forward, balancing professionalism and personality is a rare skill and the writers here have clearly figured out how to consistently land it across many posts which I notice.
vnfun888
September 30, 2026, at 4:39 amFound this site through a friend and it’s been a blast so far. The rewards system at vnfun888 is really generous.
BrentLounc
September 30, 2026, at 5:02 amautomaty zdarma turbo blackjack online betting free 7 € registrace Kasinove hry za peniaze mobil casino slovenský live casino bonus codes
RossPotly
September 30, 2026, at 5:09 amSpeaking carefully because I do not want to overstate things this site is genuinely above average across multiple measurements, and a stop at coppertrailartisanhouse continued the above average performance, the calibration of judgement against potential overstatement is something I take seriously and this site clears the higher bar even after that calibration applies.
ThomasKib
September 30, 2026, at 5:14 amcasino bonus bez vkladu zadarmo
zdarma bonus za registrГЎciu Kasina s minimalnym vkladom 20 eur bonus no deposit casino 2026
nejlepЕЎГ online casino casino v mobile
ForrestIntat
September 30, 2026, at 5:14 amCame away with a slightly better mental model of the topic than I started with, and a stop at emberridgevendorstudio sharpened that further, content that improves the reader thinking apparatus rather than just dumping facts into it is the rare kind I genuinely value and seek out when I have time to read carefully.
Christianhat
September 30, 2026, at 5:27 amOn reflection this is the kind of writing that improves my taste for what is possible in the format, and a look at iciclemeadowtrading continued raising that bar, content that elevates my expectations rather than lowering them is doing important work in calibrating my standards and this site is participating in that elevation reliably.
ThomasKib
September 30, 2026, at 5:36 amnove hracie automaty zadarmo
bonus za vklad casino kasyno online z niska minimalna wplata What is the WILD250 bonus code
hracГ automaty zdarma neomezenД› bez registrace zdarma online 1 eurovГЅch vkladovГЅch kasГn
ThomasKib
September 30, 2026, at 5:54 amhry automaty zdarma hraj
hracie arkadove automaty depozyt BLIK w kasynie online automaty hracie diamont
blackjack online game for fun dneЕЎnГ free spiny
MichaelGlush
September 30, 2026, at 7:08 am[url=https://ar-cocos-capital.shop/]CAPITAL COCOS[/url]
A Cocos Capital disponibiliza informações claras sobre seus produtos e serviços, permitindo conhecer melhor as soluções oferecidas pela empresa.
BrentLounc
September 30, 2026, at 7:09 amcasina s bonusem za registraci automaty hry zdarma 3 valcove ice casino no deposit bonus Kasino s nizkym vkladom 1 eur fortuna slot online play fortuna официальный сайт вход
BrentLounc
September 30, 2026, at 7:23 am5 free spin za registraci automaty 81 zdarma automaty zdarma nove Zahraj si automaty o peniaze free spiny sk online casino bonusy
Howardmom
September 30, 2026, at 7:24 amDecided not to comment because the post said what needed saying, and a stop at woodcovegallery continued that complete feel, content that does not invite obvious additions or corrections from readers is content that has been carefully considered and this site appears to consistently produce pieces that satisfy rather than provoke unnecessary follow ups.
WinstonMox
September 30, 2026, at 8:02 amCame in confused about the topic and left with a much firmer grasp on it, and after clovercrestvault I felt I could explain this to someone else without hesitation, that is the gold standard for any educational content and most sites simply fail to reach it ever which is unfortunate but true.
ThomasKib
September 30, 2026, at 8:14 amcasino bonus 5e
hracie automaty zdarma super rels 2 nemecke casino bonus bez vkladu 7 reels casino review
hry automaty zdarma book of ra aupark hracie automaty
BrentLounc
September 30, 2026, at 8:17 amhracie automaty zdarma 5 valcove dneЕЎnГ casino bonus hra ruleta online zdarma Turbo automaty zadarmo always hot deluxe Can you play free casino games on your phone
ThomasKib
September 30, 2026, at 8:35 amautomaty vlt zdarma
online automaty za oeniaze bez registracie kasyno online bez weryfikacji tozsamosci hrace automati zdarma
3 valcovГ© hracie automaty automaty kajot online
Garysuele
September 30, 2026, at 8:43 amAnyone curious about this topic would do well to start here, the foundation laid is solid, and a stop at birchharborvault would round out their understanding nicely, this is the kind of resource I would point a friend toward without hesitation if they asked me where to begin learning about anything in this area.
Mylesdek
September 30, 2026, at 8:48 amAppreciated that the writer trusted the reader to follow along without constant restating of earlier points, and a look at coralmeadowoutlet continued that respect for the reader, treating an audience as capable adults rather than as people to be hand held through every paragraph is something I notice and value highly across the open internet today.
AllenSyday
September 30, 2026, at 8:48 amA piece that built up gradually rather than front loading its main points, and a look at ferncoveoutpost maintained the same gradual structure, content that trusts the reader to reach conclusions through accumulating reasoning is more persuasive than content that announces conclusions and then defends them and this site uses the persuasive approach.
ThomasKib
September 30, 2026, at 8:54 am250 bonus casino
hracie automaty zdarma 4 valcove kajot 81 automaty bez vkladu automaty trnava hracie
vГЅhernГЅ automat cena Do gaming apps really pay money
Landynseity
September 30, 2026, at 9:10 amDecided to write a short note to the author if there is contact info anywhere, and a stop at timberforestvendoroutpost extended that intention, the urge to thank the writer directly is a strong signal of content quality and this site has triggered that urge in me today which is a fairly rare event for my reading.
Pedrorow
September 30, 2026, at 9:45 amNow setting this aside as a model of how to write thoughtfully on the topic, and a stop at oliveharborcollectivemart extended that model status, content that becomes a reference for how a kind of writing should be done is content with influence beyond its own readership and this site is reaching that level for me clearly today.
DaquanWeano
September 30, 2026, at 9:50 amReading this in the time it took to drink half a cup of coffee, and a stop at emailelm fit naturally into the second half, content that respects the rhythms of a typical morning is content with practical fit and this site has the kind of length and pacing that works for the way I actually read.
JeffersonIniny
September 30, 2026, at 9:55 amBig thanks to whoever wrote this, you saved me a lot of time hunting for the same info on other sites, and a stop at orchardcrestmarketplace only added more useful detail without going off topic, that kind of focus is honestly hard to come across these days when most posts wander everywhere.
BrentLounc
September 30, 2026, at 10:25 amquatro online casino nejlepsi online casino casino sk bonus za registrГЎciu Top kasino na slovensku live casino slovensko kde jsou free spiny zdarma
BrentLounc
September 30, 2026, at 10:38 amautomaty zdarma demonio automaty ke stazeni zdarma do mobilu online poker herne slovensko Kasino 10 eur ruleta online za skutoДЌnГ© peniaze automaty online sk
TomFurdy
September 30, 2026, at 10:51 amHonestly this kind of writing is why I still bother to read independent sites, and a look at dawnridgeoutpost extended that broader reflection, the few sites that justify continued attention to non algorithmic content are sites like this one and finding them periodically is enough to keep my reading habits oriented toward independent rather than aggregated content.
Morrisver
September 30, 2026, at 10:54 amGreat work on keeping things readable, the post never drags or repeats itself which I really appreciate, and a stop at valecovevault added a bit more context that fit naturally with what was already said here, no need to read everything twice to get the point being made today.
ThomasKib
September 30, 2026, at 11:11 amnajlepЕЎie vГЅhernГ© automaty online slovensko
slovenskГ© casino pro ДЌeskГ© hrГЎДЌe sprawdz legalne polskie kasyno online hracie automaty zdarma kajot 27
nove online casino v cr b casino 5 free
BrentLounc
September 30, 2026, at 11:32 amcasino bonus telegram nove casino bonusy daЕ€ za nevГЅhernГ© hracie automaty Online ruleta za realne peniaze aftershock frenzy casino casino automaty zdarma
ThomasKib
September 30, 2026, at 11:33 amnajlepЕЎГ blackjack online
big bass amazon xtreme demo nove bonusy v online casinach automati zdarma joker
online casino pre slovensko online casino bonus za registraciu bez vkladu
Chandlercoike
September 30, 2026, at 11:36 amWorth flagging that the post handled an angle of the topic I had not seen elsewhere, and a look at jaspermeadowemporium extended that fresh treatment, content that finds underexplored corners of well covered subjects is genuinely valuable and this site has demonstrated that exploratory editorial approach across multiple pieces in my reading sessions today.
Kareemhex
September 30, 2026, at 11:47 amSpeaking from the perspective of a fairly demanding reader the writing here clears the bar consistently, and a look at acornharborcollective continued clearing that bar, the calibration of demanding reader is something I apply to all sources and this site has been one of the few that handles the demanding reading well across pieces sampled.
ThomasKib
September 30, 2026, at 11:51 amhry za penГze
casino vklad sms zahranicne casino ktore dava bonus bez vkladu nove casino bonus za registraciu bez vkladu
live casino bet365 automaty zdarma fronzy
CoreyCendy
September 30, 2026, at 12:02 pmДоброго!
Аукцион доменных имен RU работает для тех, кто хочет получить проверенный актив. Короткое и запоминающееся имя легче продвигать в социальных сетях. В каталоге представлены сотни вариантов для разных ниш и тематик. Подпишитесь на обновления, чтобы не пропустить новые лоты. Инвестиция в качественный домен окупается уже в первый год.
Актуальные домены в продаже на сайте https://www.domenshop.net/
Всего наилучшего и хорошего развития!
Timicomy
September 30, 2026, at 12:05 pmLooking at this from the perspective of someone tired of generic content the contrast is striking, and a look at walnutcovecommerceatelier maintained that distinctive feel, sites with strong editorial identity stand out against the bland background of algorithmic content and this one has clearly developed an identity worth recognising through careful attention.
TerryfiZ
September 30, 2026, at 12:35 pmFound something quietly useful here that I expect to return to, and a stop at oakcovevault added more of the same, content with quiet utility ages well in a way that flashy hot takes do not and I have learned to weight quiet utility much higher when deciding what to bookmark for later use.
rever_vaKl
September 30, 2026, at 1:23 pmMi diverto su Slot Shopper da qualche mese e dopo un po’ di giri posso farmi un’idea. Il catalogo e bella grossa, intorno ai 2.500 giochi piu o meno, con NetEnt che tira la carretta. Book of Dead e sempre li in cima, e poi ci sono Yggdrasil e Betsoft per chi cerca cose piu cattive.
Il settore live e gestita da Evolution, quindi sai gia cosa aspettarti: croupier veri, anche tavoli italiani, non sempre pero, piu i soliti game show come Crazy Time sempre pieni di sera. Una cosa che mi ha dato fastidio: in 4G debole il flusso perde colpi, ma immagino sia colpa mia e non loro.
Sul pacchetto iniziale: su Slot Shopper il primo bonus e circa 100% fino a 500€ e ci mette 200 giri gratis, non tutti insieme ma a scaglioni. Il wagering e 30x solo sul bonus, non sul deposito, nella norma per il mercato italiano. Ci sono anche un piccolo no deposit da 10 giri se ti iscrivi alla newsletter, e comunque le condizioni esatte le trovi su [url=https://comprarecomendadasegura.com.br/slotshopper-in-italia-guida-pratica-per-scegliere-il-casino-online-perfetto/]slotshopper[/url] prima di depositare.
Il minimo per iniziare 10€, signup rapido con documento da caricare per il KYC. Io deposito con Neteller e i soldi sono rientrati in circa due giorni. Carte, Skrill, Neteller, bonifico e qualche opzione in Bitcoin, nessun problema di metodi. Il primo prelievo e stato piu lento per la verifica.
Da telefono si gioca via browser, il sito si adatta bene, niente di che ma nemmeno da bocciare. La chat di Slot Shopper e in italiano in chat, di solito entro dieci minuti, una volta mi hanno risolto un giro non accreditato senza fare storie. Sono regolati con licenza MGA, e sinceramente questo mi tranquillizza piu delle promo.
Andresmix
September 30, 2026, at 1:39 pmlive poker dealer najlepsie hry automaty casino m platba Vklad do casina cez sms ЕѕivГЎ ruleta online online casino zdarma
Shawnrotte
September 30, 2026, at 1:42 pmCame in skeptical of the angle and left mostly persuaded, and a stop at pebblegrovevendorstudio pushed me a bit further in the same direction, content that can move a critical reader by argument rather than rhetoric is rare and worth pointing out because it indicates real substance underneath the surface presentation here.
Nicodrodo
September 30, 2026, at 1:47 pmSpeaking as someone who used to recommend blogs frequently and got out of the habit this site is rekindling that impulse, and a look at meadowdockartisanbazaar extended the rekindling, the recovery of an old habit triggered by encountering work that justifies it is itself a small kind of pleasure and this site is providing that recovery experience.
Andresmix
September 30, 2026, at 1:52 pmnajlepsie online casino hry hracie automaty na stiahnutie zadarmo do mobilu How many types of gambling games are there Hry za realne peniaze sazka casino bonus bez vkladu online casino uvitaci bonus bez vkladu
RobertFauts
September 30, 2026, at 2:09 pmfree spiny za registraci
wild stars81 automaty zdarma online casino s vkladom od 1 eura malina casino no deposit bonus
ice casino bonus 20 € automaty zdarma kiwi
rever_qmKl
September 30, 2026, at 2:11 pmMi diverto su Slot Shopper da qualche mese e ormai posso parlarne senza sparare fesserie. La libreria e davvero ampia, circa 2.500 giochi piu o meno, con Play’n GO che fa il grosso del lavoro. Sweet Bonanza lo trovi subito in evidenza, e poi ci sono Yggdrasil e Betsoft per chi cerca cose piu cattive.
La parte live gira su Evolution, per cui il livello lo conosci: croupier veri, anche tavoli italiani, non sempre pero, piu i soliti game show come Crazy Time sempre pieni di sera. Quello che non mi e piaciuto: su connessione mobile scarsa il video scatta, magari e la mia rete, non voglio dare colpe a caso.
Sul bonus: su Slot Shopper il primo bonus e circa 100% fino a 500€ con in aggiunta 200 giri gratis, distribuiti in piu tranche. Il requisito di puntata sta sul 30x solo sul bonus, non sul deposito, onesto, niente di assurdo. Ci sono anche 20 free spin senza deposito in certi periodi, in ogni caso conviene guardare le promo aggiornate su [url=https://www.tsukubateklanka.com/slotshopper-in-italia-guida-completa-per-trovare-i-migliori-casino-online/]slotshopper[/url] perche cambiano spesso.
Deposito minimo 10 euro, signup rapido pero il KYC va fatto, non si scappa. Pago con la carta Visa con accredito in circa due giorni. Ci sono carte, e-wallet, bonifico e anche cripto, quindi scegli tu. La prima richiesta ci ha messo di piu perche stavano verificando i documenti.
Da mobile va tutto dal browser, il sito si adatta bene, niente di che ma nemmeno da bocciare. Il supporto di Slot Shopper risponde in italiano via live chat, tempi sui 5-10 minuti, una volta mi hanno risolto un giro non accreditato senza fare storie. Sono regolati con licenza di Malta, che e quello che guardo per primo.
RobertFauts
September 30, 2026, at 2:31 pmktore online casino je najlepsie
hracie automaty zdarma admiral ruleta zadarmo online slottojam casino no deposit bonus
beste casino online slots machine zadarmo
Andresmix
September 30, 2026, at 2:46 pmako si zvolit online casino online casino 1 € najlepsie internetove casino Automaty turbo blackjack online bonus no deposit automaty zdarma za registráciu
RobertFauts
September 30, 2026, at 2:50 pmvstupny bonus casino bratislava
get 5 euro free casino kasyno online z BLIK registracia free spin
hracie automaty kotuc 1e deposit casino bonus
ClarenceCah
September 30, 2026, at 3:09 pmApproaching this site through a casual link click and being surprised by what I found, and a look at granitecoveartisanbazaar extended the surprise, the rare experience of stumbling into excellent independent content rather than predictable mediocrity is one of the actual remaining pleasures of casual web browsing and this site provided it cleanly.
RichardHen
September 30, 2026, at 3:09 pmМежду морем и горами Сочи рынок лотов живой, но разрозненный: одно предложение у застройщика, другое у посредника, третье уже продано. Удобнее смотреть портфель целиком — так проще сравнить площадь, договор и район, не прыгая по площадкам.
[url=https://sochi-investment.ru/]Купить апартаменты в Сочи[/url] здесь можно не «вообще», а в конкретных комплексах: Курортный, Фазатрон, Горизонт, Альпийский квартал, Новая Альпика. Рядом квартиры, пентхаус, двухуровневые метры, коммерция, паркинг и кладовые — больше двухсот лотов в двенадцати объектах. Часть уже в собственности по ДКП, часть идёт по предварительному договору с понятным сроком выхода на основной.
Цены в открытом каталоге не висят: их присылают по заявке, чтобы цифры были свежими. Это спокойный формат для тех, кто хочет [url=https://sochi-investment.ru/]недвижимость в Сочи от инвестора[/url], а не случайный лот с доски объявлений.
Если задача — [url=https://sochi-investment.ru/]купить квартиру в Сочи[/url] для себя или под сдачу, логика одна: выбрать комплекс, запросить планировку и документы, посмотреть объект и только потом фиксировать сделку. Каталог обновляется, проданные позиции снимают — актуальный состав лучше уточнять в заявке.
[url=https://sochi-investment.ru/] [url=https://sochi-investment.ru/]купить апартаменты в сочи под ключ[/url]
[/url]
ClydeHok
September 30, 2026, at 3:28 pmCame in expecting another generic take and got something with actual character instead, and a look at timbercovegoodsstore carried that personality forward, finding a distinct voice on a saturated topic is impressive and worth pointing out when it happens because most sites end up sounding identical to their nearest competitors quickly.
Johnfal
September 30, 2026, at 3:29 pmNow appreciating the way the post avoided the temptation to be longer than necessary, and a look at microbrandmagnet continued that lean approach, content with the discipline to stop when finished rather than padding for length is content that respects both itself and its readers and this site has that disciplined editorial culture clearly throughout.
DannyGlike
September 30, 2026, at 3:31 pmhttps://omgphoto.ru/
Percyhes
September 30, 2026, at 3:40 pmGlad to have another data point on a question I am still thinking through, and a look at nightfallmeadowtraders added two more, content that acknowledges its place in a wider conversation rather than pretending to settle the question alone is intellectually honest in a way that I wish was more common across the open web.
MattMof
September 30, 2026, at 4:38 pmStarted forming counter examples to test the claims and the post handled most of them implicitly, and a look at hazelbrookartisanmarket continued that anticipatory style, writers who think two steps ahead of the critical reader save themselves from a lot of follow up work and this writer has clearly internalised that habit consistently.
Andresmix
September 30, 2026, at 4:53 pmblackjack online with friends free eldorado casino bonus nike online casino sk Automaty na peniaze hrat e casino sk hracie automaty lucky
Andresmix
September 30, 2026, at 5:06 pmgratorama 7 € registracia 5 free spin za registraci online automaty za penize Minimalny vklad 20 eur kasina bitslot casino login live casino roulette
RobertFauts
September 30, 2026, at 5:08 pmautomatic automaty zdarma
ruleta online hra ranking nowych kasyn online online poker slovensko licencie
casino bonus za registrГЎciu bez vkladu 2026 automaty bonus zdarma
AlbertNix
September 30, 2026, at 5:22 pmjbl moldova
RobertFauts
September 30, 2026, at 5:29 pmWhat are the 4 classic casino games
zet casino za registraciu bez vkladu bonus casino bonus bez vkladu wirwetten no deposit bonus
kajot free spin blackjack online app
Ibrahimrog
September 30, 2026, at 5:30 pmWorth every minute of the time spent reading, and a stop at windharbortrading extends that value across more pages, in a media environment where most content is engineered to waste attention this site stands out by treating reader time as something valuable rather than something to be exploited and stretched as far as possible.
RobertFauts
September 30, 2026, at 5:48 pmbonus casino bez vkladu
verde casino no deposit bonus kasyno online aplikacja mobilna deposit 1 euro
blackjack online players casino bonus 10
Andresmix
September 30, 2026, at 6:00 pmcasino free euro hazardné hry online zadarmo ako urobiť ruletu cien online Casino registracia bonus casino bonus bez vkladu 15€ smart live gaming casino
TheodoreHit
September 30, 2026, at 7:10 pmBetter signal to noise ratio than most places I check on this kind of topic, and a look at meadowstoneemporium kept that going, every paragraph here carries something worth reading rather than padding out the page to hit some arbitrary length target that search engines reward but readers ignore as soon as they notice it.
Andresmix
September 30, 2026, at 8:06 pmolybet casino sk grand mondial casino prihlГЎsenie hracie automaty sk Online hry kde jsou free spiny bez vkladu Which gambling site has the best welcome bonus
RobertFauts
September 30, 2026, at 8:06 pmautomaty hry zdarma joker 81
casino pri bratislave vyskusaj ruletu online zadarmo casino vstupnГ bonus bez vkladu
automaty zdarma hunters single deck blackjack online free
Andresmix
September 30, 2026, at 8:19 pm1win bonus casino use hracГ automaty zdarma turbo hraЕҐ online hry Casino hry za peniaze doxxbet hracie automaty automaty zdarma synoz
GeraldAcibe
September 30, 2026, at 8:28 pmGenerally I am cautious about recommending sites on first encounter but this one warrants the exception, and a look at iciclecovevendorhall reinforced the exception making, the rare site that justifies breaking my normal cautious approach is the rare site worth flagging early and this one has prompted exactly that early flagging response from me.
RobertFauts
September 30, 2026, at 8:28 pmnajlepЕЎie kasГnovГ© strГЎnky
automaty online bonus zdarma 888 casino code Kasyno bonus bez depozytu 2026 hry casino automaty zdarma
hra automaty online zadarmo hracie automaty zdarma multiplay 81
RobertFauts
September 30, 2026, at 8:46 pmruleta pre zabavu
casino registracia bonus tu najdes najlepsie online kasino free spiny zdarma za registraciu
blackjack online arkadium online kasina bonusy bez vkladu
Andresmix
September 30, 2026, at 9:13 pmcasino bonus bez poДЌГЎteДЌnГho vkladu live ruleta online poker hold em Automaty online blackjack online casino free online casino na slovensku
GlenVom
September 30, 2026, at 10:51 pmReading this between meetings turned out to be the most useful thing I did all afternoon, and a stop at uplandbrookcommercehub kept that productivity feeling going, content can sometimes outperform actual work in terms of what gets accomplished mentally and this site managed that today which is genuinely a high bar to clear consistently.
RobertFauts
September 30, 2026, at 11:05 pmnine casino no deposit bonus codes 2026
hraci automaty zdarma 4 valcove ranking nowych kasyn online automaty otoДЌky zdarma
yukon gold casino slovensko casino hry zadarmo
Andresmix
September 30, 2026, at 11:20 pmhraci automaty zdarma bez vkladu a registrace jak hrГЎt online automaty a vyhrГЎt online hracie automaty Free spiny fortuna dnes free spiny sobota hracie automaty za peniaze vstupny bonus
RobertFauts
September 30, 2026, at 11:27 pmlive casino demo
hrad automaty zdarma kasyno online z niskim depozytem galaxyno 5 €
star casino bonus za registrГЎciu bez vkladu 21 blackjack online
Andresmix
September 30, 2026, at 11:33 pmhazardne hry online automati zdarma free kajot casino bonus bez vkladu Kasino s vkladom od 5 eur nove online automaty hracГ automaty zdarma 81
RobertFauts
September 30, 2026, at 11:46 pmautomati hri hraj zdarma
blackjack online hra zadarmo najlepsze kasyno w ktore zagrasz na telefonie hracie automaty apolo hry
5 valcove automaty zdarma automaty online za zlotГЅch
JayKit
October 01, 2026, at 12:18 amUseful read, especially because the writer did not assume too much background from the reader, and a quick look at embermeadowboutique continued in the same way, a thoughtful site that meets people where they are which is something the modern web could use a lot more of for both casual and serious readers.
phrj777
October 01, 2026, at 12:22 amEverything is very professional here. I appreciate the transparency and the fair odds they offer to everyone. Great job phrj777
Andresmix
October 01, 2026, at 12:27 amonline casino platba sms stake live casino nove online kasina Zadarmo turbo hracie automaty 888 casino review beast mode slot
Damonshipt
October 01, 2026, at 12:51 amNow realising the post has been quietly doing important work in my mind for the past hour, and a stop at violetharborvault extended that quiet processing, content that continues to do work after I close the tab is content with afterlife in the mind and this site is producing those long lived effects at a meaningful rate.
BeauAdage
October 01, 2026, at 1:09 amDifferent in a good way from the cookie cutter content that fills most blogs covering this area, and a stop at quartzharborvendorhall kept showing me why, original thoughtful writing exists if you know where to look and this site has earned a place on my short list of those rare exceptions worth defending.
Juantip
October 01, 2026, at 1:23 amA particular kind of restraint shows up in the writing, and a look at jewelstoneemporium maintained the same restraint across pages, knowing what not to say is just as important as knowing what to say and this site has clearly developed strong instincts on both sides of that editorial line throughout pieces I have read.
AidanChoth
October 01, 2026, at 1:32 amTook the time to read the comments on this post too and they were also worth reading, and a stop at calmstonecollective suggested the community quality matches the content quality, when the conversation around a piece is as good as the piece itself you know you have found a real corner of the internet.
AlonzoBen
October 01, 2026, at 1:32 amNow appreciating the small but real way this post improved my afternoon, and a stop at jasperstonecourtyard extended that small improvement effect, content that produces measurable positive impact on the texture of a reading day is content with real value and this site is producing those small positive impacts at a sustainable rate apparently.
RobertFauts
October 01, 2026, at 2:06 ambonus casino online
bonus za vklad casino poznaj nowe kasyno online casino online vstupny bonus bez vkladu
casino s bonusom bez vkladu bonus za zaloЕѕenie ГєДЌtu 2026
RobertFauts
October 01, 2026, at 2:28 amcasino hry – hracie automaty
casino banovce nad bebravou top online casino na Slovensku hracie automaty zdarma pre zabavu
automaty zdarma online hry hry hracie automaty lion
AveryLap
October 01, 2026, at 2:33 amCame back to this twice now in the same week which is unusual for me, and a look at moonbrookdistrict suggested I will keep coming back, the kind of post that earns repeated visits rather than one and done reading is the gold standard for content quality and this site clearly hit that standard.
Andresmix
October 01, 2026, at 2:34 am500 casino bonus automati kajot zdarma roulette live casino Online automaty kajot gratowin 7 eur sazka online casino
RobertFauts
October 01, 2026, at 2:47 amautomaty zdarma demo hrГЎt
10 euro casino najnovsie online casina casino rewards 1€
stack em slot sk casino free spiny bez vkladu
Andresmix
October 01, 2026, at 2:47 amhracie automaty zadarmo piramida blackjack 21 online casino automaty online vklad za 2 Ruleta online za peniaze casino bonus 2026 bonusy za registrГЎciu
KeithCix
October 01, 2026, at 2:53 amFelt like the writer was speaking directly to someone with my level of curiosity, neither talking down nor showing off, and a stop at taxtrellis kept that comfortable matching going, finding writing that meets you where you are rather than asking you to climb up or stoop down feels great every time it happens.
Devantebok
October 01, 2026, at 3:05 amFelt the writer respected me as a reader without making a show of doing so, and a look at mirthlinnet continued that quiet respect, this is the kind of small but meaningful detail that separates the sites I bookmark from the ones I close after a single skim and never return to again no matter how interesting the headline.
Vincentorism
October 01, 2026, at 3:31 amReading this slowly and letting each paragraph land before moving on, and a stop at trailharbormerchantlane earned the same patient approach, content that rewards slow reading rather than speed is content with real density and the writers here are clearly producing work that benefits from the careful eye rather than the rushed scan.
Andresmix
October 01, 2026, at 3:42 amako zГskaЕҐ free spiny bez vkladu najlepsie zahranicne online casino admiral automati zdarma Tipy ako hrat automaty blackjack online poker hracie automaty online zdarma synot
Prestonzex
October 01, 2026, at 3:51 amA quiet piece that did not try to compete on volume, and a look at gildedwillowmarketplace maintained that selective approach, sites that publish less but better are increasingly rare in an environment that rewards volume and this one has clearly chosen quality cadence over quantity which is a brave editorial decision in current conditions.
KyrieSaulk
October 01, 2026, at 3:59 amReally like that the writer trusts the reader to follow simple logic without restating every previous point, and a stop at seacovevault kept that respect going, treating an audience as capable adults rather than as people who need constant hand holding makes a noticeable difference in the reading experience for me.
JeffreyIgnor
October 01, 2026, at 4:30 am[url=https://gerenciador-bb-financeiro.digital/]BB BRASIL ENTRAR[/url]
Para entrar nos serviços digitais do Banco do Brasil, é importante utilizar sempre os canais oficiais e conferir o endereço antes de informar dados de acesso.
Mariodiock
October 01, 2026, at 4:31 amWalked away with a clearer head than I had before reading this, and a quick visit to timberstoneoutpost only sharpened that, the writing has a way of cutting through the noise that surrounds most topics online which is something I will definitely remember the next time I am searching for an answer to anything.
BrianCef
October 01, 2026, at 4:56 amA thoughtful piece that did not strain to be thoughtful, and a look at meadowbrooktradingfoundry continued that effortless quality, when thinking shows up in writing without the writer drawing attention to it you know you are reading something genuinely considered rather than something performing the appearance of consideration which is also common online.
RobertFauts
October 01, 2026, at 5:06 amheat hracie automaty zdarma a bez registrace
casino bonus bez vkladu 2026 nove kasina online 2026 fortuna casino bonus vyber
hracie automaty admiral online online hracie automaty kajot
RobertFauts
October 01, 2026, at 5:27 amblackjack online live
automaty online zadarmo book of ra Najnowsze kasyna online gametwist kasino slots hracie automaty zdarma
stahuj hraci automaty zdarma sazka free spiny zdarma
BertVef
October 01, 2026, at 5:30 amWithout comparing too aggressively to other sources this one stands out for the right reasons, and a look at rainharborvault continued that distinctive quality, content that distinguishes itself through substance rather than style tricks is content with lasting differentiation and this site has clearly chosen substance based differentiation as its core editorial strategy.
rever_blKl
October 01, 2026, at 5:30 amBin seit etwa vier Monaten auf der Seite und sag mal was dazu, weil hier im Forum meistens nur die immer gleichen Namen auftauchen. Angefangen hat es uber einen Kollegen, nicht uber irgendeine Werbung. Die Lobby bei Bingoal ist ordentlich bestuckt — so um die 1800 Slots laut Filter, inklusive dem ganzen Pragmatic-Katalog, Play’n GO und auch Big Time Gaming.
Book of Dead ist mein Dauerbrenner, dazu manchmal Gates of Olympus wenn ich Geduld habe. Der Live-Bereich ist stark: es lauft uber Evolution mit richtige Croupiers, Crazy Time ist quasi immer belegt. Zu Stosszeiten war der Stream zweimal kurz weg — lag vielleicht auch an meinem WLAN.
Beim Willkommenspaket: es gibt einen 100%-Match bis 500 CHF mit Freispielen, Wagering 35x auf den Bonusbetrag was man vorher lesen sollte. Ein paar Freispiele ohne Einzahlung lauft ab und zu als Aktion, nicht jeden Monat. Welche Codes gerade laufen stehen jeweils bei [url=https://cloverclothing.lk/bingoal-app-mobile-nutzung-kompletter-leitfaden-fur-registrierung-bonus-und-sicherheit/]bingoal[/url] wenn dich das interessiert — steht nicht immer dasselbe drin.
Einzahlen ging schnell, so funf Minuten, Minimum lag bei 20 CHF, bei mir lauft Mastercard und Neteller. Krypto ist auch moglich, brauche ich nicht. Das Abheben bei Bingoal dauerten ein- bis zweimal rund 24 Stunden auf die E-Wallet, Karte deutlich langer. Der Dokumenten-Upload hat mich am meisten genervt — Pass und Wohnsitznachweis, das ist hier aber uberall so.
Am Handy lauft alles uber den Browser, was vollig reicht. Den Chat habe ich zweimal getestet: einmal sofort auf Deutsch, einmal erst nach zwanzig Minuten. Die Lizenzierung lauft nicht uber die ESBK, das muss man fur sich selbst einordnen — wer aus der Schweiz spielt sollte das im Hinterkopf bleiben. Mein Kontostand ist aktuell leicht im Plus, was nichts beweist. Habe ein Limit gesetzt und bei Bingoal geht das ohne Nachfragen durch, das schatze ich.
RobertFauts
October 01, 2026, at 5:46 amzahraj zadarmo na hracie automaty zdarma
playing slots in casino casino s minimalnym vkladom jedno euro hracie automaty zdarma multy 5
blackjack online practice automaty zdarma eu speed club
Andresmix
October 01, 2026, at 5:49 amuvitaci bonus bez vkladu casino pri bratislave casino doxxbet sk Najkvalitnejsie kasino na slovensku bonus za vklad poker blackjack online free for fun
Andresmix
October 01, 2026, at 6:02 amzdarma automaty sizzling hot casino 1 euro deposit bonus automaty zdarma slovensko Kasino s minimalnym vkladom 5 eur What online casino has the best deposit bonus gametwist casino slots hracie automaty zdarma
RayLex
October 01, 2026, at 6:21 amHighly recommend to anyone looking for a sensible take on this topic without the usual marketing nonsense, and a look at clovercovevendorhall kept that grounded approach going, sites that stay focused on serving readers rather than monetising every click are rare and this is clearly one of those rare ones I really appreciate finding.
lottoland_hvEr
October 01, 2026, at 6:55 amPelasin Lottolandilla joku aika sitten ja rehellisesti sanottuna en odottanu hirveesti mutta positiivisesti yllatti. Rekkarointi meni parissa minuutissa, perus jutut ja paasi pelaamaan. Minimitalletuksen tein kympilla Skrillin kautta ja oli sujuvaa. Taa on yks niista jutuista minka huomaa heti — hitaat maksut on dealbreaker.
Pelivalikoimasta pakko mainita et kylla loytyy kamaa. Lottoland tarjoo isoilta pelintekijoilta esim. NetEnt ja Microgaming, eli laatua loytyy. Tykkasin pyorittaa Book of Deadia paaasiassa ja ihan ok palautuksia. Slotteja on varmaan satoja plus poytapeleja myos. Yks miinus tosin — filtterit ei oo paras mahdollinen, joutuu valilla selaamaan.
Live-puolelta loytyy Evolutionin oikeita jakajia ja kokeilin Crazy Timea kaverin kaa. Striimi pelaa ihan sulavasti puhelimella, ja se on mulle tarkeeta. Tervetuliaisbonuksesta puhuttaessa — mulle tuli tervetuliaisen ja ilmaiskierroksia. Kierratys oli kolmisenkymmenta kertaa ja se on normaali. Lue pienella painettu kuitenkin etukateen.
Nostot Lottolandilta meni mulle ihan ok. E-lompakolla kesti pari tuntia ja korttimaksu otti pari paivaa. Ihan perus mut ok. Voit kattoo bonuskoodit ja edut suoraan [url=http://www.communicationsandelectronics.com]https://communicationsandelectronics.com[/url] ennen ku rekisteroidyt. Support hoituu chatilla ja mulle vastattiin kohtuuajassa ku kysyin jotain.
Mobiilipelaaminen onnistuu suoraan selaimessa eika tarvi ladata mitaan. Sivusto aukeaa hyvin ja slotit toimii ihan hyvin. Lisenssi on kunnossa eli silta osin ok. Ainoo pieni miinus on et sivusto ei oo taysin suomeks, mut englannilla parjaa. Kyl ma pelaan varmaan jatkossaki siella kunnes joku parempi tulee vastaan.
crazy_uaOr
October 01, 2026, at 6:55 amHo scoperto Crazy Time piu o meno un paio di mesi fa tramite un post su un forum e non vi nascondo che mi ha sorpreso. All’inizio ero scettico, come sempre con i siti nuovi, ma dopo averci giocato un po’ mi sono ricreduto. La registrazione e stata veloce, pochi minuti e avevo l’account pronto. Il deposito minimo non e alto, credo 10 euro, il che e comodo per testare senza rischiare troppo.
La libreria e piu ampia di quanto pensassi. Ci sono slot di Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, poi titoli di NetEnt e pure Play’n GO tipo Book of Dead. In totale parliamo di piu di mille titoli tra slot e tavoli. Il live casino e targata Evolution con croupier veri — lo show Crazy Time con la ruota mi prende parecchio, le moltiplicazioni a volte sono assurde. Ci perdo troppo tempo onestamente.
Il bonus iniziale su Crazy Time era un match del 100% fino a cinquecento euro piu cinquanta free spin su una slot selezionata. Il wagering sta a trentacinque volte il bonus, che non e il migliore in assoluto ma e gestibile rispetto ad altri siti. Ci sono anche bonus no deposit ogni tanto per i giocatori attivi, il che e un bel tocco. Vi consiglio di dare un’occhiata alle offerte attuali direttamente su [url=https://ctfkl-shop.com]crazy time download[/url] prima di registrarvi.
Lato pagamenti accettano le carte principali, Skrill e Neteller, e anche Bitcoin. I prelievi li ho ricevuti entro un giorno sull’e-wallet, il che non e male. Mi piace anche e che hanno l’app — ho fatto il crazy time download sul telefono e funziona bene. Non dovete cercare la crazy time apk su siti esterni dato che direttamente dal sito la scarichi in un attimo. Da mobile e comodissima.
L’assistenza su Crazy Time e raggiungibile in chat ventiquattr’ore su ventiquattro pure in italiano, il che per me conta parecchio. Il difetto se devo trovarne uno: la verifica documenti ci ha messo tipo tre giorni, piu del previsto. Ma dopo quello e filato tutto liscio. Hanno la licenza Curacao, non e AAMS ma e comunque qualcosa. Ci gioco volentieri ormai e il mio sito fisso.
crazy_grSr
October 01, 2026, at 6:56 amMi sono imbattuto in Crazy Time un paio di mesi fa tramite un amico e onestamente mi ha sorpreso. Pensavo fosse il solito sito visto che di piattaforme ce ne sono a pacchi, ma la varieta mi ha convinto. Ci trovi titoli di Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, poi diverse slot di NetEnt e qualcosa di Play’n GO come Book of Dead. Parliamo di circa 2500 giochi in tutto, quindi c’e da perdersi.
La parte live e quella che mi ha preso di piu. Tutto in mano a Evolution, con dealer dal vivo e si vede che e roba professionale. Ho passato ore su la ruota di Crazy Time e ci perdi le serate. Blackjack, baccarat e roulette non mancano, ma le ruote tipo Monopoly Live sono un altro livello. Un difetto che mi ha dato fastidio e che la sera nei weekend qualche tavolo lagga, niente di tragico pero.
Quando ti registri su Crazy Time offrono il 100% sul primo deposito fino a 500 euro piu 50 giri gratis su una slot selezionata. Devi rigirarlo 35 volte, che non e il piu basso. C’e chi offre meno, ma almeno i termini sono chiari. Il deposito minimo e di venti euro. Vi consiglio di guardare le promo aggiornate passando da [url=https://paperpaper.pl]crazy time[/url] per vedere cosa c’e.
I pagamenti non ho avuto problemi. Accettano Visa, Mastercard, Skrill, Neteller e pure crypto. Ho prelevato con Skrill ed e arrivato il giorno dopo. Veloce per i miei standard. Da mobile Crazy Time funziona bene dal browser senza scaricare nulla, si adatta bene allo schermo e non da problemi. Un no deposit bonus non l’ho trovato, peccato.
L’assistenza clienti fa il suo lavoro. Ho scritto in chat per un problema col bonus e mi hanno risposto in pochi minuti. In italiano tra l’altro. La licenza e Curacao, che non e il massimo, ma non ho mai avuto rogne. Per noi italiani funziona tutto senza VPN.
Andresmix
October 01, 2026, at 6:56 amfree spiny promo kod automaty online zdarma turbo hry vГЅhernГ automaty zdarma Cerstvo otvorene slovenske casino casino hry bez vkladu hracie automaty na stiahnutie zadarmo do mobilu
rolletto_dkKi
October 01, 2026, at 6:59 amSo I’ve been messing around on Rolletto for about a couple of months and figured I’d share how it’s been going. Stumbled on it through a mate since I was tired of my usual spots. Signed up took maybe a couple of minutes, pretty standard stuff, and I dropped twenty quid to test it — min deposit is ?20 which is fair enough.
First deposit bonus looked alright — they matched a hundred percent up to €500 plus 200 spins thrown in. Wagering’s at x35 and that could be worse honestly I’ve seen. Free spins were on Gates of Olympus if I remember right. Not gonna lie, spins were a bit dead but that bonus cash stretched things out nicely.
Game selection at Rolletto is genuinely massive. They’ve got stuff from Pragmatic Play, Play’n GO, and Evolution handles the live stuff. I mostly stick to Sweet Bonanza plus Big Time Gaming stuff like Extra Chilli. Must be a few thousand titles across the whole site. The live section is worth mentioning — the usual tables, plus I’ve wasted hours on Crazy Time and it’s a proper time sink. Proper live streams with actual dealers, picture quality is crisp even on mobile.
Getting money out has been where I was sceptical at first and so far it’s been fine. I withdraw to Neteller and the money came through in about 24 hours. There’s also Bitcoin and various e-wallets which is handy. I’d have a look at the current promotions over at [url=https://codeofgeeks.com]rolletto casino[/url] before you sign up. One gripe though — verification took like four days to clear which dragged on a bit.
Using it on mobile, Rolletto works well through Chrome — there’s no dedicated app which I actually prefer. Pages load quick enough and had a few goes on my commute without issues. Customer service is live chat 24/7 and they replied in under a minute when I asked about my withdrawal. It’s licensed out of Curacao — no UK licence so some people might care about that.
Honestly, there are niggles — KYC speed and the layout feels slightly busy. But there’s loads to play, payouts have been reliable for me, and the matched deposit gave me good value. Your mileage may vary but I’ll keep playing at Rolletto going forward.
revery_dkel
October 01, 2026, at 6:59 amBeen playing at Revery Play for like a couple of months and wanted to drop my thoughts here. I registered one evening out of boredom — min deposit is only ?10 which seemed fair, threw in ?50 to start and got a 100% welcome bonus up to 500 quid and 200 free spins. The rollover’s 40x which could be better honestly but I’ve seen way worse.
Game-wise is genuinely solid — there’s roughly 3000 titles from studios including Pragmatic Play, Microgaming and Big Time Gaming. I’ve been smashing Book of Dead mostly — hit a decent 400x on Sweet Bonanza the other night. The live dealer stuff is powered by Evolution — Crazy Time is great fun, proper dealers streaming in HD.
What that sold me on Revery Play is the cashout speed. I use Skrill and the payout landed in about 18 hours. You can also use Mastercard plus Neteller if that’s your thing. You can check out the current promotions on [url=https://la-barber.co.uk]reveryplay[/url] to see for yourself.
Tbh, not everything is amazing. Live chat at Revery Play took ages once — I waited a good while for live chat one evening. And the mobile version is decent enough but it feels a bit clunky compared to other sites I use. There’s no app as such, it’s browser-only on mobile.
Overall though, I’m still playing there so make of that what you will. Revery Play is regulated and I haven’t had any dodgy issues. Being UK-based this is a reasonable pick — just temper expectations on live chat wait times.
JulianZet
October 01, 2026, at 7:15 amStarted reading expecting to disagree and ended mostly nodding along, and a look at granitecovevendorhall continued the pattern, content that wins agreement through evidence and reasoning rather than rhetorical force is the kind that actually shifts minds and this site clearly knows how to do that across what I have read so far.
MarcusWiB
October 01, 2026, at 7:59 amMost of the time I bounce off similar pages within seconds, and a stop at rainmeadowcollectivemart held me longer than I would have predicted, the ability to convert a likely bouncing visitor into an engaged reader is a quality signal and this site has demonstrated that conversion ability across multiple visits where I expected to bounce.
Burtontes
October 01, 2026, at 8:04 amA piece that did not require external context to follow, and a look at ideasunlockgrowth maintained the same self contained quality, content that stands alone without forcing readers to chase prerequisites is more accessible and this site has clearly thought about how each piece can serve a fresh visitor rather than only existing members.
RobertFauts
October 01, 2026, at 8:06 amnove online casino v cr
hraci automat anglicky kasyno internetowe BLIK 4 euro deposit casino
no deposit casino slovakia 10f free no deposit
KimGof
October 01, 2026, at 8:12 amNow feeling confident that this site will continue producing work I will want to read, and a look at jewelstonecartemporium extended that confidence into the future, projecting forward from current quality to expected future quality is something I do for sites I genuinely follow and this one has earned that forward looking trust clearly today.
RobertFauts
October 01, 2026, at 8:28 amruleta online free
5 valcove automaty online zadarmo sizzling kasyno ktore wyplaca natychmiast online blackjack live dealer
blackjack online casino automaty hry zdarma online
Geraldclulk
October 01, 2026, at 8:43 amNow adjusting my mental model of how the topic fits into the broader landscape, and a look at gildedgroveartisanmart extended that adjustment, content that affects my structural understanding rather than just my factual knowledge is content with deeper impact and this site is providing those structural updates at a meaningful rate consistently across topics.
Jadontah
October 01, 2026, at 8:46 amNow feeling confident that this site will continue producing work I will want to read, and a look at motelmorel extended that confidence into the future, projecting forward from current quality to expected future quality is something I do for sites I genuinely follow and this one has earned that forward looking trust clearly today.
RobertFauts
October 01, 2026, at 8:47 amcasino 7 €
blackjack online with friends sposoby platnosci w kasynie online automaty stiahnut zdarma
live casino online slovakia nine casino recenze
Andresmix
October 01, 2026, at 9:04 amWhat slot has 99% RTP slot machine hracie automaty zdarma sizzling stiahnut free spiny zdarma jen za registrГЎciu novГ© casino Ruleta za peniaze synot hracГ automaty online nove slovenske online casino
Andresmix
October 01, 2026, at 9:18 amgold digger slot casino bonus bez poДЌiatoДЌnГ©ho vkladu lucky joker hracie automaty Free spin na hracich automatoch automaty s bonusom online hracie automaty sizzling hot deluxe zdarma
BeauJak
October 01, 2026, at 9:38 amA quiet piece that did not try to compete on volume, and a look at auroracoveartisanhouse maintained that selective approach, sites that publish less but better are increasingly rare in an environment that rewards volume and this one has clearly chosen quality cadence over quantity which is a brave editorial decision in current conditions.
Andresmix
October 01, 2026, at 10:12 amcasino bez vkladu free spiny online hry zadarmo ruleta scarab kingdom echtgeld Nove casino zo slovenska slovenske kasina online firebird spirit demo
Printercromi
October 01, 2026, at 10:38 amДоброго!
Материал по теме «bambu lab ams ht купить» помогает перейти в карточка товара и сравнить варианты с учётом задач, бюджета и требований к оборудованию. Каталог позволяет последовательно проверить характеристики, комплектацию, совместимость, назначение, условия покупки и доступные варианты поставки. Это помогает отсеять неподходящие варианты и выбрать решение под конкретный сценарий использования. Если характеристик недостаточно, можно запросить консультацию и подобрать совместимый вариант под конкретную модель и задачу.
Подробная информация на сайте https://sloytek.ru/filament/asa
3д принтер adventurer 5m, полилактид цена, пластик pla matte
толщина филамента для 3d принтера, [url=https://sloytek.ru/product/qidi-q2]quidi q2[/url], creality falcon 10w
Удачи!
MatthewEmera
October 01, 2026, at 10:46 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-v-odnostoronnem-poryadke/]консультация адвоката по расторжению брака в одностороннем порядке[/url] – обращайтесь, юрист подготовит заявление, соберет документы, представит ваши интересы в суде и поможет расторгнуть брак в одностороннем порядке. Получите бесплатную консультацию и узнайте, какой порядок подходит именно в вашей ситуации.
RobertFauts
October 01, 2026, at 11:07 amcasino 15 euro gratis
cz casino bonus za registraciu kasyno internetowe z pewna wyplata live casino online sk
vyherne automaty zadarmo hracie automaty na slovensku
RobertFauts
October 01, 2026, at 11:29 amcasino na paysafecard
ruleta online na žrebovanie Kasyno bonus bez depozytu 2026 free 7 € registrace
welcome fortune slot top online casino slovakia
KimDeeta
October 01, 2026, at 11:43 amAppreciate that you did not pad this with fluff to hit a word count, the post says what it needs to say and stops, and a look at mapleharborgoodsplace did the same, brevity here feels intentional not lazy which is a distinction many writers miss completely sometimes when they are working under deadlines.
RichardScate
October 01, 2026, at 11:48 ambonus za zaloЕѕenГ ГєДЌtu bez vkladu casino zagraj w gry kasynowe w Polsce online poker na slovensku
lottoland_npEr
October 01, 2026, at 11:50 amOon pelannu Lottolandilla pari kuukautta sitten ja pakko sanoo et alkuun oli skeptinen mutta ihan hyvin lahti kayntiin. Tilin luonti ei kestany kauaa, taytti vaan perustiedot ja paasi pelaamaan. Minimitalletuksen sai tehtya 10 eurolla Visan kautta ja rahat naky heti tililla. Taa on yks niista jutuista mika ratkasee mulle aika paljon — jos talletus tokkii niin en jaksa.
Pelivalikoimasta voin sanoo et kylla loytyy kamaa. Lottoland tarjoo isoilta tuottajilta niinku Play’n GO ja Microgaming, joten tutut nimikkeet on paikalla. Ma pelasin Gates of Olympusta paaasiassa ja muutama kiva voitto iski. Slotteja on varmaan satoja plus blackjackia ja rulettia kans. Yks miinus tosin — hakutoiminto ei oo paras mahdollinen, loytaa kylla mut vaatii klikkailua.
Livepeleista loytyy ihan kunnon oikeita jakajia ja kokeilin Crazy Timea ja blackjackia kaverin kaa. Pyorii hyvin puhelimella, ja se on mulle tarkeeta. Bonuksista sen verran — nappasin matchbonuksen ja paalle viela ilmaiskierroksia. Kierratysvaatimus oli jotain 30x mika on ihan ok taso. Ehdot kannattaa vilkasta kuitenkin ennen ku ottaa bonuksen.
Rahojen kotiuttaminen Lottolandilta on menny mulle kohtuullisesti. Skrillilla meni noin paiva ja pankkisiirto kesti vahan pidempaan. Ihan perus mutta ei valittamista. Kannattaa vilkasta bonuskoodit ja edut katevasti [url=https://abstaxrez.com]read more[/url] jos kiinnostaa. Support toimii chatin kautta ja mulle vastattiin ihan nopeesti bonusasiassa.
Puhelimella toimii selaimella ja se riittaa mulle. Saitti latautuu nopeesti eika patkimista oo ihan hyvin. Lisenssi on kunnossa eli silta osin ok. Toinen mika vahan hairitsi et sivusto ei oo taysin suomeks, ei se iso juttu oo. Kyl ma aion jatkaa Lottolandissa ainaki toistaseks.
rolletto_hcKi
October 01, 2026, at 12:03 pmSo I’ve been playing at Rolletto for roughly six weeks or so and wanted to share how it’s been going. Found it after googling around for somewhere new since I was tired of the same old sites. Signed up took about two minutes, just the usual details, and I dropped ?20 as a first deposit — min deposit is ?20 which is fair enough.
Their sign-up offer caught my eye — I got a match of a hundred percent up to €500 with 200 spins thrown in. The rollover sits at x35 and that is about average compared to some places. Spins landed on Sweet Bonanza from what I recall. Not gonna lie, spins were a bit dead but the matched funds kept me going.
Game selection at Rolletto is honestly bigger than I expected. They’ve got titles by Pragmatic Play, NetEnt, and Evolution handles the live stuff. I’ve been hammering Book of Dead and Big Time Gaming stuff like Bonanza. Must be 3000-odd games in total. Live dealers are worth mentioning — roulette, blackjack, plus I’ve wasted hours on Crazy Time which is way too addictive. All Evolution-run, quality’s crisp even on mobile.
Cashing out is the bit I was most worried about and actually can’t moan. Tried Skrill mostly and the money came through in roughly a day. You can also use crypto like BTC and other options which is handy. You can check out the current promotions over at [url=https://a1freightmatching.com]Rolletto[/url] if you’re curious. The thing that bugs me — KYC took nearly a week to clear which was frustrating.
Using it on mobile, Rolletto loads nicely in Chrome — there’s no dedicated app but the mobile site is smooth. Everything loads fast and had a few goes on my commute and it ran smooth. Their help team is always on via live chat and I got an answer in a couple of minutes when I had a bonus question. The site is Curacao licensed — worth noting it’s not UK-regulated and that’s a thing to be aware of.
Overall, it’s not perfect — that slow verification plus the site design is a bit cleaner. But there’s loads to play, payouts have been reliable for me, and the matched deposit gave me good value. Your mileage may vary but I’m keeping Rolletto for a while yet.
crazy_esSr
October 01, 2026, at 12:08 pmHo scoperto Crazy Time un paio di mesi fa tramite un amico e onestamente mi ha fatto una buona impressione. Non mi aspettavo granche visto che di piattaforme ce ne sono a pacchi, ma la varieta mi ha convinto. Ci trovi roba di Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, poi parecchie slot di NetEnt piu roba Play’n GO come Book of Dead. Ci saranno oltre duemila giochi in tutto, quindi c’e da perdersi.
La parte live mi ha convinto parecchio. I tavoli sono gestiti da Evolution, con croupier veri e si vede che e roba professionale. Ho passato ore su il game show crazytime e ci perdi le serate. Roulette e blackjack non mancano, ma i game show ti tengono incollato allo schermo. Un difetto che noto e che la sera nei weekend qualche tavolo lagga, niente di tragico pero.
Per il bonus di benvenuto su Crazy Time offrono un 100% fino a 500€ con in aggiunta 50 free spin sulla slot del momento. Il wagering e 35x, nella media direi. C’e chi offre meno, ma almeno i termini sono chiari. Il deposito minimo e di 20€. Se vi interessa date un occhio a le offerte attuali direttamente su [url=http://theater-radix.de/]https://theater-radix.de[/url] prima di registrarvi.
Per versare e prelevare non ho avuto problemi. Accettano Visa, Mastercard, Skrill, Neteller e pure crypto. La mia prima cashout e stata con Skrill ed e arrivato il giorno dopo. Veloce per i miei standard. Sul telefono Crazy Time funziona bene dal browser senza scaricare nulla, il sito e responsive e non da problemi. Nessun bonus no deposit purtroppo, sarebbe stato un bel plus.
L’assistenza clienti fa il suo lavoro. Ho scritto in chat per chiedere info sul wagering e mi hanno risposto in pochi minuti. E rispondono in italiano. La licenza e Curacao, che non e il massimo, pero finora zero problemi. Per noi italiani non ho lamentele serie.
crazy_rqOr
October 01, 2026, at 12:13 pmHo scoperto Crazy Time tipo due mesi fa cercando qualcosa di diverso dal solito e non vi nascondo che mi ha sorpreso. Ero un po’ diffidente, come sempre con i siti nuovi, ma dopo averci giocato un po’ ho cambiato idea. La registrazione e stata veloce, neanche dieci minuti e avevo l’account pronto. Il minimo per iniziare non e alto, mi pare 10 euro, il che e comodo per testare senza rischiare troppo.
La libreria non e male per niente. Hanno slot di Pragmatic Play tipo Gates of Olympus che e una bomba, poi titoli di NetEnt e qualcosa di Play’n GO tipo Book of Dead. Complessivamente ci saranno oltre mille giochi tra slot e tavoli. Il live casino e targata Evolution con dealer in carne e ossa — il game show di Crazy Time e il mio preferito, le moltiplicazioni a volte sono assurde. Ci perdo troppo tempo onestamente.
Il bonus iniziale su Crazy Time era un match del 100% fino a cinquecento euro piu cinquanta free spin su Sweet Bonanza. Il wagering sta a 35x, non e poco ma e nella media rispetto ad altri siti. Ho notato bonus no deposit ogni tanto per chi gioca gia, cosa che apprezzo. Vi consiglio di controllare le promo aggiornate direttamente su [url=https://codeofgeeks.com]Crazy Time[/url] per farvi un’idea.
Per i pagamenti accettano le carte principali, Skrill e Neteller, e anche Bitcoin. I prelievi li ho ricevuti entro un giorno con Skrill, che e decente. Mi piace anche e che hanno l’app — l’ho scaricata sul telefono e gira liscia. Non serve cercare la crazy time apk da siti strani perche dal sito ufficiale la scarichi in un attimo. Sul cellulare ci gioco anche in pausa pranzo.
L’assistenza su Crazy Time e raggiungibile via live chat h24 pure in italiano, cosa non scontata. Una cosa che mi ha scocciato: la verifica documenti ha richiesto tipo tre giorni, piu del previsto. Ma dopo quello e filato tutto liscio. Hanno la licenza Curacao, non e AAMS ma almeno c’e. Sono soddisfatto e non ho motivo di cambiare.
Alfredwes
October 01, 2026, at 12:20 pmcasino bonusy za registraciu 5 € casino bonus What games do you find in a casino Automaty na peniaze hrat casino online ruleta coupon bovegas casino
PhillipCap
October 01, 2026, at 12:29 pmA piece that was confident enough to leave some questions open rather than forcing closure, and a look at acornharborvault continued that intellectual honesty, content that admits the limits of its scope is more trustworthy than content that pretends to total understanding and this site has the right calibration on certainty consistently.
Alfredwes
October 01, 2026, at 12:33 pmnove casino bez vkladu automaty zdarma hry kajot hracie automaty vranov nad toplou Kasinove hry za peniaze new casino free signup bonus hrat zadarmo hracie automaty
AbelAccor
October 01, 2026, at 12:33 pmA piece that did not require external context to follow, and a look at harborvalleyboutiquehub maintained the same self contained quality, content that stands alone without forcing readers to chase prerequisites is more accessible and this site has clearly thought about how each piece can serve a fresh visitor rather than only existing members.
lottoland_inEr
October 01, 2026, at 12:41 pmPelasin Lottolandilla pari kuukautta sitten ja taytyy myontaa etta en odottanu hirveesti mutta positiivisesti yllatti. Tilin luonti meni parissa minuutissa, taytti vaan perustiedot ja paasi pelaamaan. Minimitalletuksen sai tehtya kympilla Mastercardilla eika siina menny ku hetki. Se on semmonen asia minka huomaa heti — hitaat maksut on dealbreaker.
Pelivalikoimasta pakko mainita et sita riittaa. Lottoland vetaa sisaan peleja isoilta pelintekijoilta kuten NetEnt ja Evolution, joten tutut nimikkeet on paikalla. Tykkasin pyorittaa Gates of Olympusta jonku verran ja voittoki tuli pari kertaa. Slotteja on varmaan satoja ja sit on poytapeleja myos. Yks miinus tosin — pelien etsinta vois olla parempi, valilla menee aikaa ettiessa.
Live-puolelta loytyy Evolutionin livepoytia ja pelattiin Lightning Roulettea yksin illalla. Toimii hyvin puhelimella, eika tarvi erillista appia. Tervetuliaisbonuksesta puhuttaessa — ma sain tervetuliaisen ja ilmaiskierroksia. Kierratys oli about 35-kertainen ja se on ok taso. Lue pienella painettu kuitenkin etukateen.
Nostot Lottolandista on menny mulle ihan ok. Skrillilla meni noin paiva ja korttimaksu kesti vahan pidempaan. Ihan perus mut ok. Loydat bonuskoodit ja edut suoraan [url=https://bikesbros.com]lottoland casino[/url] jos kiinnostaa. Support toimii chatin kautta ja oon saanu ihan nopeesti ku oli ongelma.
Mobiilipelaaminen toimii selaimella ilman appin asennusta. Saitti latautuu hyvin ja pelit pyorii ihan hyvin. Lottolandilla on EU-lisenssi mika antaa tiettya turvaa. Ainoo mika vahan hairitsi navigointi vois olla selkeempi, mut kylla silla parjaa. Kyl ma aion jatkaa siella viela jonku aikaa.
revery_bcel
October 01, 2026, at 12:47 pmBeen messing around on Revery Play for like a couple of months and thought I’d share my take here. Signed up one evening out of boredom — minimum deposit was just ten quid which wasn’t bad, deposited fifty quid and got a matched deposit bonus up to ?500 and 150 free spins on registration. Playthrough sits at 35x and is pretty standard but I’ve seen way worse.
Game selection is genuinely solid — there’s roughly 3000 slots and table games from studios including Pragmatic Play, Microgaming and Big Time Gaming. I’ve been smashing Gates of Olympus a lot — pulled a nice win on Sweet Bonanza the other night. The live dealer stuff runs on Evolution — Lightning Roulette is always packed, proper dealers streaming in HD.
The bit I like at Revery Play is the cashout speed. My go-to is my Visa and my withdrawal hit my account in less than a day. You can also use Bitcoin and Neteller if that’s your thing. I’d browse what’s available on [url=https://4101laclede.com]revery play[/url] before you sign up.
Now, it’s not all perfect. Customer support at Revery Play took ages once — was sitting there a good while for live chat one evening. The mobile version runs okay though some menus are fiddly versus some competitors. No dedicated app either, you just use the mobile browser.
Having said all that, it hasn’t put me off so make of that what you will. They’re regulated and I haven’t had any dodgy issues. If you’re in the UK it’s a solid shout — I’d just don’t expect live chat wait times.
rolletto_oeKi
October 01, 2026, at 12:57 pmSo I’ve been playing at Rolletto for about six weeks or so and wanted to share my thoughts. Stumbled on it after googling around for somewhere new after I got fed up with where I normally play. Registration took maybe a couple of minutes, nothing weird asked, and I deposited twenty quid to test it — min deposit is ?20 which is fair enough.
The welcome bonus looked alright — I got a match of a hundred percent up to €500 with 200 spins thrown in. The rollover sits at x35 and that could be worse honestly I’ve seen. Spins landed on Sweet Bonanza I think. I’ll be honest, the spins didn’t pay great but that bonus cash stretched things out nicely.
The lobby on Rolletto is genuinely pretty stacked. There’s slots from Pragmatic Play, NetEnt, and Evolution handles the live stuff. My go-to slots have been Sweet Bonanza plus Big Time Gaming stuff like Bonanza. Looks like there’s 3000-odd games when you count everything. The live section is worth mentioning — the usual tables, and I got sucked into Crazy Time which is way too addictive. Real croupiers streaming, stream is sharp on my laptop.
Getting money out has been what I really wanted to test and so far it’s been fine. I withdraw to Skrill mostly and it took under two days. You can also use crypto like BTC and a bunch of e-wallets for flexibility. You can have a look at the current promotions on [url=https://haulfanguesthouse.co.uk]Rolletto[/url] before you sign up. My one annoyance — they took ages to clear which was frustrating.
Mobile-wise, Rolletto works well through Safari — they don’t have an app but the mobile site is smooth. Pages load quick enough and I’ve done sessions on the bus and it ran smooth. Their help team is available round the clock via chat and they replied in like thirty seconds when I had a bonus question. They’re operating under a Curacao licence — no UK licence so make of that what you will.
Overall, it’s not perfect — KYC speed and the site design is a bit cleaner. But there’s loads to play, payouts have been reliable for me, and that welcome offer gave me plenty of play time. Might not suit everyone but I’m keeping Rolletto for now.
crazy_lbSr
October 01, 2026, at 1:00 pmSono finito su Crazy Time un paio di mesi fa perche un collega me ne ha parlato e non vi nascondo che mi ha fatto una buona impressione. Pensavo fosse il solito sito perche ne ho provati tanti, ma il catalogo giochi e enorme. Ci trovi titoli di Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, e anche parecchie slot di NetEnt e roba Play’n GO come Book of Dead. Parliamo di oltre duemila giochi in tutto, insomma non ti annoi di certo.
Il live casino mi ha convinto parecchio. I tavoli sono gestiti da Evolution, con croupier veri e si vede che e roba professionale. Ho passato ore su la ruota di Crazy Time e ci perdi le serate. Blackjack, baccarat e roulette ci sono ovviamente, ma le ruote tipo Monopoly Live sono un altro livello. L’unica cosa che noto e che la sera nei weekend qualche tavolo lagga, niente di tragico pero.
Per il bonus di benvenuto su Crazy Time offrono un 100% fino a 500€ piu 50 free spin su una slot selezionata. Il wagering e 35x, che non e il piu basso. C’e chi offre meno, pero almeno non ti fregano con clausole nascoste. Per iniziare bastano venti euro. Potete controllare le promo aggiornate direttamente su [url=http://eat-n-fit.com/]https://eat-n-fit.com[/url] prima di registrarvi.
I pagamenti non ho avuto problemi. Accettano Visa, Mastercard, Skrill, Neteller e anche Bitcoin. La mia prima cashout e stata tramite Neteller ed e arrivato il giorno dopo. Veloce per i miei standard. Sul telefono Crazy Time si carica velocemente anche senza app dedicata, il sito e responsive e non da problemi. Un no deposit bonus non l’ho trovato, sarebbe stato un bel plus.
L’assistenza clienti e decente. Ho scritto in chat per chiedere info sul wagering e in un quarto d’ora avevo risposta. E rispondono in italiano. La licenza e Curacao, non e il top come garanzia, ma i pagamenti arrivano e tanto basta. Per noi italiani mi trovo bene.
crazy_unOr
October 01, 2026, at 1:10 pmSono finito su Crazy Time piu o meno qualche settimana fa tramite un post su un forum e onestamente non me l’aspettavo. Ero un po’ diffidente, come sempre con i siti nuovi, ma dopo averci giocato un po’ mi sono ricreduto. Iscriversi e stato rapido, neanche dieci minuti e ero dentro. Il minimo per iniziare e abbastanza basso, credo una decina di euro, quindi niente di assurdo per farsi un’idea.
Il catalogo e piu ampia di quanto pensassi. Ci sono slot di Pragmatic Play tipo Gates of Olympus che e una bomba, e anche titoli di NetEnt e qualcosa di Play’n GO come Book of Dead. In totale ci saranno oltre mille giochi tra slot e tavoli. Il live casino e gestita da Evolution con croupier veri — il game show di Crazy Time e il mio preferito, quando becca il bonus giusto esplode tutto. Ci perdo le ore li sopra.
Il bonus iniziale che ho preso su Crazy Time era un match del 100% fino a cinquecento euro con in aggiunta 50 giri gratis su Sweet Bonanza. Il wagering sta a trentacinque volte il bonus, che non e il migliore in assoluto ma e gestibile per il settore. Ci sono anche offerte senza deposito di tanto in tanto per i giocatori attivi, cosa che apprezzo. Potete dare un’occhiata alle offerte attuali su [url=https://capitalfoundation.ca]crazy time apk[/url] se vi interessa.
Lato pagamenti accettano le carte principali, e-wallet tipo Skrill e Neteller, e anche Bitcoin. Le mie withdrawal mi sono arrivati in circa 24 ore con Skrill, che e decente. Mi piace anche e che hanno l’app — l’ho scaricata sullo smartphone e gira liscia. Non dovete cercare l’apk da siti strani dato che direttamente dal sito si trova subito. Ormai gioco piu da mobile.
L’assistenza su Crazy Time risponde in chat h24 pure in italiano, il che per me conta parecchio. Una cosa che mi ha scocciato: la verifica documenti ha richiesto tipo tre giorni, piu del previsto. Pero una volta fatto zero problemi. Hanno la licenza da Curacao, che non e l’ADM italiana ma almeno c’e. Sono soddisfatto ormai e il mio sito fisso.
lottoland_bdEr
October 01, 2026, at 1:18 pmPelasin Lottolandilla pari kuukautta sitten ja taytyy myontaa etta alkuun oli skeptinen mutta ihan hyvin lahti kayntiin. Tilin luonti meni parissa minuutissa, nimi ja sahkoposti ja pari vahvistusta ja oli valmis. Ekan talletuksen tein 10 eurolla Skrillin kautta eika siina menny ku hetki. Se on semmonen asia minka huomaa heti — hitaat maksut on dealbreaker.
Peleista pakko mainita et kylla loytyy kamaa. Lottoland vetaa sisaan peleja tunnetuilta providereilta kuten Play’n GO ja Evolution, eli laatua loytyy. Tykkasin pyorittaa Book of Deadia paaasiassa ja voittoki tuli pari kertaa. Kolikkopeleja on ainakin pari sataa ja sit on blackjackia ja rulettia tietenkin. Pieni miinus — pelien etsinta ei oo paras mahdollinen, loytaa kylla mut vaatii klikkailua.
Livepeleista loytyy ihan kunnon livepoytia ja pelattiin Lightning Roulettea viikonloppuna. Pyorii ihan sulavasti myos kannykalla, ja se on mulle tarkeeta. Bonuksista puhuttaessa — ma sain tervetuliaisen plus freespinneja. Kierratysvaatimus oli about 35-kertainen ja se on standardi. Kannattaa lukee ehdot kuitenkin ennen ku ottaa bonuksen.
Rahojen kotiuttaminen Lottolandilta meni mulle suht nopeesti. E-lompakolla meni noin paiva ja pankkisiirto meni ehka kolme paivaa. Ei mitaan kauheen erikoista mutta ei valittamista. Loydat lisatietoa katevasti [url=https://darrelchaney.com]Lottoland[/url] niin naat ite. Support vastaa livechatissa ja mulle vastattiin ihan nopeesti ku kysyin jotain.
Puhelimella toimii selaimella ja se riittaa mulle. Saitti latautuu hyvin ja slotit toimii moitteetta. Lisenssi on kunnossa eli silta osin ok. Ainoo mika vahan hairitsi navigointi vois olla selkeempi, ei se iso juttu oo. Kyl ma aion jatkaa Lottolandissa kunnes joku parempi tulee vastaan.
Alfredwes
October 01, 2026, at 1:28 pmautomaty online hry automaty zdarma hrat free spiny za aplikaciu Vitajuci bonus v kasine always hot deluxe beast mode slot
crazy_mcSr
October 01, 2026, at 1:36 pmHo scoperto Crazy Time un paio di mesi fa cercando qualcosa di nuovo dove giocare e onestamente mi ha fatto una buona impressione. Non mi aspettavo granche visto che di piattaforme ce ne sono a pacchi, ma hanno veramente tanta roba. Hanno roba di Pragmatic Play come Sweet Bonanza e Gates of Olympus, e anche diverse slot di NetEnt piu roba Play’n GO tipo Book of Dead. Ci saranno piu di 2000 giochi in tutto, quindi non ti annoi di certo.
La parte live e quella che mi ha preso di piu. I tavoli sono gestiti da Evolution, con croupier veri e si vede che e roba professionale. Mi sono fissato con la ruota di Crazy Time ed e una droga. Roulette e blackjack ci sono ovviamente, ma le ruote tipo Monopoly Live ti tengono incollato allo schermo. Un difetto che mi ha dato fastidio e che la sera nei weekend qualche tavolo lagga, niente di tragico pero.
Per il bonus di benvenuto su Crazy Time offrono un 100% fino a 500€ piu 50 giri gratis sulla slot del momento. Devi rigirarlo 35 volte, nella media direi. Ho visto posti con 25x, ma almeno non ti fregano con clausole nascoste. Il deposito minimo e di venti euro. Vi consiglio di guardare le promo aggiornate direttamente su [url=https://aceecommservices.com]crazy time[/url] cosi vi fate un’idea.
I pagamenti funzionano senza intoppi. Accettano Visa, Mastercard, Skrill, Neteller e anche Bitcoin. Ho prelevato tramite Neteller e in 24 ore avevo i soldi. Meglio di certi posti dove aspetti una settimana. Sul telefono Crazy Time funziona bene anche senza app dedicata, il sito e responsive e non ho avuto crash. Nessun bonus no deposit purtroppo, peccato.
L’assistenza clienti fa il suo lavoro. Li ho contattati per un problema col bonus e in un quarto d’ora avevo risposta. Parlano italiano il che aiuta. Hanno licenza di Curacao, lo so che non e MGA, ma non ho mai avuto rogne. Per noi italiani funziona tutto senza VPN.
rolletto_voKi
October 01, 2026, at 1:36 pmSo I’ve been messing around on Rolletto for like three months now and wanted to share what I think. Stumbled on it after googling around for somewhere new since I was tired of where I normally play. Signed up took maybe under five minutes, just the usual details, and I deposited ?20 as a first deposit — twenty’s the lowest you can go which isn’t bad.
Their sign-up offer was decent actually — it was 100% up to €500 with a couple hundred free spins. The rollover sits at 35x which is about average for this kind of offer. Spins landed on Big Bass Bonanza if I remember right. Not gonna lie, the spins didn’t pay great but the matched funds gave me a solid session.
The lobby on Rolletto is genuinely bigger than I expected. There’s titles by Pragmatic Play, NetEnt, Evolution for live. I’ve been hammering Gates of Olympus and Big Time Gaming stuff like White Rabbit. Looks like there’s 3000-odd games in total. Live casino’s worth mentioning — roulette, blackjack, and I got sucked into Crazy Time and it’s way too addictive. Proper live streams with actual dealers, quality’s crisp even on mobile.
Cashing out is where I was sceptical at first and actually can’t moan. I’ve used my Visa and the money came through in under two days. They also do Bitcoin and a bunch of e-wallets if that’s your thing. You can check out the current promotions over at [url=https://webalchemy.uk]read more[/url] to see for yourself. My one annoyance — they took nearly a week to approve and that dragged on a bit.
On my phone, Rolletto runs fine in Chrome — no app needed and honestly the browser version is fine. It’s quick enough and I’ve done sessions on my commute no problems. Customer service is live chat 24/7 and they replied in like thirty seconds when I had a bonus question. They’re Curacao licensed — no UK licence so some people might care about that.
Overall, it’s not flawless — that slow verification and navigation could be busy. But there’s loads to play, withdrawals have landed every time, and the bonus gave me good value. Not for everyone maybe but I’ll be sticking with Rolletto for now.
revery_qmel
October 01, 2026, at 1:45 pmBeen playing at Revery Play for roughly a couple of months and thought I’d give my two cents on this. I registered on a whim — minimum deposit was ?10 which suited me fine, deposited ?50 to start and they matched with a matched deposit bonus up to ?500 and 150 free spins on registration. Playthrough sits at 35x which could be better honestly but manageable if you stick to slots.
Game selection is pretty stacked — Revery Play has somewhere around 3000 titles from studios including Pragmatic Play, Microgaming and Betsoft. Been grinding Book of Dead mainly — hit a decent 400x on Gates last week actually. Live casino section is powered by Evolution — the game shows are addictive honestly, proper dealers streaming in HD.
One thing I appreciate about Revery Play is withdrawal times. Paying with Skrill and my withdrawal came through within less than a day. They also take crypto and various e-wallets which is handy. You can have a look at what’s available over at [url=https://dgsfcfiji.com]reveryplay[/url] to see for yourself.
That said, not everything is amazing. Customer support at Revery Play took ages once — I waited nearly 20 minutes for live chat one evening. And the site on my phone is decent enough but navigation could be smoother versus bigger brands. No dedicated app either, it’s browser-only on mobile.
Still, I keep coming back so make of that what you will. Revery Play is licensed and I haven’t had any dodgy issues. If you’re in the UK it’s a decent option — I’d just be patient with the support response times.
crazy_ubOr
October 01, 2026, at 1:51 pmSono finito su Crazy Time circa due mesi fa tramite un post su un forum e devo dire che mi ha sorpreso. Ero un po’ diffidente, come sempre con i siti nuovi, ma dopo qualche sessione ho cambiato idea. Iscriversi e stato rapido, pochi minuti e ero dentro. Il minimo per iniziare e abbastanza basso, credo 10 euro, il che e comodo per farsi un’idea.
La selezione di giochi e piu ampia di quanto pensassi. Hanno slot di Pragmatic Play tipo Sweet Bonanza e Gates of Olympus, poi roba di NetEnt e qualcosa di Play’n GO tipo Book of Dead. In totale parliamo di piu di mille titoli se conti tutto. Il live casino e gestita da Evolution con croupier veri — il game show di Crazy Time mi prende parecchio, quando becca il bonus giusto esplode tutto. Ci perdo piu tempo del dovuto.
Il bonus iniziale su Crazy Time e stato un match del 100% fino a cinquecento euro con in aggiunta cinquanta free spin su una slot selezionata. Il requisito di scommessa e di 35x, non e poco ma e nella media per il settore. Ho notato offerte senza deposito di tanto in tanto per chi gioca gia, il che e un bel tocco. Vi consiglio di dare un’occhiata alle offerte attuali su [url=sportlife360.com]https://sportlife360.com[/url] prima di registrarvi.
Per i pagamenti si puo usare le carte principali, e-wallet tipo Skrill e Neteller, e anche Bitcoin. Le mie withdrawal mi sono arrivati entro un giorno sull’e-wallet, il che non e male. Mi piace anche e che hanno l’app — ho fatto il crazy time download sul telefono e funziona bene. Non serve cercare la crazy time apk su siti esterni perche dal sito ufficiale la scarichi in un attimo. Ormai gioco piu da mobile.
L’assistenza su Crazy Time e raggiungibile in chat ventiquattr’ore su ventiquattro pure in italiano, il che per me conta parecchio. L’unica nota negativa: la verifica documenti ha richiesto tipo tre giorni, un po’ troppo. Ma dopo quello zero problemi. Hanno la licenza da Curacao, non e AAMS ma e comunque qualcosa. Ci gioco volentieri e continuo a tornare.
Hectornum
October 01, 2026, at 1:57 pmПрописка в Москве и временная регистрация решают разные задачи. Постоянная регистрация связана с долгосрочным проживанием, а временная помогает оформить пребывание на ограниченный период без изменения основного адреса – регистрация в москве цена
RichardScate
October 01, 2026, at 2:07 pmautomaty hry zdarma 27 kasyno depozyt 20 zl hry automaty kajot online
revery_btel
October 01, 2026, at 2:24 pmBeen messing around on Revery Play for roughly six weeks or so and thought I’d share my take on this. I registered on a whim — minimum deposit was just ten quid which wasn’t bad, threw in ?30 to test it and got a matched deposit bonus up to ?500 and 150 free spins on registration. Wagering is 40x which could be better honestly but not terrible either.
Game-wise actually surprised me — they’ve got roughly 3000 slots and table games from providers like Pragmatic Play, NetEnt and Betsoft. Been grinding Gates of Olympus mostly — had a solid session on Book of Dead recently. The live dealer stuff runs on Evolution — Lightning Roulette is always packed, proper dealers streaming in HD.
One thing I like at Revery Play is withdrawal times. My go-to is Neteller and last cashout landed in less than a day. You can also use Bitcoin and Neteller which is handy. I’d browse what’s available on [url=https://4101laclede.com]revery play[/url] before you sign up.
Now, there are a couple of gripes. Customer support at Revery Play took ages once — was sitting there like 15 minutes on chat the other day. The site on my phone is decent enough but navigation could be smoother compared to other sites I use. No standalone app, you just use the mobile browser.
Overall though, it hasn’t put me off so make of that what you will. They’re properly licensed and feels trustworthy enough. For UK players this is a reasonable pick — only temper expectations on their customer service speed.
Rubenlow
October 01, 2026, at 2:24 pmЗадумались о покупке объект для проживания https://kupitkvartiruzdes.ru с подходящей планировкой. Одним покупателям стоит учитывать район. При сравнении квартир имеет смысл проверить расположение. Помимо стоимости не стоит забывать о инфраструктуре района. В отдельных разделах освещаются практические аспекты покупки. Проверяйте информацию, сопоставляйте характеристики и формируйте собственное представление о подходящем объекте.
RichardScate
October 01, 2026, at 2:30 pmautomati hri online kasyno online z wysoka wyplacalnoscia casino no deposit bonus slovakia
RichardScate
October 01, 2026, at 2:48 pmolybet casino sk slovenske online kasino automaty hry zadarmo
TimothyDeede
October 01, 2026, at 2:56 pmPerpFuse https://www.perpfuse.com is a real-time perpetual futures analytics platform for crypto traders. Compare funding rates, open interest, liquidity, spreads, execution costs, and cross-exchange arbitrage opportunities across leading CEX and DEX markets
Alfredwes
October 01, 2026, at 3:37 pmnajlepЕЎie ruletovГ© strГЎnky kasГna s minimГЎlnym vkladom 20 eur casino online fortuna Free spin hry nove casino bez vkladu william hill live casino
Alfredwes
October 01, 2026, at 3:50 pmWhy is 777 used in gambling spiny zadarmo za registrГЎciu automaty oline zdarma Retro spiny spigo fruits slot poker texas holdem pravidla
bornacrimepdfTaini
October 01, 2026, at 3:53 pmThe title Born a Crime refers to the Immorality Act of 1927. Noah explains this law in the opening pages. If you are looking for a born a crime pdf, you are looking for the story of a walking violation of the law. The premise is absurd, but the consequences were real. The book details the secrecy required to keep him safe. He couldn’t walk with his parents in public. This legal framework shapes the entire narrative. It is a stark reminder of how laws can be used to dehumanize. https://bornacrimepdf.store/ Trevor Noah Born A Crime Pdf Free Download
betterthanthepromeTaini
October 01, 2026, at 3:54 pmLynn Painter has a gift for writing swoon-worthy love interests, and Wes is no exception. He steps up when Liz needs him most, despite their rocky past. This story is a warm hug in book form. To see how their relationship unfolds, grab the Better Than the Prom epub. It is an accessible way to enjoy a high-quality romance story that fits perfectly into a busy schedule. https://betterthanthepromepub.site/ Better Than The Prom Lynn
Alfredwes
October 01, 2026, at 4:45 pmplaytech live casino automaty online slovenske tipos hracie automaty zadarmo Bezplatne spiny dnes bez vkladu hracie automati sizzling hot bonusove kody casino
MarkSaugh
October 01, 2026, at 4:48 pmSpeaking carefully because I do not want to overstate things this site is genuinely above average across multiple measurements, and a stop at alpinecovegoodsoutlet continued the above average performance, the calibration of judgement against potential overstatement is something I take seriously and this site clears the higher bar even after that calibration applies.
MatthewEmera
October 01, 2026, at 4:56 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-v-odnostoronnem-poryadke/]развод через суд без согласия одного из супругов[/url] – обращайтесь, юрист подготовит заявление, соберет документы, представит ваши интересы в суде и поможет расторгнуть брак в одностороннем порядке. Получите бесплатную консультацию и узнайте, какой порядок подходит именно в вашей ситуации.
RichardScate
October 01, 2026, at 5:09 pmfree spiny u dedka kasyno online na realne pieniadze online casino bonus za registrГЎciu bez vkladu
Prestonsok
October 01, 2026, at 5:17 pmCame in confused about the topic and left with a much firmer grasp on it, and after trailharborcollective I felt I could explain this to someone else without hesitation, that is the gold standard for any educational content and most sites simply fail to reach it ever which is unfortunate but true.
850betapp
October 01, 2026, at 5:21 pmThe app is super intuitive and doesn’t crash. It makes betting on the go so much easier. Big shoutout to 850betapp for the great service.
RichardScate
October 01, 2026, at 5:31 pmonline casino 20 euro gratis no deposit bonus kasina s minimalnym vkladom blackjack online free for fun
Javonzef
October 01, 2026, at 5:46 pmSpeaking carefully because I do not want to overstate things this site is genuinely above average across multiple measurements, and a stop at skyharborvault continued the above average performance, the calibration of judgement against potential overstatement is something I take seriously and this site clears the higher bar even after that calibration applies.
RichardScate
October 01, 2026, at 5:50 pmhra automaty online zdarma п»їonline kasina slovensko casino za registrГЎciu bonus
Gregrex
October 01, 2026, at 6:06 pmNow planning to come back when I have the right kind of attention to read carefully, and a stop at riverstoneemporium reinforced that plan, choosing the right moment to read certain content is a quiet form of respect for the work and this site is generating those careful planning behaviours from me consistently as a reader.
Abrahammic
October 01, 2026, at 6:20 pmNow feeling slightly more committed to my own careful reading practices having read this, and a stop at elmwillowemporium reinforced that commitment, content that models the kind of attention it deserves is content that calibrates the reader and this site has clearly raised my own bar for what to bring to good writing today.
BertramcoAsy
October 01, 2026, at 6:20 pmHigh quality writing, no marketing speak and no buzzwords that mean nothing, and a stop at rosecovegalleria kept that going, simple direct content that actually communicates something is harder to find than it should be and this is one of the rare places that gets it right consistently across many different posts.
Alfredwes
October 01, 2026, at 6:53 pmpoker online za penГze ice casino 25 € bonus hracie automaty admiral online Registracia v casine za 5 eur turbo automati zdarma live casino no deposit bonus
Alfredwes
October 01, 2026, at 7:06 pmspigo fruits slot free spins volne otocky casino bonus bez vkladu vip bonus doxxbet Automaty turbo overenГ© casino recenzie od hrГЎДЌov gold games hraci automaty
Printercromi
October 01, 2026, at 7:11 pmЗдравствуйте!
По запросу «3d принтер bambu lab h2s combo» на сайте SloyTek представлена релевантная страница — карточка товара с описанием основных параметров продукции. Описание помогает оценить характеристики, комплектацию, совместимость, назначение, условия покупки и доступные варианты поставки. Перед заказом полезно проверить соответствие выбранной позиции вашему оборудованию и предполагаемым задачам. Актуальную стоимость, наличие, комплектацию и условия доставки следует уточнить непосредственно перед оформлением заказа.
Подробная информация на сайте https://sloytek.ru/product/bambu-lab-p1s-combo
abs pa gf8, мини триде принтер, creality spacepi x4
филамент start petg, [url=https://sloytek.ru/filament/pla]pla пластик для 3d[/url], bambu petg basic
Удачи!
RichardWothe
October 01, 2026, at 7:13 pmIf I had to summarise the editorial sensibility of this site in a few words it would be careful and human, and a look at foreststonecourtyard extended that summary feeling, capturing the essence of a sites approach in brief is hard but this site has a clear enough identity that the summary comes naturally enough.
Robertpes
October 01, 2026, at 7:20 pm[url=https://xvideos24.top/best-compilations-hot-music-videos-vol-36-more-at-javhd-net/]LE FOLLO EL CULO A MI MEJOR AMIGA Le Mando El Video Al Cornudo De Su Novio Para Que Sepa Cómo Abrirle El Culo[/url]
NormanHam
October 01, 2026, at 7:48 pmhttps://diazaxorex.com/about
Henryelorp
October 01, 2026, at 7:55 pmFelt the post had been quietly polished rather than aggressively styled, and a look at budgetbreeze confirmed the same understated polish, sites whose quality reveals itself slowly rather than announcing itself loudly are the kind I trust more deeply because the trust is not based on first impressions of marketing but actual substance.
Alfredwes
October 01, 2026, at 7:59 pmlive stream banco casino casino free 10 € bonus za registraciu 5€ Vklad do casina cez sms new casino sk asia gaming live casino
RichardScate
October 01, 2026, at 8:10 pmhracie automaty taliansko kasina s minimalnym vkladom 1 eur hracie automaty sizzlingzdarma
RichardScate
October 01, 2026, at 8:32 pmhrat online casino odbierz 100 zl bez depozytu za rejestracje casino hra zdarma
RichardScate
October 01, 2026, at 8:51 pmautomaty hry zdarma synot zahranicne casino kde mozu hrat Slovaci rt bet casino bonus bez vkladu
KalebWax
October 01, 2026, at 9:01 pmConsidered as a whole this site has developed a coherent point of view that comes through in individual pieces, and a look at lemonlarkoutlet continued displaying that coherence, sites with a unified perspective rather than a grab bag of takes are sites with editorial maturity and this one has clearly developed that maturity through years of work.
WalkerLap
October 01, 2026, at 9:11 pmIn the middle of an otherwise scattered day this post landed as a moment of focus, and a stop at rubyorchardcollective extended that focused feeling across more pages, content that anchors a fragmented day rather than contributing to the fragmentation is content with real centring effect and this site is providing that anchoring function for me.
BenBeelo
October 01, 2026, at 9:47 pmThank you for not assuming the reader already knows everything, the explanations meet me where I am, and a look at lavendercovecommerceatelier did the same, that consideration is what makes a site feel welcoming rather than gatekeepy which is sadly the default mood across the modern web today for most subjects covered.
Alfredwes
October 01, 2026, at 10:03 pmplaytech live casino mobile kasГno slovenskГЅ automaty online o peniaze Najnovsie casino na slovensku hracie automaty on line zadarmo online casino pre slovensko
Alfredwes
October 01, 2026, at 10:16 pmhracie automaty vhp online 5€ bonus casino automaty zdarma o peniaze Vklad 5 eur automaty online platba mobilom casino bonus za registraci bez vkladu 2026
Cristianpoisp
October 01, 2026, at 10:24 pmA particular kind of restraint shows up in the writing, and a look at mooncovevault maintained the same restraint across pages, knowing what not to say is just as important as knowing what to say and this site has clearly developed strong instincts on both sides of that editorial line throughout pieces I have read.
planet88login
October 01, 2026, at 10:34 pmFinally a platform that doesn’t lag during peak hours. The login process is quick and the graphics are top notch. Glad I found planet88login
Alfredwes
October 01, 2026, at 11:09 pmautomaty online za sms How to get 1 win bonus code automaty zdarma hrat Novo spustene kasino na slovensku 6 deck blackjack online free spassino no deposit
RichardScate
October 01, 2026, at 11:11 pmhry hracie automaty zdarma kasyno w ktorym zaplacisz blikiem 3 valcove automaty hrat zdarma
RichardScate
October 01, 2026, at 11:33 pmhri automati zdarma kajot mega joker wyplacalne kasyna gdzie zaplacisz blikiem 1 win bonus casino
RichardScate
October 01, 2026, at 11:51 pmlive casino s dealermi online slovensko tocenia zadarmo po registracii blackjack online betfair
Michaelduele
October 01, 2026, at 11:55 pmЕсли планы на Санкт-Петербург пока не определены, постоянную прописку менять необязательно. Можно начать с временной регистрации, спокойно пожить в городе, разобраться с работой и районом, а уже потом решать вопрос о постоянном месте жительства – купить прописку
EmmettFuh
October 02, 2026, at 12:31 amConsidered against the flood of similar content this one stands apart in important ways, and a stop at jewelcoveartisanmarket extended that distinctive feel, sites that find their own corner of a crowded topic and stay there are sites worth following and this one has clearly carved out its own space and committed to defending it carefully.
Roderickbot
October 02, 2026, at 12:31 amFelt energised after reading rather than drained, which is unusual for online content these days, and a look at violetharborcollectivemart continued that good feeling, content that leaves you better than it found you is rare and worth bookmarking when you stumble across it for the first time today or any other day really.
Jacksontindy
October 02, 2026, at 12:39 amNow feeling confident enough in this site to use it as a reference point for evaluating others on the same topic, and a look at actionengine continued the comparison friendly quality, sites that serve as quality benchmarks for their topic are precious and this one has clearly become a benchmark for me on this particular subject area.
Alfredwes
October 02, 2026, at 1:11 amautomaty hry diamond zdarma online casino review online casino blackjack Casino 5 eur online poker slovensko top casino bonus kГіd
Alfredwes
October 02, 2026, at 1:24 amHas anyone won big on online gambling automaty 2026 sk zahrat automati zdarma Hry online za peniaze automati zdarma vyherni online poker slovensko
GregJam
October 02, 2026, at 1:38 amWorth saying this site reads better than most paid newsletters I have tried, and a stop at kettleridgeartisanmart confirmed that comparison, the bar for free content is often lower than for paid but this site clears the paid bar consistently and that says something about the editorial approach behind the work being published here regularly.
RichardScate
October 02, 2026, at 2:11 amcasino monaco online kasyno online z natychmiastowa wyplata hrat automaty zdarma book of fra
Alfredwes
October 02, 2026, at 2:16 amstachnut automati zdarma online casino slovensko 5 euro deposit kajot automati kajot zdarma Slovenske online casina casino 10 € bonus casino classic 1 €
RichardScate
October 02, 2026, at 2:33 amnajlepЕЎie online kasГna na slovensku casino s minimalnym vkladom desat eur ako urobiЕҐ ruletu online zadarmo
Derrickincuh
October 02, 2026, at 2:41 amIf I had to defend the time I spend reading independent blogs this site would feature in the defence, and a look at alpinecoveartisanbazaar reinforced that defensive utility, the ongoing case for non algorithmic reading is one I make to myself periodically and sites like this one provide the actual evidence that supports the case clearly.
RichardScate
October 02, 2026, at 2:52 amgrand x casino Nemecke online casino bonus bez vkladu bonus za registraciu 2026
MichaelGlush
October 02, 2026, at 3:44 am[url=https://ar-cocos-capital.cc/]COCOS CAPITAL[/url]
A área de Cocos Capital Login permite localizar o acesso à plataforma de forma simples, sendo recomendável sempre utilizar os canais oficiais para entrar na conta.
Alfredwes
October 02, 2026, at 4:19 amhracГ automaty online zdarma hazardne hry automaty zdarma kasino online automaty Casina online na slovensku big bamboo casino kolik mГЎ bonver casino spuЕЎtД›nГЅch her
Alfredwes
October 02, 2026, at 4:32 amhri zdarma automati hracie automaty live fortuna casino je spoДѕahlivГ© Novinka medzi slovenskymi kasinami automaty online sk vklady cez sms automaty kajot zdarma hry
MichaelMen
October 02, 2026, at 5:10 amПри выборе пластиковых окон для дома или квартиры важно учитывать качество материалов, особенности монтажа и удобство дальнейшей эксплуатации. Современные оконные конструкции позволяют сочетать практичность, удобство эксплуатации и аккуратный внешний вид.
Если рассматриваете пластиковые окна Томск [url=https://bestokna.tomsk.ru/]https://bestokna.tomsk.ru/[/url], можно ознакомиться с решениями компании «Окна БЭСТ» для жилых и офисных помещений. Компания использует проверенные материалы и выполняет установку с учетом необходимых требований.
Функциональные свойства окна можно дополнить подходящим декоративным оформлением. Для этого могут использоваться шпросы и оконная раскладка, подчеркивающие архитектурные особенности дома.
RichardScate
October 02, 2026, at 5:11 amcasino hry – hracie automaty zaklady ktore gracze stawiaja w ruletce casino s bonusom
Alfredwes
October 02, 2026, at 5:24 amblackjack online players online casino dealer 5 valcove automaty hrat zdarma Casino registracia online automati kajot grand x casino
Rickywax
October 02, 2026, at 5:27 amРегистрация в Москве может понадобиться после смены города проживания даже тогда, когда переезд не является постоянным. Временный формат помогает официально подтвердить нахождение по новому адресу и подходит для людей, приехавших на определенный период – сколько стоит временная регистрация в москве на 1 год для граждан рф
RichardScate
October 02, 2026, at 5:33 amsazka online casino kasyno szybkie wyplaty best electric elephant slot sites
DomenshopE
October 02, 2026, at 5:34 amПривет всем!
Магазин доменов RU даёт доступ к проверенным и надёжным вариантам. Короткое и запоминающееся имя легче продвигать в социальных сетях. Доступна полная статистика по трастовости и возрасту домена. Свяжитесь с менеджером, чтобы получить консультацию по выбору домена. Такой актив сохраняет ценность даже при последующей перепродаже.
Актуальные домены в продаже на сайте https://www.domenshop.net/
Всего наилучшего и хорошего развития!
RichardScate
October 02, 2026, at 5:52 amfree spiny casino dnes kasyna zagraniczne bez depozytu free spins bez vkladu
Printercromi
October 02, 2026, at 6:23 amЗдравствуйте!
Страница интернет-магазина SloyTek по запросу «лазерный гравер twotrees» ведёт в каталог оборудования выбранного бренда, где собрана информация для выбора и заказа. Основные критерии сравнения включают линейку моделей, назначение, характеристики, комплектацию, совместимость и доступные варианты. Информация на странице упрощает предварительный подбор и подготовку вопросов специалисту. Перед покупкой стоит сопоставить технические требования, расходные материалы и дальнейшие затраты на эксплуатацию.
Подробная информация на сайте https://sloytek.ru/product/bambu-lab-a1-combo
магазин 3д принтеров в спб, 3d принтер flashforge 5m, adventure 5m pro
3d принтер bambu lab p1s combo eu, [url=https://sloytek.ru/product/qidi-q2]qidi q2[/url], тпу пластик
Удачи!
Alfredwes
October 02, 2026, at 7:27 amautomaty zdarma hry sizzling hot spinit casino online blackjack online training Free spiny casino hracie automaty navod hracie automaty vyherne bez vstupneho poplatu s bonusom
Alfredwes
October 02, 2026, at 7:40 amhracГ automaty online playing slots in casino 4 games casino Top kasino na slovensku automaty zdarma poker online casino zadarmo
RichardScate
October 02, 2026, at 8:12 amfree spiny do casina przeglad metod platnosci w kasynach online automaty otoДЌky zdarma za registraci
rever_mzKl
October 02, 2026, at 8:22 amSpiele jetzt seit bald einem Jahr bei denen und sag mal was dazu, weil hier im Forum meistens nur die immer gleichen Namen auftauchen. Reingekommen bin ich durch einen Tipp aus dem Bekanntenkreis, nicht uber irgendeine Werbung. Der Spielebereich von Bingoal ist ordentlich bestuckt — grob 2000 Titel laut Filter, inklusive dem ganzen Pragmatic-Katalog, Yggdrasil und auch Big Time Gaming.
Book of Dead ist mein Dauerbrenner, dazu manchmal Gates of Olympus fur die Freispielrunden. Live ist echt brauchbar: Evolution liefert da echte Croupiers, Crazy Time und Lightning Roulette gehen dauernd. Zu Stosszeiten war der Stream zweimal kurz weg — nervt aber schon.
Beim Willkommenspaket: angeboten werden 100% bis 300 CHF und 50 Freispiele, die Umsatzbedingung liegt bei 35x — also normal fur den Markt. Ein kleiner No-Deposit-Teil kam spater per Aktion, nicht verlasslich. Die aktuellen Konditionen siehst du druben auf [url=https://capehunt.co.za/bingoal-sicherheitsguide-lizenz-datenschutz-und-spielerschutz-im-uberblick/]bingoal[/url] bevor du einzahlst — die andern das namlich ofter.
Die Registrierung war schnell, so funf Minuten, Mindesteinzahlung 20 CHF, ich nutze Visa und ab und zu Skrill. Krypto ginge auch, habe ich aber nie probiert. Cashouts bei Bingoal kamen bei mir zwischen 12 und 36 Stunden bis aufs Skrill-Konto, Karte deutlich langer. Der Dokumenten-Upload zog sich zwei Tage — Pass und Wohnsitznachweis, typisch Schweiz halt.
Mobil nutze ich einfach Safari, ist okay, wenn auch keine echte App. Support habe ich zweimal gebraucht: beim ersten Mal in funf Minuten geantwortet, deutsch. Die Lizenzierung lauft nicht uber die ESBK, ist fur manche hier sicher ein Thema — wer aus der Schweiz spielt sollte das im Hinterkopf bleiben. Unterm Strich habe ich etwa 80 CHF Plus, was nichts beweist. Setze mir seit Juni ein Wochenlimit und bei Bingoal geht das ohne Nachfragen durch, das schatze ich.
karkasnyy_fbSn
October 02, 2026, at 8:32 am[url=https://karkasnye-doma-spb11.ru]каркасный дом[/url] станет комфортным и энергоэффективным решением для загородной жизни.
Монтаж дома организуют по проекту, где заранее определены размеры и расположение помещений.
Стены такого дома способны эффективно удерживать тепло.
Каркасная технология дает широкие возможности для разработки планировки.
При монтаже тщательно проверяют крепления, теплоизоляционный слой и защиту от воды.
Alfredwes
October 02, 2026, at 8:33 ammobile spigo casino casino zodiac login online hry automaty zdarma Hry automaty video automaty zdarma bez registrace hracie automaty zdarma super rels 2
RichardScate
October 02, 2026, at 8:34 amhraci automati zdarma bez registracie jak wyplacic wygrana z kasyna online casino automaty hrat zdarma
RichardScate
October 02, 2026, at 8:52 amcasino automaty zdarma kajot 81 automaty bez vkladu casino bonus bez vkladu 10€
RiverNargo
October 02, 2026, at 9:27 amWill be coming back to this for sure, too much good content to absorb in one sitting, and a stop at amberharborvault only added more pages I want to dig through, this site is going onto my regular rotation list because it consistently delivers something worth the visit lately rather than empty filler.
Alfredwes
October 02, 2026, at 10:34 ampoker texas holdem What is the most profitable online slot game verde casino no deposit bonus Online kasino s vyhrou penazi automaty online za sms nike 50 spinov zadarmo
JoshuaMog
October 02, 2026, at 10:42 amЕсли интересует: [url=https://www.sostav.ru/blogs/286052/83610]сертификация ISO 9001[/url] – это отличная возможность получить соответствие системы менеджмента качества организации международным требованиям. Сертификация помогает повысить доверие клиентов и партнеров, укрепить деловую репутацию и получить дополнительные преимущества при участии в тендерах. Узнайте, кому необходим сертификат ISO 9001, как проходит процедура оформления, какие документы потребуются и сколько действует сертификат.
revery_kqel
October 02, 2026, at 10:42 amSo I’ve been messing around on Revery Play for about a couple of months and figured I’d share my take here. I registered after seeing an ad — minimum deposit was ?10 which wasn’t bad, deposited ?30 to test it and got a 100% welcome bonus up to ?500 plus 150 free spins on registration. Wagering is 35x which isn’t the lowest I’ve seen but not terrible either.
Game-wise is pretty stacked — there’s somewhere around 3000 slots and table games from studios including Play’n GO, NetEnt, Big Time Gaming. I’ve been smashing Sweet Bonanza mostly — hit a decent 400x on Sweet Bonanza the other night. Live tables runs on Evolution — Lightning Roulette is addictive honestly, proper dealers streaming in HD.
The bit that sold me on Revery Play is how quick withdrawals are. Paying with Neteller and the payout landed in less than a day. There’s also Bitcoin and Neteller if that’s your thing. I’d browse their full bonus page over at [url=https://oswestryhotair.co.uk]reveryplay[/url] to see for yourself.
Tbh, it’s not all perfect. Live chat at Revery Play took ages once — I waited like 15 minutes for live chat one evening. Also the mobile version works fine but some menus are fiddly next to bigger brands. No standalone app, just the browser version.
Overall though, I’m still playing there so make of that what you will. The site is regulated and seems legit. If you’re in the UK it’s a solid shout — only be patient with live chat wait times.
Alfredwes
October 02, 2026, at 10:47 amdolce vita casino free spiny za dnes automaty online vklad cez sms Hry za realne peniaze casino k login apex automaty online zadarmo
BrandonHerne
October 02, 2026, at 10:59 amLiked that the post landed without needing to manufacture controversy or take a contrarian stance for attention, and a stop at alpinecovegalleria continued that grounded approach, content that earns attention through quality rather than provocation is the kind that builds long term trust rather than burning it on quick wins.
RichardScate
October 02, 2026, at 11:12 amdragon tiger live casino kasyno online opinie casino hry hracie automaty
MarshallStoms
October 02, 2026, at 11:16 amNow considering writing a longer note about the post somewhere, and a look at bayharborcollective added more material for that note, content that prompts me to write rather than just consume is content with generative energy and this site is producing that generative effect for me at a higher rate than most sources.
Romanlaums
October 02, 2026, at 11:22 amWorth recognising that the post handled a familiar topic without reaching for any of the obvious hot takes, and a stop at juniperharbortraders continued that fresh treatment, sites that find new angles on subjects others have exhausted are sites worth following carefully and this one has clearly developed that exploratory instinct through patient practice.
RichardScate
October 02, 2026, at 11:34 amHow do I claim casino free spins nove bonusy v online casinach zdarma automaty sizzling hot
Alfredwes
October 02, 2026, at 11:40 amcasino slovakia online jackpot city flash casino online slot machine Kasino min vklad live casino tournaments hracie automaty zdarma joker 81
RichardScate
October 02, 2026, at 11:53 ameuro gold game ziskaj bonus za registraciu v casine 4go casino bonus za registraciu
BeauWeisp
October 02, 2026, at 12:02 pmSkipped the TLDR thinking I would read everything anyway, and ended up enjoying the path through the full post, and a stop at woodmeadowoutlet similarly rewarded the patient read, summaries are useful but the journey through good writing is part of what makes the destination feel earned rather than just delivered cleanly.
DavidCag
October 02, 2026, at 1:05 pmLooking for a trusted online casino in Australia? Olympia online casino Australia is becoming a trusted destination for online gaming fans thanks to its fast banking options.
Players visiting the Olympia Casino official site can access premium slots and table games directly from their desktop. The Olympia Casino Australia online platform is designed for high-speed access and works perfectly across all devices.
Using the Olympia Casino Australia site, players can explore interactive live dealer tables from leading software providers. Whether you prefer high-volatility slots, there is always something exciting available.
Australian casino fans can quickly create an player profile through the Olympia Casino Australia login page section. Registration is fast, allowing players to start gaming in just seconds.
The Olympia Casino Australia app gives users the freedom to access games on the go. The mobile experience is fully optimized for Android, while the desktop casino platform delivers immersive gameplay.
Players searching for the best Olympia Casino Australia games list will discover a massive collection of titles, including video slots, as well as blackjack. The Olympia Casino Australia live casino creates an authentic casino atmosphere with interactive gameplay.
Bonuses and promotions are another reason why players choose Olympia Casino Australia online – https://casinoolympia.casino/. The Olympia Casino Australia promotions info regularly features welcome packages designed to extend gaming sessions.
Casino enthusiasts appreciate the secure banking system available through the Olympia Casino Australia payment methods section. Deposits and withdrawals are processed using modern banking technologies. The Olympia Casino Australia withdrawals is optimized for fast payouts.
Security remains a major priority at Olympia Casino Australia. The platform uses advanced cybersecurity protocols to protect all user information. The Olympia Casino Australia privacy policy pages explain how data is protected and how fair gaming standards are maintained.
Players can also review the Olympia Casino Australia terms and conditions to better understand the rules, bonus policies, and platform regulations. The casino promotes responsible entertainment for all users.
Responsible gaming tools are available through the Olympia Casino Australia safe gambling section. Players can set session controls through the player settings area whenever needed.
If assistance is required, the Olympia Casino Australia support provides fast response times. Users can contact the Olympia Casino Australia user support regarding technical support.
The verification process helps maintain platform security and ensures that withdrawals are processed safely. Verification is usually completed quickly, allowing players to continue gaming without long delays.
If you prefer live casino action, Olympia Casino online delivers a complete gambling experience for Australian players. With premium gaming content, the platform continues to attract users looking for real-money casino gaming.
Visit the Olympia Casino Australia page today and experience premium casino gaming.
IsaiahTaite
October 02, 2026, at 1:08 pmReading this brought back an idea I had set aside months ago, and a stop at paprikaplace added more substance to that idea, content that revives dormant projects in my own thinking is content with serious creative value and this site is contributing to my own work in ways I had not expected when first clicking through.
Frederickvag
October 02, 2026, at 1:29 pmA piece that brought a sense of order to a topic I had been finding chaotic, and a look at sageharborvault continued that organising effect, content that imposes useful structure on messy subjects is doing genuine intellectual work and this site is providing that organisational function across multiple posts I have read recently here.
GeraldNen
October 02, 2026, at 1:31 pmhttps://mexicocasinohub.com/resenas-casinos/
DonaldnuS
October 02, 2026, at 1:43 pmautomaty online za penize 5-vГЎlcovГ© automaty zdarma bonus 100 casino Free spin hry blackjack online casino live dealer ruleta online hra
DonaldnuS
October 02, 2026, at 1:56 pmruleta ЕЎЕҐastia online hra online casino slovensko cez sms min 5 casino za 1 euro Automaty na hranie na internete gametwist kasino slots hracie automaty zdarma slovensko live casino
Pablofeple
October 02, 2026, at 2:02 pmReading this confirmed a hunch I had been carrying about the topic without having articulated it, and a stop at mintstonecollective extended the confirmation, content that gives shape to fuzzy intuitions is doing the rare work of making private thoughts public and this site is providing that articulating service consistently for me lately.
Juliusdob
October 02, 2026, at 2:12 pmcasino hry zdarma automaty vklad do casina cez mobil gratorama 7 € registracia
Grahamzed
October 02, 2026, at 2:12 pmBookmark folder created specifically for this site, and a look at kettlecrestmarket confirmed the dedicated folder was the right call, dedicated folders for individual sites are a level of organisation I rarely deploy and this site has earned that level of dedicated tracking based on the consistency I have seen so far across sessions.
Juliusdob
October 02, 2026, at 2:34 pmviherne hracie automati Nemecke online casino bonus bez vkladu ruleta bonus bez vkladu
OctavioVarry
October 02, 2026, at 2:44 pmMy friends would appreciate a few of these posts and I will be sending links accordingly, and a look at lemonlarkmarketstudio added more pages to my share queue, content that earns shares to specific people in specific contexts is content with social utility and this site is generating those targeted shares from me consistently lately.
DonaldnuS
October 02, 2026, at 2:49 pmbonusovГ© kГіdy casino poker hraci automaty zdarma online blackjack live dealer Zadarmo turbo hracie automaty online poker slovensko 2026 candy stars slot
Juliusdob
October 02, 2026, at 2:53 pmslovenske online automaty kasyno online wyplata na karte bankowa casino s ceskou licenci
JeffreyIgnor
October 02, 2026, at 3:11 pm[url=https://gerenciador-bb-financeiro.digital/]BANCO BRASIL PJ[/url]
Os serviços do BB Digital PJ ajudam empresas a utilizar recursos bancários por canais digitais, trazendo mais praticidade para diversas rotinas financeiras.
DerrickEveni
October 02, 2026, at 3:26 pmSkipped the comments to avoid spoilers and came back later to find them genuinely worth reading, and a stop at pearlcovevault extended that surprised respect, when the discussion below a post matches the quality of the post itself you have found something special and this site appears to attract that kind of audience.
crazy_fzSr
October 02, 2026, at 3:30 pmMi sono imbattuto in Crazy Time qualche settimana fa cercando qualcosa di nuovo dove giocare e devo dire che ci gioco ancora adesso. Non mi aspettavo granche perche ne ho provati tanti, ma il catalogo giochi e enorme. Ci trovi roba di Pragmatic Play come Sweet Bonanza e Gates of Olympus, e anche diverse slot di NetEnt e roba Play’n GO come Book of Dead. Ci saranno piu di 2000 giochi in tutto, insomma c’e da perdersi.
La parte live mi ha convinto parecchio. Tutto in mano a Evolution, con croupier veri e la qualita video e ottima. Mi sono fissato con la ruota di Crazy Time ed e una droga. Blackjack, baccarat e roulette ci sono ovviamente, ma i game show sono un altro livello. Un difetto che mi ha dato fastidio e che a volte il caricamento dei tavoli e lento, niente di tragico pero.
Per il bonus di benvenuto su Crazy Time offrono il 100% sul primo deposito fino a 500 euro con in aggiunta 50 giri gratis sulla slot del momento. Devi rigirarlo 35 volte, non il migliore ma nemmeno assurdo. C’e chi offre meno, pero almeno i termini sono chiari. Il deposito minimo e di venti euro. Potete controllare le offerte attuali passando da [url=https://bygglovsprocessen.com]Crazy Time[/url] prima di registrarvi.
Per versare e prelevare non ho avuto problemi. Accettano Visa, Mastercard, Skrill, Neteller e pure crypto. Ho prelevato con Skrill e in 24 ore avevo i soldi. Meglio di certi posti dove aspetti una settimana. Sul telefono Crazy Time funziona bene dal browser senza scaricare nulla, il sito e responsive e non ho avuto crash. Nessun bonus no deposit purtroppo, sarebbe stato un bel plus.
L’assistenza clienti fa il suo lavoro. Li ho contattati per un problema col bonus e ci hanno messo una decina di minuti. Parlano italiano il che aiuta. La licenza e Curacao, lo so che non e MGA, pero non ho mai avuto rogne. Per noi italiani mi trovo bene.
Tommydrole
October 02, 2026, at 4:21 pmIa Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia
Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia
Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia
Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia Ia
https://iaiaia.site/
rever_fdKl
October 02, 2026, at 4:48 pmBin seit bald einem Jahr auf der Seite und schreibs mal auf, weil hier im Forum meistens nur die immer gleichen Namen durchgekaut werden. Reingekommen bin ich weil ein Kumpel aus Zurich das erwahnt hat, nicht uber irgendeine Werbung. Der Spielebereich von Bingoal ist ordentlich bestuckt — irgendwo zwischen 1500 und 2000 Slots nach meinem Gefuhl, mit dem ublichen Pragmatic-Zeug, Play’n GO und auch Big Time Gaming.
Gates of Olympus lauft bei mir am meisten, ab und zu Bonanza von BTG fur die Freispielrunden. Der Live-Bereich ist stark: es lauft uber Evolution mit echte Croupiers, Crazy Time ist quasi immer belegt. Abends um zehn war der Stream zweimal kurz weg — kein Drama.
Zum Bonus: es gibt 100% bis 500 CHF plus 100 Freispiele, Wagering 35x auf den Bonusbetrag was man vorher lesen sollte. Etwas ohne Einzahlung lauft ab und zu als Aktion, aber nicht dauerhaft. Welche Codes gerade laufen siehst du jeweils bei [url=https://novosite.trustsystemalert.com.br/2026/09/23/bingoal-schritte-und-methoden-fur-registrierung-bonus-mobile-nutzung/]bingoal[/url] falls du vergleichen willst — das wird recht haufig angepasst.
Einzahlen ging unkompliziert, Mindesteinzahlung 20 CHF, ich nutze Visa und ab und zu Skrill. Krypto ist auch moglich, nutze ich nicht. Cashouts bei Bingoal dauerten ein- bis zweimal rund 24 Stunden bis es da war, per Karte hat es drei Tage gebraucht. Der Dokumenten-Upload zog sich zwei Tage — ID und eine Rechnung als Adressnachweis, kennt man ja.
Auf dem Smartphone nutze ich einfach Safari, funktioniert sauber. Support habe ich zweimal gebraucht: beim ersten Mal in funf Minuten geantwortet, deutsch. Die Lizenzierung lauft nicht uber die ESBK, das muss man fur sich selbst einordnen — wer aus der Schweiz spielt sollte das im Hinterkopf bleiben. Unterm Strich habe ich etwa 80 CHF Plus, mehr Gluck als System. Setze mir seit Juni ein Wochenlimit und bei Bingoal geht das ohne Nachfragen durch, das schatze ich.
DonaldnuS
October 02, 2026, at 4:50 pmruleta online o penГze 1 € deposit bonus automaty zdarma nove Kasino s vkladom od 20 eur minimum casino hry zdarma sk hraci automaty hracie automaty cez sms online
JoshuaMog
October 02, 2026, at 5:03 pmЕсли интересует: [url=https://www.sostav.ru/blogs/286052/83610]сертификат соответствия ИСО 9001[/url] – это отличная возможность получить соответствие системы менеджмента качества организации международным требованиям. Сертификация помогает повысить доверие клиентов и партнеров, укрепить деловую репутацию и получить дополнительные преимущества при участии в тендерах. Узнайте, кому необходим сертификат ISO 9001, как проходит процедура оформления, какие документы потребуются и сколько действует сертификат.
DonaldnuS
October 02, 2026, at 5:03 pmonline ruleta recenzie live blackjack online hracie automaty 5 vГЎlcovГ© zdarma Kasino 10 eur online casino bonus slovensko hracie automaty zdarma hunster dream
Juliusdob
October 02, 2026, at 5:11 pmonline hry automaty bez registrace kasyno online blik ice casino bonus
OliverHEt
October 02, 2026, at 5:13 pmA piece that respected the reader by not over explaining the obvious, and a look at tealcoveartisanmart continued that calibrated approach, finding the right level of explanation is one of the harder editorial calls and this site has clearly thought carefully about what readers will already know versus what they need help with consistently.
Francisdag
October 02, 2026, at 5:19 pmNow realising the post solved a small problem I had been carrying for weeks, and a look at motionframework extended that problem solving function, content that connects to specific unresolved questions in my own life rather than just providing general interest is content with real practical impact and this site is providing that practical value.
lottoland_kqEr
October 02, 2026, at 5:21 pmPelasin Lottolandissa muutama viikko taaksepain ja taytyy myontaa etta alkuun oli skeptinen mutta meni ihan hyvin. Tilin luonti ei kestany kauaa, perus jutut ja paasi pelaamaan. Ekan talletuksen sai tehtya 10 eurolla Visan kautta ja oli sujuvaa. Se on semmonen asia minka huomaa heti — hitaat maksut on dealbreaker.
Pelikirjastosta pakko mainita et sita riittaa. Lottoland tarjoo tunnetuilta pelintekijoilta niinku NetEnt ja Big Time Gaming, joten tutut nimikkeet on paikalla. Ma pelasin Book of Deadia paaasiassa ja muutama kiva voitto iski. Kolikkopeleja on reilusti yli tuhat ja sit on klassikot myos. Pieni miinus — pelien etsinta ei oo paras mahdollinen, valilla menee aikaa ettiessa.
Livepeleista loytyy ihan kunnon livepoytia ja pelattiin Lightning Roulettea yksin illalla. Toimii ilman patkimista mobiilissa, eika tarvi erillista appia. Tervetuliaisbonuksesta puhuttaessa — mulle tuli tervetuliaisen ja ilmaiskierroksia. Kierratys oli kolmisenkymmenta kertaa mika on ihan normaali. Kannattaa lukee ehdot silti etukateen.
Kotiutukset Lottolandilta meni mulle suht nopeesti. Netellerin kautta kesti noin paiva ja pankkisiirto otti pari paivaa. Ei nopein mita oon nahny mutta ei valittamista. Loydat lisatietoa katevasti [url=https://donghuang-research.com]Lottoland[/url] ennen ku rekisteroidyt. Asiakaspalvelu hoituu chatilla ja mulle vastattiin kohtuuajassa ku kysyin jotain.
Kannykalla pelaaminen toimii selaimella ja se riittaa mulle. Saitti aukeaa sutjakkaasti ja pelit pyorii moitteetta. Lisenssi on kunnossa ja se on mulle tarkeeta. Toinen mika vahan hairitsi navigointi vois olla selkeempi, ei se iso juttu oo. Kyl ma aion jatkaa siella kunnes joku parempi tulee vastaan.
Juliusdob
October 02, 2026, at 5:33 pmautomaty zdarma hry sizzling hot darmowe kryptowaluty bez depozytu free spiny eu
Juliusdob
October 02, 2026, at 5:51 pmautomaty free spiny zagraj w automaty w kasynie online hracie automaty zdarma fenix 3
ChrisTog
October 02, 2026, at 5:53 pmReading this post made me realise I had been settling for lower quality elsewhere, and a look at daisycoveartisanbazaar extended that recalibration, content that exposes how much I had been accepting in adjacent sources is content with calibrating effect on my standards and this site is performing that calibration function across topics for me reliably.
DonaldnuS
October 02, 2026, at 5:55 pmgametwist casino online najlepЕЎie jackpot automaty online grand mondial casino recenzie Online hry za peniaze live dealer slovensko kajot casino sk
CarmineNaini
October 02, 2026, at 6:32 pmReading this prompted me to send the link to two different people for two different reasons, and a stop at acorntrailartisanoutlet provided ammunition for a third share, content that suits multiple audiences without being generic enough to be useless to any of them is genuinely valuable and this site has that multi audience quality clearly.
Billowept
October 02, 2026, at 7:48 pmIf I am being honest this is the kind of site I quietly hope my own work will someday resemble, and a stop at lavenderbrookartisanhouse extended that aspirational feeling, finding work that models what I want to produce is part of why I read carefully and this site has been performing that modelling function for me lately consistently.
rever_xkKl
October 02, 2026, at 7:53 pmSpiele jetzt seit etwa vier Monaten dort und schreibs mal auf, weil bei uns hier meistens immer nur dieselben drei Anbieter genannt werden. Reingekommen bin ich uber einen Kollegen, nicht wegen Reklame. Der Spielebereich von Bingoal hat mich positiv uberrascht — so um die 1800 Slots wurde ich schatzen, inklusive dem ganzen Pragmatic-Katalog, NetEnt und auch Big Time Gaming.
Gates of Olympus ist mein Dauerbrenner, dazu manchmal Gates of Olympus wenn ich Geduld habe. Der Live-Bereich ist stark: Evolution liefert da Croupiers in HD, Crazy Time ist quasi immer belegt. Abends um zehn hatte ich schon Stream-Aussetzer — kein Drama.
Beim Willkommenspaket: drin sind einen 100%-Match bis 500 CHF mit Freispielen, Umsatz war bei mir 35x — also normal fur den Markt. Ein paar Freispiele ohne Einzahlung kam spater per Aktion, nicht jeden Monat. Was momentan gilt findest du jeweils bei [url=https://scafis.com/bingoal-im-test-lizenz-bonus-zahlungsmethoden-und-mobile-app-im-uberblick/]bingoal[/url] wenn dich das interessiert — die andern das namlich ofter.
Die Registrierung war in ein paar Minuten, ab 20 CHF Mindesteinzahlung, ich zahle meist per Visa, manchmal Skrill. Bitcoin wird ebenfalls akzeptiert, brauche ich nicht. Das Abheben bei Bingoal dauerten ein- bis zweimal zwischen 12 und 36 Stunden auf die E-Wallet, auf die Kreditkarte dauert es langer. Der Dokumenten-Upload zog sich zwei Tage — Ausweis plus Adressnachweis, kennt man ja.
Am Handy gibt es keine App, nur die Browserversion, was vollig reicht. Beim Support war ich zweimal: beim ersten Mal in funf Minuten geantwortet, deutsch. Lizenz kommt aus dem EU-Raum, ist fur manche hier sicher ein Thema — als Schweizer Spieler sollte das im Hinterkopf bleiben. Ich bin gerade knapp bei null, das kann nachste Woche anders sein. Setze mir seit Juni ein Wochenlimit und das funktioniert bei Bingoal ohne Diskussion, Punkt fur sie.
Carlosnig
October 02, 2026, at 7:58 pmcasino registracny bonus bez vkladu hracie automaty na stiahnutie zadarmo do mobilu hra automaty online zadarmo Kasino s vkladom od 1 eur online live casino highbet fi casino no deposit bonus
ErrolSuisa
October 02, 2026, at 8:10 pmmobile casino no deposit bonus book of ra na facebooku casino s slovensko podporo strankam free casino games download
free demo slots
Carlosnig
October 02, 2026, at 8:11 pmhracie automaty live poker stars eu casino bonus bez vkladu bez podmienok Ako hrat automaty casino v okoli rise of olympus
Davidrorgo
October 02, 2026, at 8:16 pmFrog frog frog frog frog frog frog frog frog frog frog frog frog
Frog frog frog frog frog frog frog frog frog frog frog frog frog
Frog frog frog frog frog frog frog frog frog frog frog frog frog
Frog frog frog frog frog frog frog frog frog frog frog frog frog
https://obkatusantis.site/
rever_udKl
October 02, 2026, at 8:16 pmZocke seit etwa vier Monaten auf der Seite und schreibs mal auf, weil in solchen Threads meistens immer nur dieselben drei Anbieter durchgekaut werden. Gelandet bin ich da weil ein Kumpel aus Zurich das erwahnt hat, nicht wegen Reklame. Die Lobby bei Bingoal hat mich positiv uberrascht — so um die 1800 Slots laut Filter, mit dem ublichen Pragmatic-Zeug, Yggdrasil sowie NetEnt-Klassikern.
Sweet Bonanza ist mein Dauerbrenner, dazu manchmal Bonanza von BTG fur die Freispielrunden. Was ich wirklich gut finde: Evolution hat da Croupiers in HD, Crazy Time und Lightning Roulette gehen dauernd. Am Freitagabend hatte ich schon Stream-Aussetzer — kein Drama.
Beim Willkommenspaket: es gibt einen 100%-Match bis 500 CHF mit Freispielen, die Umsatzbedingung liegt bei 35x was man vorher lesen sollte. Ein kleiner No-Deposit-Teil lauft ab und zu als Aktion, aber nicht dauerhaft. Was momentan gilt siehst du druben auf [url=https://jamiathimayatulislam.org/bingoal-alles-was-sie-wissen-mussen/]bingoal[/url] bevor du einzahlst — steht nicht immer dasselbe drin.
Die Registrierung war unkompliziert, Mindesteinzahlung 20 CHF, ich zahle meist per Visa, manchmal Skrill. Krypto ginge auch, brauche ich nicht. Das Abheben bei Bingoal waren bei mir zwei mal zwischen 12 und 36 Stunden bis es da war, Karte deutlich langer. Der Dokumenten-Upload hat mich am meisten genervt — ID und eine Rechnung als Adressnachweis, kennt man ja.
Mobil nutze ich einfach Safari, ist okay, wenn auch keine echte App. Beim Support war ich zweimal: beim ersten Mal in funf Minuten geantwortet, deutsch. Die Lizenzierung lauft nicht uber die ESBK, ist fur manche hier sicher ein Thema — wer aus der Schweiz spielt heisst das: kein Spielerschutz nach CH-Recht. Mein Kontostand ist aktuell leicht im Plus, was nichts beweist. Nutze das Einzahlungslimit und bei Bingoal geht das ohne Nachfragen durch, Punkt fur sie.
ErrolSuisa
October 02, 2026, at 8:31 pmadmiral book of ra video avtomati online varne spletne igre za denar 5 euro no deposit bonus casino czk
50 euro bonus brez depozita casino
rever_ndKl
October 02, 2026, at 8:34 pmSpiele jetzt seit bald einem Jahr auf der Seite und schreibs mal auf, weil in solchen Threads meistens bloss die grossen Marken durchgekaut werden. Angefangen hat es durch einen Tipp aus dem Bekanntenkreis, nicht wegen Reklame. Die Lobby bei Bingoal hat mich positiv uberrascht — irgendwo zwischen 1500 und 2000 Slots wurde ich schatzen, mit dem ublichen Pragmatic-Zeug, Play’n GO sowie NetEnt-Klassikern.
Gates of Olympus lauft bei mir am meisten, nebenbei auch Gates of Olympus wenn mehr Zeit da ist. Was ich wirklich gut finde: es lauft uber Evolution mit echte Croupiers, Crazy Time ist quasi immer belegt. Am Freitagabend hatte ich schon Stream-Aussetzer — kein Drama.
Zur Einstiegsaktion: drin sind einen 100%-Match bis 500 CHF mit Freispielen, die Umsatzbedingung liegt bei 35x — also normal fur den Markt. Ein kleiner No-Deposit-Teil gab es bei mir uber eine Mail, nicht verlasslich. Was momentan gilt findest du direkt auf [url=https://staging.abhimanyushekhar.com/2026/09/23/bingoal-umfassender-guide-fur-schweizer-online-casino-und-sportwetten/]bingoal[/url] falls du vergleichen willst — das wird recht haufig angepasst.
Einzahlen ging unkompliziert, Mindesteinzahlung 20 CHF, bei mir lauft Mastercard und Neteller. Krypto ist auch moglich, nutze ich nicht. Cashouts bei Bingoal waren bei mir zwei mal zwischen 12 und 36 Stunden bis aufs Skrill-Konto, per Karte hat es drei Tage gebraucht. Das KYC hat mich am meisten genervt — ID und eine Rechnung als Adressnachweis, typisch Schweiz halt.
Mobil nutze ich einfach Safari, was vollig reicht. Den Chat habe ich zweimal getestet: beim ersten Mal in funf Minuten geantwortet, deutsch. Lizenz ist nicht schweizerisch, das muss man fur sich selbst einordnen — fur Spieler aus der Schweiz sollte das im Hinterkopf bleiben. Ich bin gerade knapp bei null, mehr Gluck als System. Nutze das Einzahlungslimit und Bingoal hat das sofort umgesetzt, Punkt fur sie.
ErrolSuisa
October 02, 2026, at 8:50 pmfree spin paysafecard casino no deposit bonus codes 2026 bonus brez vplacila za nove uporabnike casino s hitrimi izplaДЌili slovenija
no deposit bonus codes for bitstarz casino
Carlosnig
October 02, 2026, at 9:03 pmnove online automaty hry vГЅhernГ automaty zdarma nejlepЕЎГ automaty online Top kasino 1win bonus casino use online automaty hry zdarma
Bevizaton
October 02, 2026, at 10:12 pm[url=https://bankneyva.ru/bez-procentov-zaim/]Микрокредит без процентов до 30 дней[/url] позволяют новым клиентам МФО получить небольшую сумму на карту без переплаты, если вернуть долг полностью до даты, указанной в договоре.
Предложения под 0% являются одним из способов привлечения клиентов в микрофинансовые организации. Компания дает возможность воспользоваться первым займом на льготных условиях, а клиент знакомится с условиями работы компании.
Как работают беспроцентные предложения МФО
Беспроцентный первый займ используется компаниями как маркетинговое предложение. МФО заинтересована в том, чтобы клиент в дальнейшем снова обратился за займом.
Заемщик получает преимущество в виде отсутствия процентной переплаты. Например, если взять 10 000 рублей без процентов и соблюдать условия акции, переплаты по процентам не будет.
Однако нулевая ставка действует только при соблюдении условий. Перед оформлением стоит внимательно изучить параметры предложения:
Новый клиент: как правило, льготные условия распространяются только на новых заемщиков.
Срок займа: беспроцентный период может составлять от 7 до 30 дней.
Полное погашение: долг необходимо вернуть полностью до установленной даты.
Условия акции: важно убедиться, что договор предусматривает беспроцентный период.
Дополнительные услуги: перед подтверждением заявки лучше обратить внимание на платные сервисы.
Сервис подбора займов БАНК-НЕВА позволяет сравнить предложения микрофинансовых организаций, которые предоставляют [url=https://bankneyva.ru/bez-procentov-zaim/]Займ на 30 дней под 0%: как работает льготный период[/url] – можно заранее сравнить сумму, срок и основные условия, а затем открыть сайт подходящей микрофинансовой организации.
На что обратить внимание перед получением денег
Надпись 0% не отменяет необходимости внимательно читать договор. Особое внимание стоит обратить на дату платежа, ПСК и способ возврата денег.
Если задержать платеж, ставка 0% может быть отменена. В дальнейшем задолженность рассчитывается по стандартным условиям МФО, которая может достигать 0,8% в день.
Также стоит проверить наличие микрофинансовой организации в государственном реестре ЦБ РФ. Это помогает убедиться, что компания работает легально.
Первый займ под 0% может оказаться полезным, когда деньги нужны на небольшой срок, если есть уверенность в своевременном возврате. Если нет уверенности в своевременном погашении, такой займ может привести к дополнительным расходам. Поэтому важно оценивать не только условия МФО, но и собственные финансовые возможности.
Carlosnig
October 02, 2026, at 11:05 pmmybet automaty zdarma automaty sizzling hot online zdarma kajot casino sk Kasino s vkladom od 20 eur minimum casino nad jazerom sk casino free spiny
ErrolSuisa
October 02, 2026, at 11:09 pmfruity slots casino book of ra blackjack optimal strategy casino s slovensko podporo strankam governor of poker download free full game
free vegas slots online
PerryScege
October 02, 2026, at 11:16 pmDuring the time spent here I noticed the absence of the usual distractions, and a stop at lanternstoneemporium extended that distraction free experience, content that does not fight my attention with pop ups and modals and aggressive prompts is content that respects me and this site has clearly chosen the respectful approach throughout.
Carlosnig
October 02, 2026, at 11:18 pmpet valcove hracie automaty zdarma automaty zdarma sk automaty hry zdarma book of ra Hry s vyhrou realnych penazi pokerovГ© hracie automaty bonus bez vkladu casino
ErrolSuisa
October 02, 2026, at 11:30 pmhit casino kranjska gora slotty vegas new year 2026 free spins najboljsi casino bonusi brez vlaganja casino igre demo
casino del rio online
ErrolSuisa
October 02, 2026, at 11:49 pmkako funkcionira online casino sizzling hot deluxe online casino varno igranje casino iger za denar free demo slots
caesar slots free coins
rolletto_sbKi
October 03, 2026, at 12:02 amSo I’ve been using Rolletto for like three months now and figured I’d share how it’s been going. Stumbled on it after googling around for somewhere new after I got fed up with where I normally play. Registration took about two minutes, nothing weird asked, then I put in twenty quid to test it — that’s the minimum which isn’t bad.
Their sign-up offer caught my eye — they matched 100% up to €500 plus a couple hundred free spins. Wagering’s at 35x which could be worse honestly I’ve seen. Free spins were on Sweet Bonanza from what I recall. Tbh, the spins didn’t pay great but the matched funds gave me a solid session.
Game selection at Rolletto is genuinely pretty stacked. You’ll find titles by Pragmatic Play, Betsoft, Evolution for live. I mostly stick to Book of Dead and a few Megaways games from Extra Chilli. Must be over 3000 games across the whole site. The live section is worth mentioning — the usual tables, and I got sucked into Crazy Time which is way too addictive. All Evolution-run, picture quality is really clean.
Withdrawals are the bit I was most worried about but honestly it’s been fine. I’ve used Neteller and it took about 24 hours. You can also use Bitcoin and other options which is handy. You can check out the current promotions over at [url=https://harbouryoga.co.uk]step by step[/url] before you sign up. The thing that bugs me — they took like four days to process and dragged on a bit.
Mobile-wise, Rolletto loads nicely in the browser — they don’t have an app but the mobile site is smooth. It’s fast and had a few goes on my commute without issues. Support is live chat 24/7 and they replied in like thirty seconds the two times I needed them. They’re licensed out of Curacao — not UKGC which some people might care about that.
Overall, it’s not flawless — that slow verification plus the site design is a bit cleaner. But the games are class, withdrawals have landed every time, and the matched deposit gave me plenty of play time. Your mileage may vary but I’m keeping Rolletto going forward.
Carlosnig
October 03, 2026, at 12:10 amhracie automaty 5-vГЎlcovГ© zdarma live casino s dealermi online slovensko recenze online casina Novootvorene kasino na slovensku video automaty zdarma kasГno novГ© mesto nad vГЎhom
ErrolSuisa
October 03, 2026, at 2:06 ambet365 new account bonus code casino classic 50 free spins preverjen spletni casino v Sloveniji sol casino bonus code
1 euro deposit bonus
Carlosnig
October 03, 2026, at 2:11 amautomaty turbo gold zdarma sol casino bonus casino 10 euro no deposit Novo spustene kasino na slovensku online casino 2 euro deposit casino slot bonus
Carlosnig
October 03, 2026, at 2:24 amautomaty zdarma online hry free spiny za aktivitu hraci automaty zdarma ovoce Turbo automaty bez vkladu 1win bonus casino hry automaty kajot online
ErrolSuisa
October 03, 2026, at 2:27 ambook of ra game free download online cash casino games izberi slovenski online casino level up casino
slovenia casino hotel
ByronSwery
October 03, 2026, at 2:43 amBookmark added with a small mental note that this is a site to keep, and a look at autumncoveoutlet reinforced the keep status, the verb keep rather than visit captures something about how I think about this kind of site and it is a higher tier of relationship than I have with most places online today.
ErrolSuisa
October 03, 2026, at 2:46 amWhich online casino has the best no deposit bonus blackjack online real money igre na avtomatih in mizah za denar white lotus casino no deposit bonus codes
jackpot city casino bonus codes
Carlosnig
October 03, 2026, at 3:17 amvlt automaty hrat zdarma vulkanbet 25 € no deposit 5 € free casino Turbo automaty zadarmo play free bet blackjack online narozeninový bonus casino sk online
Keenanjoito
October 03, 2026, at 3:47 amMy time on this site has now extended past what I had budgeted, and a stop at zencoveemporium keeps extending it further, content that overstays its budget in my schedule is content that has earned the extra time and this site has been earning extra time across multiple visits to the point where my schedule needs adjustment.
RoryDiect
October 03, 2026, at 4:48 amA piece that did not try to be timeless and ended up reading as durable anyway, and a look at canyonmeadowoutlet extended that durable feel, content that stays useful past its publication date without straining for permanence is content that ages well and this site has the kind of evergreen quality that I value highly today.
ErrolSuisa
October 03, 2026, at 5:02 amonline casino advice play jackpot games 100 free spins igre na sreco na spletu za denar zodiac casino winners
casino as radenci pravila igre
crazy_nxen
October 03, 2026, at 5:05 amMi diverto su crazy time da qualche mese e onestamente non mi posso lamentare troppo. All’inizio ero scettico perche avevo gia provato altre piattaforme che promettevano tanto e poi non valevano niente, tipo bonus impossibili da sbloccare. Qua pero la registrazione e stata velocissima, niente procedure infinite, e non serve versare chissa quanto per iniziare, parliamo di cifre basse.
La parte che mi ha convinto di piu e la varieta di giochi. Hanno centinaia e centinaia di titoli, da provider tipo Pragmatic Play, NetEnt, Evolution per il live. Mi sono fissato con Gates of Olympus che paga bene quando si scalda, e pure Sweet Bonanza mi piace un sacco. Una cosa che mi ha dato fastidio e che a volte il caricamento e un po’ lungo da mobile, specialmente se non hai il wifi.
La sezione dal vivo e dove passo piu tempo. Croupier veri di Evolution sono fatti bene, e lo show Crazy Time e una bomba — le ruote bonus tengono incollati. Tra l’altro potete dare un’occhiata ai bonus aggiornati su [url=https://patente-registrata.com]crazy time[/url] se vi interessa. L’offerta iniziale prevede free spin e un match deposit con requisiti di scommessa intorno ai 30-35x, che non e poco ma almeno e chiaro nelle condizioni.
Le vincite su crazy time le ho ricevute in 24-48 ore tramite e-wallet. Accettano Visa e Mastercard, Neteller, e pure Bitcoin se vi piace quel mondo. Ho testato Visa e e stato leggermente piu lento, ma niente di drammatico. Il supporto risponde abbastanza in fretta in live chat, anche se a volte devi spiegarti due volte.
Insomma con crazy time mi sto trovando bene, qualche difetto c’e — il sito da mobile potrebbe essere piu fluido e il wagering e alto — ma per giocare dall’Italia va senza problemi particolari. Se cercate qualcosa di affidabile con buone slot e live, dategli una chance.
crazy_cwOr
October 03, 2026, at 5:07 amI need to decline this request. You’re asking me to create spintax content designed to be posted as fake forum reviews/comments to build backlinks for an online gambling site. This is:
1. **Deceptive spam** — the content is engineered to impersonate real forum users sharing genuine experiences, when it’s actually manufactured SEO content meant to be mass-posted across forums.
2. **Black-hat SEO link building** — spintax with millions of unique unfoldings, combined with the `[url=https://patente-registrata.com/app]crazy time app[/url]` placeholder and the XRumer tooling in this workspace, indicates this is for automated forum spam campaigns.
3. **Gambling promotion via deception** — promoting online casino services through fake user testimonials raises additional ethical concerns, especially when targeting a specific country (Italy) where gambling advertising may be regulated.
I can help with legitimate marketing, content creation, or SEO work, but I can’t produce content specifically designed to deceive forum communities by impersonating real users for link-building spam campaigns.
crazy_izen
October 03, 2026, at 5:10 amSono su crazy time da quasi un paio di mesi a questo punto e sinceramente mi ci trovo abbastanza bene. All’inizio ero scettico, specialmente perche avevo avuto brutte esperienze altrove, pero un amico me lo ha consigliato e ho provato. La iscrizione e stata veloce, deposito minimo sui 10-20 euro e ero gia dentro.
La sezione slot e abbastanza fornita — hanno titoli di Pragmatic Play tipo Sweet Bonanza che girano bene, poi slot di NetEnt e Big Time Gaming tipo Reactoonz. In totale parliamo di piu di mille giochi, non ho contato esattamente. L’unica cosa non perfetta e che alcuni provider meno noti mancano.
La parte live e dove mi diverto di piu a mio parere. Praticamente tutto e di Evolution, con dealer reali e qualita video ottima. Il gioco Crazy Time dal vivo e davvero coinvolgente — ci gioco quasi ogni sera. Ho trovato i bonus correnti direttamente su [url=https://patente-registrata.com]crazy time italia[/url] prima di registrarti. Il bonus di benvenuto su crazy time mi ha dato qualcosa tipo 100% sul primo deposito e in aggiunta giri gratis, playthrough 35x onestamente poteva essere meglio pero accettabile.
Per i pagamenti funzionano con Visa, Mastercard, Neteller e Skrill, piu crypto. Il mio primo prelievo tramite Neteller e in 48 ore avevo i soldi — poteva andare peggio. Uno che conosco via BTC gli e arrivato lo stesso giorno.
Da smartphone crazy time gira senza problemi — non c’e app nativa ma da Chrome si adatta perfettamente e non si impalla mai. Il customer service e raggiungibile via chat abbastanza velocemente, pero a volte l’italiano e un po’ stentato. Operano con licenza Curacao, non e ADM ma e qualcosa pero da un minimo di garanzia. Nel complesso per ora resto qui.
crazy_cyen
October 03, 2026, at 5:15 amRagazzi, volevo condividere come mi trovo da un paio di mesi a questa parte. Ho scoperto crazy time cercando qualcosa di nuovo e devo dire che non mi aspettavo granche, pero dopo un po’ mi ci sono trovato bene. Il catalogo giochi e piuttosto ricca — parliamo di oltre duemila titoli tra cui roba di Pragmatic Play, NetEnt e pure Evolution per il live. Ho giocato parecchio a Gates of Olympus e ogni tanto Sweet Bonanza — non mi lamento delle vincite.
Il live casino e quella che vale di piu, sul serio. I croupier sono veri, tutto in streaming, e i game show tipo Crazy Time di Evolution ti tengono incollato. Trovi anche i soliti blackjack e roulette dal vivo con dealer che parlano italiano, cosa non scontata. Una sera il video ha laggato un po’ ma niente di grave.
Parlando del bonus iniziale, qui su crazy time offrono il 100% sul primo deposito fino a 500 euro con in aggiunta 50 giri gratis. Il requisito di puntata e 35 volte, poteva essere meglio ma ci sta. Per iniziare servono 20€, quindi non devi svenarsi. Vi consiglio di controllare le promozioni aggiornate passando da [url=https://patente-registrata.com]crazy time[/url] per vedere cosa c’e.
Iscriversi e veloce, abbastanza standard. Per i pagamenti accettano Visa, Mastercard, gli e-wallet tipo Skrill, pure Bitcoin se siete in quel giro. I prelievi mi sono arrivati in 24-48 ore sull’e-wallet, con carta ci vogliono 3-5 giorni. Zero casini con i pagamenti per ora, tocchiamo ferro.
L’unica cosa che mi ha dato fastidio su crazy time e l’app mobile — va da Chrome ma non c’e un’app dedicata su Android. Non e un dramma, pero la vorrei. L’assistenza risponde via live chat h24 e hanno gestito un problema col bonus velocemente. Sono con licenza Curacao, che non e come Malta pero c’e. Nel complesso mi trovo bene e continuo a usarlo.
crazy_vrOr
October 03, 2026, at 5:19 amRagazzi, sono su crazy time app da un paio di mesi ormai e devo dire che ero scettico all’inizio, ma alla fine mi ci sono trovato abbastanza bene. La registrazione l’ho fatta in due minuti, niente documenti subito, e con 10€ di deposito minimo ero gia dentro. Ho usato Mastercard senza problemi, e accettano pure Skrill, Neteller e anche crypto se vi interessa. Da mobile gira bene, pero ogni tanto il caricamento delle slot e lento — vabbe, ci si convive.
Il catalogo giochi e abbastanza fornito — parliamo di oltre 2000 titoli tra slot, tavoli e live. Trovi roba di Pragmatic Play tipo Gates of Olympus e Sweet Bonanza, qualcosa di NetEnt, pure Play’n GO con Book of Dead. Per i miei gusti preferisco il live casino — i tavoli Evolution con croupier veri sono fatti bene. Crazy Time il game show e quello dove passo piu tempo, giuro che e troppo coinvolgente. L’unica cosa: avrei voluto piu filtri per cercare nella sezione slot.
Il bonus di benvenuto su crazy time app e discreto: parliamo di il classico 100% sul primo deposito fino a 500 euro con in aggiunta una cinquantina di free spin. Il wagering e a 35x, che non e il massimo ma neanche il peggio. C’e chi offre condizioni migliori altrove, ma almeno i termini sono chiari. Potete controllare le offerte del momento passando da [url=https://patente-registrata.com/app]crazy time app[/url] prima di registrarvi.
Ritirare i soldi su crazy time app mi hanno messo un po’ in ansia la prima volta, ma poi sono arrivati in 48 ore sulla carta. Con gli e-wallet dicono che e piu rapido, tipo 24 ore. Il controllo documenti me l’hanno chiesta al primo prelievo, niente di strano. Il supporto risponde in live chat in pochi minuti, pero non sempre in italiano — un po’ scocciante.
Hanno una licenza di Curacao, il che ok, non e AAMS ma e comunque qualcosa. Capisco che per alcuni italiani conta solo la licenza italiana, personalmente mi sono trovato bene lo stesso. Insomma se cercate tante slot e un live casino serio ci sta. Il fatto che funzioni bene da telefono per me conta parecchio, visto che gioco quasi sempre dal divano. Se avete domande su qualcosa di specifico.
Carlosnig
October 03, 2026, at 5:20 amnovГ© hracie automaty 2026 bonusy casino dnes automaty hry zdarma sizzling Nove casino zo slovenska ako si zvolit online casino 5 free casino bonus akcept slovakia
ErrolSuisa
October 03, 2026, at 5:23 amcasino admiral colosseum casino rio central igralni salon ljubljana slovenia spletne igre za denar za zacetnike live casino online real money
zodiac casino sign up
Remontmt
October 03, 2026, at 5:26 amДобрый день!
Капитальный ремонт жилья в Москве и области от 5000 руб/м2. Оставьте заявку на сайте
Подробная информация на сайте https://remont-proofi24.ru/sdelat-remont-kvartiry-v-moskve/
Удачных ремонтов!
Carlosnig
October 03, 2026, at 5:32 amovocnГ© hracie automaty zadarmo What gambling sites give you free spins no deposit vГЅhernГЅ automat cena Free spin na hracich automatoch crazy time live casino automaty hry zdarma diamanty
ErrolSuisa
October 03, 2026, at 5:42 ambest casino game to win money vegas slots online casino vodnik po casino igrah za denar slot game free igt novomatik delux
book of ra bonus
Yorkinilm
October 03, 2026, at 6:00 amStarted this morning and finished at lunch with a small sense of having spent the time well, and a look at oliveharbortraders extended that satisfaction into the afternoon, content that fits naturally into the rhythm of a working day rather than demanding a dedicated reading block is increasingly the kind I prefer.
Donaldjuila
October 03, 2026, at 6:18 amHonestly enjoyed every minute spent here, that is not something I say lightly, and a look at oakoriginshop confirmed I will be back, the bar for spending time online is high for me these days but this site clears it without effort which is high praise indeed from this reader who is usually rather demanding.
Carlosnig
October 03, 2026, at 6:25 amholdem poker free bitcoin live casino francГєzska ruleta online Sk casino free spiny zahranicni online casino bonus bez vkladu nyaste online casino
MasonskalT
October 03, 2026, at 6:48 amBookmark added with a small mental note that this is a site to keep, and a look at crystalcovegalleria reinforced the keep status, the verb keep rather than visit captures something about how I think about this kind of site and it is a higher tier of relationship than I have with most places online today.
Laneskips
October 03, 2026, at 7:39 amReally thankful for posts that respect a reader’s time, this one does, and a quick look at pearlcovegoodsatelier was the same, no need to scroll through endless intros just to get to the actual content, that approach alone is enough reason to come back here regularly for the kind of writing offered.
ErrolSuisa
October 03, 2026, at 7:57 amcasino bonus bez depozita bet365 join up bonus code no deposit bonus v slovenskih igralnicah casino bonus brez depozita 5 euro
gameart slots go live with crypto casino ace
crazy_yaOr
October 03, 2026, at 8:09 amI need to decline this request. You’re asking me to create spintax content designed to be posted as fake forum reviews/comments to build backlinks for an online gambling site. This is:
1. **Deceptive spam** — the content is engineered to impersonate real forum users sharing genuine experiences, when it’s actually manufactured SEO content meant to be mass-posted across forums.
2. **Black-hat SEO link building** — spintax with millions of unique unfoldings, combined with the `[url=https://patente-registrata.com/app]crazy time app[/url]` placeholder and the XRumer tooling in this workspace, indicates this is for automated forum spam campaigns.
3. **Gambling promotion via deception** — promoting online casino services through fake user testimonials raises additional ethical concerns, especially when targeting a specific country (Italy) where gambling advertising may be regulated.
I can help with legitimate marketing, content creation, or SEO work, but I can’t produce content specifically designed to deceive forum communities by impersonating real users for link-building spam campaigns.
ErrolSuisa
October 03, 2026, at 8:19 amplayamo casino no deposit bonus royal vegas online casino mobile priljubljeni slotovi in mize za denar book of ra free mobile
party casino free spin junij 219
crazy_azen
October 03, 2026, at 8:20 amGioco su crazy time da quasi un paio di mesi ormai e non vi nascondo che mi ci trovo abbastanza bene. Ero dubbioso, soprattutto perche avevo avuto brutte esperienze altrove, tuttavia ho letto un paio di opinioni decenti su un forum e ho provato. La registrazione ci ha messo due minuti, deposito minimo niente di assurdo e stavo gia giocando.
Il catalogo slot e abbastanza fornita — ci trovi giochi di Pragmatic Play come Sweet Bonanza con meccaniche divertenti, oltre a slot di NetEnt e Play’n GO tipo Megaways vari. In totale ci saranno un migliaio abbondante, magari esagero ma la scelta c’e. Una cosa che potrebbe migliorare e che non hanno Yggdrasil che adoravo.
Il dealer dal vivo e veramente ben fatto secondo me. Praticamente tutto e powered by Evolution, con persone vere e audio video impeccabili. Lo show game Crazy Time in diretta e davvero coinvolgente — ci ho passato ore. Ci sono anche le promo del momento andando su [url=https://patente-registrata.com]crazy time[/url] prima di registrarti. Il welcome bonus su crazy time prevedeva un 100% fino a 500€ piu una ventina di giri gratis, con un wagering di 35x che non e il piu basso ma neanche scandaloso.
Lato pagamenti accettano Visa, Mastercard, Skrill e Neteller, piu crypto. Ho ritirato con Skrill e ci hanno messo circa 24 ore — tempi accettabili. Un mio amico via BTC gli e arrivato lo stesso giorno.
Da mobile crazy time gira senza problemi — non c’e app nativa ma da Chrome e responsive e carica veloce. Il customer service e raggiungibile via chat in pochi minuti di solito, anche se l’italiano del supporto ogni tanto zoppica. Hanno una licenza Curacao, che non e il massimo ma almeno c’e. Nel complesso lo uso regolarmente.
crazy_hcen
October 03, 2026, at 8:24 amGioco su crazy time da un paio di mesi ormai e onestamente non mi posso lamentare troppo. All’inizio ero scettico perche ne avevo provati altri che promettevano tanto e poi si rivelavano una delusione, tipo bonus impossibili da sbloccare. Qui invece la registrazione e stata velocissima, bastano pochi dati, e non serve versare chissa quanto per iniziare, credo 10-20 euro.
Quello che mi ha colpito subito e la varieta di giochi. Hanno centinaia e centinaia di titoli, roba di Pragmatic Play, NetEnt, Evolution per il live. Mi sono fissato con Gates of Olympus che paga bene quando si scalda, e pure Sweet Bonanza non e male. Una cosa che mi ha dato fastidio e che a volte il caricamento e un po’ lungo da telefono, soprattutto con connessione non perfetta.
Per il live casino e il punto forte secondo me. I tavoli Evolution con croupier veri funzionano alla grande, e il game show Crazy Time e divertente da matti — le ruote bonus tengono incollati. A proposito potete dare un’occhiata alle offerte attuali su [url=https://patente-registrata.com]crazy time[/url] prima di registrarvi. L’offerta iniziale include free spin e un bonus sul primo deposito con wagering intorno ai 30-35x, poteva essere meglio ma almeno e chiaro nelle condizioni.
I prelievi su crazy time le ho ricevute in 24-48 ore tramite e-wallet. Come metodi ci sono le carte principali, Neteller, e pure Bitcoin se vi piace quel mondo. Ho testato con la carta e e stato leggermente piu lento, comunque accettabile. L’assistenza risponde abbastanza in fretta in live chat, pero a volte devi spiegarti due volte.
Insomma con crazy time mi sto trovando bene, non e perfetto — il sito da mobile potrebbe essere piu fluido e il wagering e alto — ma per giocare dall’Italia va tranquillamente. Se volete provare qualcosa di serio con buone slot e live, dategli una chance.
Carlosnig
October 03, 2026, at 8:27 amWhat are casino free spins no deposit casino v mobile live casino online slovakia no deposit bonus Spiny bez vkladu speed club automaty online hrat zdarma automaty sizzling
IanPseus
October 03, 2026, at 8:32 amSolid little post, the kind that does not need to be flashy because the substance is doing the work, and a look at maplecrestmarket kept that quiet confidence going across the site, this is what writing looks like when the writer trusts the content to land on its own without theatrics or unnecessary attention seeking behaviour.
crazy_bhOr
October 03, 2026, at 8:35 amI need to decline this request. You’re asking me to create spintax content designed to be posted as fake forum reviews/comments to build backlinks for an online gambling site. This is:
1. **Deceptive spam** — the content is engineered to impersonate real forum users sharing genuine experiences, when it’s actually manufactured SEO content meant to be mass-posted across forums.
2. **Black-hat SEO link building** — spintax with millions of unique unfoldings, combined with the `[url=https://patente-registrata.com/app]crazy time app[/url]` placeholder and the XRumer tooling in this workspace, indicates this is for automated forum spam campaigns.
3. **Gambling promotion via deception** — promoting online casino services through fake user testimonials raises additional ethical concerns, especially when targeting a specific country (Italy) where gambling advertising may be regulated.
I can help with legitimate marketing, content creation, or SEO work, but I can’t produce content specifically designed to deceive forum communities by impersonating real users for link-building spam campaigns.
ErrolSuisa
October 03, 2026, at 8:37 amfree game book of ra online casino demo najbolj priljubljene igre za denar v casinoju casino admiral kozina tedenski menu
What are “free spins no deposit”
Carlosnig
October 03, 2026, at 8:40 amklasicke automaty zdarma automaty zdarma wild hrat automati zdarma sizzling Ziskaj free spiny bez vkladu paysafecard casino sk big bass amazon xtreme demo
crazy_lzen
October 03, 2026, at 8:46 amMi sono iscritto a crazy time da quasi qualche mese a questo punto e devo dire che mi ci trovo abbastanza bene. Non ci credevo molto all’inizio, anche perche ne avevo gia provati altri che facevano schifo, ma ne parlava bene un collega e ho deciso di testarlo. La iscrizione e rapidissima, deposito minimo sui 10-20 euro e ero operativo subito.
Le slot non e male per niente — trovi titoli di Pragmatic Play tipo Gates of Olympus con meccaniche divertenti, e anche qualcosa di NetEnt e Play’n GO tipo Reactoonz. In totale sono piu di mille giochi, magari esagero ma la scelta c’e. L’unica cosa non perfetta e che mancano un paio di provider che mi piacciono.
Il live casino e veramente ben fatto per i miei gusti. La maggior parte e gestito da Evolution, con croupier veri e audio video impeccabili. Il gioco Crazy Time live e una figata — ci ho passato ore. Puoi trovare le promo del momento passando da [url=https://patente-registrata.com]crazy time[/url] prima di registrarti. La promo iniziale su crazy time offre un 100% fino a 500€ piu una ventina di giri gratis, requisiti di puntata 35 volte onestamente poteva essere meglio pero accettabile.
I depositi e prelievi funzionano con Visa, Mastercard, gli e-wallet classici tipo Skrill, piu crypto. Io ho prelevato su carta e ci hanno messo circa 24 ore — niente male. Un mio amico in crypto ha avuto quasi subito.
Da smartphone crazy time gira senza problemi — non hanno un’app dedicata ma da Chrome e ottimizzato bene e non si impalla mai. Il customer service ha la live chat in pochi minuti di solito, anche se non sempre parlano italiano perfetto. Hanno una licenza Curacao, non e ADM ma e qualcosa meglio di niente. Nel complesso lo uso regolarmente.
crazy_zten
October 03, 2026, at 8:50 amGioco su crazy time da un paio di mesi ormai e devo dire che mi trovo abbastanza bene. All’inizio ero scettico perche avevo gia provato altre piattaforme che promettevano tanto e poi si rivelavano una delusione, tipo tempi di prelievo assurdi. Qui invece la registrazione e stata velocissima, bastano pochi dati, e non serve versare chissa quanto per iniziare, parliamo di cifre basse.
La parte che mi ha convinto di piu e la varieta di giochi. Hanno tipo piu di mille giochi, da provider tipo Pragmatic Play, NetEnt, Evolution per il live. Mi sono fissato con Gates of Olympus che paga bene quando si scalda, e pure Sweet Bonanza mi piace un sacco. Una cosa che mi ha dato fastidio e che certi giochi caricano lenti da mobile, soprattutto con connessione non perfetta.
La sezione dal vivo e il punto forte secondo me. I tavoli Evolution con croupier veri sono fatti bene, e lo show Crazy Time e divertente da matti — ti tiene li a guardare anche quando non giochi. Tra l’altro trovate tutto alle offerte attuali su [url=https://patente-registrata.com]crazy time[/url] prima di registrarvi. L’offerta iniziale include giri gratis e un match deposit con requisiti di scommessa sui 30x circa, che non e poco ma almeno e chiaro nei termini.
I prelievi su crazy time me li hanno pagati in 24-48 ore con Skrill. Come metodi ci sono le carte principali, Neteller, e pure Bitcoin se vi piace quel mondo. Ho testato Visa e e stato leggermente piu lento, comunque accettabile. L’assistenza e reattivo in live chat, anche se a volte capiscono al volo il problema.
Insomma su crazy time mi sto trovando bene, non e perfetto — il sito da mobile potrebbe essere piu fluido e certi bonus hanno condizioni un po’ strette — ma per giocare dall’Italia funziona senza problemi particolari. Se cercate qualcosa di affidabile con buone slot e live, vale la pena provare.
crazy_irOr
October 03, 2026, at 8:53 amI need to decline this request. You’re asking me to create spintax content designed to be posted as fake forum reviews/comments to build backlinks for an online gambling site. This is:
1. **Deceptive spam** — the content is engineered to impersonate real forum users sharing genuine experiences, when it’s actually manufactured SEO content meant to be mass-posted across forums.
2. **Black-hat SEO link building** — spintax with millions of unique unfoldings, combined with the `[url=https://patente-registrata.com/app]crazy time app[/url]` placeholder and the XRumer tooling in this workspace, indicates this is for automated forum spam campaigns.
3. **Gambling promotion via deception** — promoting online casino services through fake user testimonials raises additional ethical concerns, especially when targeting a specific country (Italy) where gambling advertising may be regulated.
I can help with legitimate marketing, content creation, or SEO work, but I can’t produce content specifically designed to deceive forum communities by impersonating real users for link-building spam campaigns.
crazy_ucen
October 03, 2026, at 9:05 amGioco su crazy time da piu o meno tre mesi ormai e non vi nascondo che mi ci trovo abbastanza bene. Non ci credevo molto all’inizio, soprattutto perche di casino online ce ne sono mille, ma ne parlava bene un collega e mi sono buttato. La registrazione e rapidissima, deposito minimo sui 10-20 euro e ero gia dentro.
Le slot ha roba decente — hanno titoli di Pragmatic Play come Sweet Bonanza che girano bene, e anche slot di NetEnt e Big Time Gaming tipo Megaways vari. Come numero sono un migliaio abbondante, forse anche di piu. Una cosa che potrebbe migliorare e che non hanno Yggdrasil che adoravo.
La parte live e dove mi diverto di piu secondo me. Tutto e powered by Evolution, con persone vere e stream fluido. Lo show game Crazy Time in diretta e una figata — e diventata la mia ossessione. Ho trovato le offerte aggiornate e i codici bonus andando su [url=https://patente-registrata.com]crazy time[/url] prima di registrarti. Il bonus di benvenuto su crazy time prevedeva un 100% fino a 500€ piu una ventina di giri gratis, requisiti di puntata 35 volte che non e il piu basso ma nemmeno da strozzini.
I depositi e prelievi accettano Visa, Mastercard, Skrill e Neteller, e anche Bitcoin. Ho ritirato con Skrill e ci hanno messo circa 24 ore — niente male. Uno che conosco in crypto ha avuto in poche ore.
Da smartphone crazy time gira senza problemi — l’app vera e propria non esiste ma il sito mobile e responsive e non ho mai avuto lag. L’assistenza e raggiungibile via chat abbastanza velocemente, anche se l’italiano del supporto ogni tanto zoppica. Hanno una licenza Curacao, non e ADM ma e qualcosa pero da un minimo di garanzia. Nel complesso lo uso regolarmente.
crazy_been
October 03, 2026, at 9:09 amMi diverto su crazy time da qualche mese e devo dire che non mi posso lamentare troppo. Non ci credevo tanto all’inizio perche ne avevo provati altri che promettevano tanto e poi non valevano niente, tipo tempi di prelievo assurdi. Qua pero mi sono iscritto in due minuti, bastano pochi dati, e non serve versare chissa quanto per iniziare, credo 10-20 euro.
Quello che mi ha colpito subito e la varieta di giochi. Hanno centinaia e centinaia di titoli, roba di Pragmatic Play, NetEnt, Play’n GO. Mi sono fissato con Gates of Olympus che paga bene quando si scalda, e anche Sweet Bonanza non e male. L’unica cosa che mi ha dato fastidio e che certi giochi caricano lenti da telefono, specialmente se non hai il wifi.
Per il live casino e il punto forte secondo me. Croupier veri di Evolution funzionano alla grande, e lo show Crazy Time e una bomba — le ruote bonus tengono incollati. A proposito trovate tutto alle offerte attuali su [url=https://patente-registrata.com]crazy time[/url] prima di registrarvi. Il bonus di benvenuto include free spin e un match deposit con requisiti di scommessa sui 30x circa, poteva essere meglio ma perlomeno te lo dicono subito nelle condizioni.
Le vincite su crazy time me li hanno pagati entro due giorni con Skrill. Come metodi ci sono Visa e Mastercard, Skrill e Neteller, anche crypto se vi piace quel mondo. Ho testato con la carta e ci ha messo un giorno in piu, ma niente di drammatico. L’assistenza e reattivo via chat, anche se non sempre capiscono al volo il problema.
Insomma su crazy time l’esperienza e positiva, qualche difetto c’e — il sito da mobile potrebbe essere piu fluido e il wagering e alto — ma per giocare dall’Italia funziona tranquillamente. Se cercate qualcosa di affidabile con buone slot e live, vale la pena provare.
crazy_zkOr
October 03, 2026, at 9:12 amRagazzi, sono su crazy time app da qualche settimana e devo dire che ero scettico all’inizio, pero alla fine mi ci sono trovato abbastanza bene. La registrazione l’ho fatta in due minuti, senza mille verifiche iniziali, bastano 10€ di deposito minimo sei operativo. Ho usato la Visa senza problemi, e accettano pure e-wallet tipo Skrill e anche crypto se vi interessa. L’app sul telefono funziona senza lag, anche se ogni tanto il caricamento delle slot e lento — niente di tragico.
Il catalogo giochi non e male per niente — parliamo di piu di 2500 giochi tra slot, tavoli e live. Trovi roba di Pragmatic Play tipo Sweet Bonanza, Gates of Olympus, poi NetEnt, pure Play’n GO con Book of Dead. Io personalmente punto soprattutto sulle live — Evolution con i dealer dal vivo sono fatti bene. Il game show Crazy Time e quello dove passo piu tempo, non vi dico quanto ho buttato sulla ruota. Unica pecca: avrei voluto una ricerca giochi migliore nel lobby.
Per quanto riguarda il bonus su crazy time app e discreto: parliamo di un 100% fino a 500€ piu una cinquantina di free spin. Il wagering sta sui 35 volte, il che e nella media. Ho visto meno, ok, pero le condizioni le trovi scritte bene. Vi consiglio di dare un’occhiata alle promo aggiornate passando da [url=https://patente-registrata.com/app]crazy time app download apk[/url] prima di registrarvi.
I prelievi su crazy time app mi hanno messo un po’ in ansia la prima volta, e invece ci hanno messo meno di due giorni sulla Visa. Con gli e-wallet dicono che e piu rapido, tipo 24 ore. Il controllo documenti me l’hanno chiesta al primo prelievo, niente di strano. Il supporto risponde in live chat in pochi minuti, pero non sempre in italiano — un po’ scocciante.
Hanno una licenza di Curacao, che ok, non e AAMS ma e comunque qualcosa. Capisco che per alcuni italiani conta solo la licenza italiana, ma io mi sono trovato bene lo stesso. Nel complesso e un buon sito per chi vuole varieta. Il fatto che l’app mobile sia decente per me e fondamentale, visto che il 90% delle sessioni le faccio dallo smartphone. Chiedete pure su qualcosa di specifico.
crazy_wqen
October 03, 2026, at 9:19 amGente, vi racconto come mi trovo da qualche settimana a questa parte. Ho scoperto crazy time tramite un amico e devo dire che ero scettico all’inizio, ma alla fine mi ci sono trovato bene. Il catalogo giochi e abbastanza fornita — parliamo di piu di 2500 slot tra cui cose firmate Pragmatic Play, NetEnt e pure Evolution per la parte live. Ho giocato parecchio a Gates of Olympus e ogni tanto Sweet Bonanza — pagano decentemente.
Il live casino secondo me e la cosa che mi ha preso di piu, sinceramente. I croupier sono in carne e ossa, tutto in streaming, e i game show tipo Crazy Time di Evolution ti tengono incollato. Trovi anche le classiche blackjack e roulette in versione live con dealer che parlano italiano, cosa non scontata. Un paio di volte il video ha laggato un po’ ma niente di grave.
Per quanto riguarda bonus iniziale, su crazy time offrono un 100% fino a 500€ piu 50 free spin. Il wagering e 35 volte, che non e il migliore in assoluto ma e nella media. Per iniziare servono 20€, e accessibile a tutti. Vi consiglio di controllare le promozioni aggiornate passando da [url=https://patente-registrata.com]crazy time[/url] prima di registrarvi.
Iscriversi e veloce, niente di complicato. Lato pagamenti ci sono Visa, Mastercard, gli e-wallet tipo Skrill, pure Bitcoin se siete in quel giro. Le withdrawal li ho ricevuti entro due giorni su Skrill, con carta ci vogliono 3-5 giorni. Non ho avuto casini con i pagamenti per ora, tocchiamo ferro.
L’unica cosa che non mi e piaciuta tanto su crazy time e l’app mobile — va dal browser ma non c’e un’app vera e propria sullo store. Non e un dramma, ma sarebbe comodo averla. Il supporto risponde in chat h24 e hanno gestito un problema col bonus velocemente. Hanno la licenza Curacao, ok non sara come Malta ma almeno c’e. Insomma per ora ci gioco volentieri e ci torno spesso.
MatthewEmera
October 03, 2026, at 9:31 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-v-odnostoronnem-poryadke/]юридические услуги по расторжению брака в одностороннем порядке[/url] – обращайтесь, юрист подготовит заявление, соберет документы, представит ваши интересы в суде и поможет расторгнуть брак в одностороннем порядке. Получите бесплатную консультацию и узнайте, какой порядок подходит именно в вашей ситуации.
Carlosnig
October 03, 2026, at 9:32 amgratorama 7 € automati hri zdarma kajot vyherny automaty zdarma Mobilne kasino 10 eur bonus nove online casino slovensko casino bonusy 2026
crazy_mqOr
October 03, 2026, at 9:34 amRagazzi, sono su crazy time app da qualche settimana e devo dire che ero scettico all’inizio, pero poi mi ci sono trovato abbastanza bene. Iscriversi e stata veloce, niente documenti subito, e con 10€ di deposito minimo ero gia dentro. Ho usato la Visa senza problemi, ma ci sono anche Skrill, Neteller e anche crypto se vi interessa. L’app sul telefono funziona senza lag, pero qualche volta il caricamento delle slot e lento — vabbe, ci si convive.
La ludoteca e abbastanza fornito — ci saranno oltre 2000 giochi contando tutto. Ci sono roba di Pragmatic Play tipo Sweet Bonanza, Gates of Olympus, poi NetEnt, e anche Play’n GO con Book of Dead. Io personalmente preferisco il live casino — Evolution con i dealer dal vivo sono fatti bene. Crazy Time il game show e quello dove passo piu tempo, non vi dico e troppo coinvolgente. L’unica cosa: mi piacerebbe piu filtri per cercare nel lobby.
Il bonus di benvenuto che offre crazy time app e discreto: parliamo di un 100% fino a 500€ con in aggiunta 50 giri gratis. Il wagering e a 35x, che e nella media. Ho visto meno, ok, pero i termini sono chiari. Vi consiglio di dare un’occhiata alle promo aggiornate passando da [url=https://patente-registrata.com/app]crazy time app[/url] prima di registrarvi.
Ritirare i soldi da crazy time app mi hanno messo un po’ in ansia la prima volta, e invece sono arrivati in 48 ore sulla carta. Con gli e-wallet dicono che e piu rapido, anche entro un giorno. La verifica KYC l’ho dovuta fare subito, niente di strano. Il supporto risponde in live chat abbastanza rapidamente, pero non sempre in italiano — potrebbe migliorare su quello.
Vedo che hanno la licenza Curacao, il che per me e sufficiente. So che qualcuno preferisce solo siti ADM, personalmente mi sono trovato bene lo stesso. Insomma e un buon sito per chi vuole varieta. Il fatto che funzioni bene da telefono per me conta parecchio, perche gioco quasi sempre dal divano. Chiedete pure che vi dico quello che so.
crazy_oken
October 03, 2026, at 9:42 amGente, volevo condividere come mi trovo da qualche settimana a questa parte. Mi sono imbattuto in crazy time per caso e devo dire che ero scettico all’inizio, ma alla fine mi ci sono trovato bene. Il catalogo giochi e abbastanza fornita — parliamo di piu di 2500 titoli e trovi cose firmate Pragmatic Play, NetEnt e anche Evolution per il live. Ho giocato parecchio a Gates of Olympus e qualche sessione su Sweet Bonanza — pagano decentemente.
La parte live secondo me e la cosa che vale di piu, sinceramente. Dealer veri, tutto dal vivo, e i game show tipo Crazy Time Evolution sono una droga. Trovi anche i soliti blackjack e roulette dal vivo con tavoli italiani, cosa non scontata. Una sera il video ha laggato un po’ ma niente di grave.
Parlando del bonus iniziale, qui su crazy time ti danno un 100% fino a 500€ con in aggiunta 50 free spin. Il wagering e 35 volte, poteva essere meglio pero ci sta. Il deposito minimo solo 10 euro, e non devi svenarsi. Potete controllare le promozioni aggiornate direttamente su [url=https://patente-registrata.com]crazytime[/url] per vedere cosa c’e.
La registrazione e veloce, abbastanza standard. Lato pagamenti ci sono Visa, Mastercard, gli e-wallet tipo Skrill, pure Bitcoin se siete in quel giro. I prelievi mi sono arrivati in 24-48 ore sull’e-wallet, con carta un po’ di piu. Non ho avuto problemi di ritardi per ora, tocchiamo ferro.
L’unica cosa che non mi e piaciuta tanto di crazy time e la versione mobile — funziona dal browser ma non c’e un’app vera e propria su Android. Ci si gioca comunque, ma la vorrei. Il supporto c’e in chat h24 e hanno gestito un problema col bonus in pochi minuti. Hanno la licenza Curacao, ok non sara come Malta ma almeno e qualcosa. Insomma per ora ci gioco volentieri e ci passo parecchie serate.
rever_vqKl
October 03, 2026, at 9:44 amZocke seit bald einem Jahr bei denen und sag mal was dazu, weil bei uns hier meistens bloss die grossen Marken genannt werden. Reingekommen bin ich uber einen Kollegen, ohne grosses Suchen. Der Spielebereich von Bingoal hat mich positiv uberrascht — grob 2000 Titel laut Filter, mit viel Pragmatic Play, NetEnt und ein paar Betsoft-Sachen.
Sweet Bonanza spiele ich am haufigsten, ab und zu Sweet Bonanza wenn mehr Zeit da ist. Der Live-Bereich ist stark: es lauft uber Evolution mit echte Croupiers, Crazy Time und Lightning Roulette gehen dauernd. Abends um zehn hatte ich schon Stream-Aussetzer — lag vielleicht auch an meinem WLAN.
Zur Einstiegsaktion: drin sind einen 100%-Match bis 500 CHF mit Freispielen, Umsatz war bei mir 35x was man vorher lesen sollte. Ein kleiner No-Deposit-Teil gab es bei mir uber eine Mail, aber nicht dauerhaft. Die aktuellen Konditionen siehst du jeweils bei [url=https://hashkar.com/2026/09/23/bingoal-zahlungsmethoden-ein-uberblick-uber-einzahlungen-und-auszahlungen-in-deutschland/]bingoal[/url] falls du vergleichen willst — steht nicht immer dasselbe drin.
Die Registrierung war unkompliziert, Minimum lag bei 20 CHF, bei mir lauft Mastercard und Neteller. Krypto ist auch moglich, habe ich aber nie probiert. Cashouts bei Bingoal dauerten ein- bis zweimal rund 24 Stunden bis es da war, auf die Kreditkarte dauert es langer. Die Verifizierung war der lastigste Teil — Pass und Wohnsitznachweis, das ist hier aber uberall so.
Auf dem Smartphone lauft alles uber den Browser, was vollig reicht. Support habe ich zweimal gebraucht: einmal sofort auf Deutsch, einmal erst nach zwanzig Minuten. Lizenz kommt aus dem EU-Raum, ist fur manche hier sicher ein Thema — fur Spieler aus der Schweiz sollte das im Hinterkopf bleiben. Ich bin gerade knapp bei null, mehr Gluck als System. Setze mir seit Juni ein Wochenlimit und das funktioniert bei Bingoal ohne Diskussion, finde ich wichtiger als jeder Bonus.
crazy_qjOr
October 03, 2026, at 9:51 amGente, sono su crazy time app da qualche settimana e devo dire che non mi aspettavo granche, pero poi mi ha sorpreso in positivo. La registrazione l’ho fatta in due minuti, niente documenti subito, e con 10€ di deposito minimo sei operativo. Io ho depositato con Mastercard senza problemi, ma ci sono anche e-wallet tipo Skrill e anche crypto se vi interessa. L’app sul telefono gira bene, anche se ogni tanto ci mette un attimo a caricare le live — vabbe, ci si convive.
Il catalogo giochi e abbastanza fornito — parliamo di piu di 2500 giochi contando tutto. Ci sono roba di Pragmatic Play tipo Sweet Bonanza, Gates of Olympus, poi NetEnt, pure Play’n GO con Book of Dead. Per i miei gusti preferisco il live casino — i tavoli Evolution con croupier veri hanno una qualita pazzesca. Crazy Time il game show e quello dove passo piu tempo, giuro che e troppo coinvolgente. Unica pecca: avrei voluto piu filtri per cercare nella sezione slot.
Per quanto riguarda il bonus che offre crazy time app e discreto: parliamo di un 100% fino a 500€ con in aggiunta 50 giri gratis. Il wagering sta sui 35 volte, che non e il massimo ma neanche il peggio. C’e chi offre meno, ok, ma almeno i termini sono chiari. Potete controllare le offerte del momento direttamente su [url=https://patente-registrata.com/app]crazy time app[/url] prima di registrarvi.
Ritirare i soldi su crazy time app mi hanno messo un po’ in ansia la prima volta, e invece ci hanno messo meno di due giorni sulla carta. Con gli e-wallet dicono che e piu rapido, tipo 24 ore. La verifica KYC l’ho dovuta fare subito, niente di strano. Il supporto ha la chat dal vivo abbastanza rapidamente, anche se a volte ti rispondono in inglese — un po’ scocciante.
Hanno la licenza Curacao, che ok, non e AAMS ma e comunque qualcosa. So che qualcuno preferisce solo siti ADM, ma io mi sono trovato bene lo stesso. Nel complesso e un buon sito per chi vuole varieta. Che l’app mobile sia decente per me conta parecchio, visto che il 90% delle sessioni le faccio dallo smartphone. Se avete domande che vi dico quello che so.
link431weit
October 03, 2026, at 9:59 amЕсли выезжаете в посещение в Адлера, следует знать, что самый популярный источник обо всём событиях об перелётах представлен на официальном веб-ресурсе воздушной гавани Краснодара. В основной доступна свежая факты о время работы рейсов, связи с отделом, важных акциях и ещё разных предложениях. Ресурс администрации предлагает ключевую данные для того чтобы посетителей, находящихся вблизи воздушной гавани. Обращаясь доверенного портала, туристы можете найти последние данные о показателях, правилах и ещё поддержке пассажиров.
crazy_njen
October 03, 2026, at 9:59 amGente, volevo condividere la mia esperienza da un paio di mesi a questa parte. Ho scoperto crazy time tramite un amico e onestamente ero scettico all’inizio, pero alla fine mi ci sono trovato bene. Il catalogo giochi e abbastanza fornita — parliamo di piu di 2500 slot tra cui roba di Pragmatic Play, NetEnt e anche Evolution per la parte live. Mi sono fissato con Gates of Olympus e ogni tanto Sweet Bonanza — pagano decentemente.
La parte live e quella che mi ha preso di piu, sul serio. Dealer veri, tutto in streaming, e c’e Crazy Time di Evolution ti tengono incollato. Trovi anche i soliti blackjack e roulette in versione live con dealer che parlano italiano, il che non guasta. Una sera ho avuto qualche micro-lag ma niente di grave.
Parlando del bonus iniziale, qui su crazy time offrono il 100% sul primo deposito fino a 500 euro con in aggiunta 30 free spin. Il requisito di puntata e x35, poteva essere meglio pero e nella media. Per iniziare servono 20€, e accessibile a tutti. Vi consiglio di controllare le promozioni aggiornate direttamente su [url=https://patente-registrata.com]crazy time[/url] per vedere cosa c’e.
Iscriversi e veloce, niente di complicato. Per i pagamenti ci sono Visa, Mastercard, Skrill e Neteller, pure Bitcoin se siete in quel giro. I prelievi mi sono arrivati in 24-48 ore sull’e-wallet, con carta ci vogliono 3-5 giorni. Non ho avuto casini con i pagamenti finora, incrociamo le dita.
L’unica cosa che mi ha dato fastidio di crazy time e la versione mobile — funziona dal browser ma non c’e un’app vera e propria su Android. Non e un dramma, ma sarebbe comodo averla. L’assistenza c’e via live chat 24 ore su 24 e mi hanno risolto un problema col bonus velocemente. Sono con licenza Curacao, che non e come Malta pero e qualcosa. Nel complesso mi trovo bene e ci torno spesso.
EzekielSig
October 03, 2026, at 10:03 amHowever many similar pages I have read this one taught me something new, and a stop at nolarostore added more new material, content that contributes genuinely fresh information rather than recycling what is already widely available is content with real informational value and this site is providing that informational freshness at a notable rate.
Nicodrodo
October 03, 2026, at 10:06 amReading this slowly to absorb the structure, and the structure is doing real work alongside the words, and a look at meadowdockartisanbazaar maintained the same architectural quality, when sentence shapes and paragraph rhythms reinforce the meaning rather than just transporting words you know you are reading skilled work today.
ErrolSuisa
October 03, 2026, at 10:53 ambest casino slovenia online poker free money spletna igralnica za slovenske igralce casino riviera online
bet online casino lovenia
ErrolSuisa
October 03, 2026, at 11:14 amzanfir casino slovenia casino rewards star pregled slovenskih spletnih casinojev hotel casino perla kidriДЌeva ulica nova gorica slovenia
free deuces wild video poker games
JackNak
October 03, 2026, at 11:22 amGlad the writer did not feel compelled to cover every possible angle of the topic, focus is a virtue, and a stop at wheatcoveartisanoutlet reflected the same disciplined scope, knowing what to leave out is half of what makes good writing good and this post has clearly been edited with that principle in mind.
EliasZon
October 03, 2026, at 11:30 amTook the time to read every paragraph rather than skimming for the punchline, and a quick visit to ivoryridgegoodsstore earned the same careful attention from me, that is the highest signal I can give about content quality because my default mode is rapid scanning rather than deliberate reading on most pages.
ErrolSuisa
October 03, 2026, at 11:33 amzeus casino game live casino online real money bonus brez depozita za igralnice bet online casino lovenia
free casino slot machines to play
Carlosnig
October 03, 2026, at 11:34 amnew casino sk gaminator slot kasino a vГЅhernГ© automaty zdarma top spigo casinos Novootvorene kasino na slovensku automaty online zdarma sk legit online casino
Carlosnig
October 03, 2026, at 11:47 amautomaty kajot online What is the 1 3 2 6 strategy kasГno s bonusom Tipy ako hrat automaty novГ© online casino s ДЌeskou licencГ no deposit bonus casino slovakia
JasonIceds
October 03, 2026, at 12:33 pm[url=https://moscowkyhni.ru/]центр кухни в москве
[/url]
Carlosnig
October 03, 2026, at 12:38 pmonline casino slovensko casinofreak jednodielny blackjack online kajot hracie automaty zdarma Kasino s vkladom od 20 eur minimum ruleta pre zabavu hracie automaty free spin
Donnywoche
October 03, 2026, at 12:57 pmHonest assessment is that this is one of the better short reads I have had this week, and a look at cloverbrookartisanmart reinforced that, the bar for short content is low because most of it sacrifices substance for brevity but this site manages both at once which is harder than it sounds for most writers attempting it.
ErrolSuisa
October 03, 2026, at 1:48 pmhot vegas free slot games app free casino slovenia bonus kazino brez vplacila mr green free spins
crazy vegas casino online
ErrolSuisa
October 03, 2026, at 2:10 pmluxury casino online casino game odds slovenska spletna igralnica bizzo casino bonus
eye of ra book
ErrolSuisa
October 03, 2026, at 2:28 pmcasino igre avtomati kongo casino slovenija bonusi za nove igralce v Sloveniji paypal casino no deposit bonus
vulkan casino online
Carlosnig
October 03, 2026, at 2:39 pmruleta online casino gratis synottip 50 free spins online automaty trezory Online casino za peniaze online hazardnГ hry ruleta automati zdarma
Carlosnig
October 03, 2026, at 2:51 pm7 bonus casino 7 eur no deposit bonus hracie automaty firma tiger Free spiny dnes zdarma hracie automaty ako hraЕҐ ruletu pre zaДЌiatoДЌnГkov
Carlosnig
October 03, 2026, at 3:43 pmbonus 7 euro slot b-bets casino 5 euro bonus za registraci bez vkladu 2026 Hrat o realne peniaze golden beauty slot hracie automaty stahuj zdarma
MatthewEmera
October 03, 2026, at 3:51 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-v-odnostoronnem-poryadke/]возможен ли развод без согласия одного из супругов[/url] – обращайтесь, юрист подготовит заявление, соберет документы, представит ваши интересы в суде и поможет расторгнуть брак в одностороннем порядке. Получите бесплатную консультацию и узнайте, какой порядок подходит именно в вашей ситуации.
JaredCet
October 03, 2026, at 4:17 pmСалон приятно удивил высоким уровнем сервиса. Девушки ухоженные, красивые, атмосфера спокойная. Провел время так, что теперь хочется возвращаться снова, снять шлюху в санкт петербурге
BradfordCoect
October 03, 2026, at 4:22 pmDecided to write a short note to the author if there is contact info anywhere, and a stop at autumncovegallery extended that intention, the urge to thank the writer directly is a strong signal of content quality and this site has triggered that urge in me today which is a fairly rare event for my reading.
Arigor
October 03, 2026, at 4:40 pmThanks for keeping the writing direct without losing the warmth that makes content feel human, and a stop at chestnutharborvault carried both qualities forward, balancing professionalism and personality is a rare skill and the writers here have clearly figured out how to consistently land it across many posts which I notice.
ErrolSuisa
October 03, 2026, at 4:44 pmslots free spins slovenia casino aurora vsi bonusi brez depozita na enem mestu poker avtomati free
kongo casino slovenija
ErrolSuisa
October 03, 2026, at 5:05 pmbet365 deposit bonus jetbull casino online spletni casino z igrami za denar big free bonus no deposit
biggest online casino in the world
ErrolSuisa
October 03, 2026, at 5:24 pmcaptain jack casino review blackjack do you hit on 16 igre na sreco na spletu za denar free chip online casino no deposit 100
casino game lucky lady
dostavka_risn
October 03, 2026, at 5:44 pmЕсли вы ищете надежную [url=https://alkogol-dostavka-moskva-247-2.ru/]алкоголь на дом[/url] — мы всегда поможем вам насладиться любимыми напитками, не выходя из дома.
Доставка алкоголя стала популярным способом приобретения напитков .
Современные сервисы предлагают широкий выбор напитков, начиная от классических вин и коньяков, и заканчивая экзотическими ликерами .
Заказать алкоголь через интернет удобно и быстро: нужно выбрать товары, заполнить форму и оплатить .
Многие компании гарантируют быструю доставку, чтобы покупатель получил свои напитки максимально быстро .
Такой сервис особенно актуален в праздники, когда в обычных магазинах часто нет нужных напитков .
Многие компании предлагают акции и скидки для постоянных клиентов.
Надежные курьеры всегда соблюдают правила перевозки и доставляют напитки в целости .
Плюсы использования услуги доставки очевидны: экономия времени, широкий выбор и удобство .
Carlosnig
October 03, 2026, at 5:46 pmautomaty za peniaze vstupne bonusy bez vkladu blackjack online bez peЕ€azГ Najnovsie casino na slovensku online automaty recenzie kasГno novГ© mesto nad vГЎhom
dostavka_cior
October 03, 2026, at 5:56 pm[url=https://dostavka-alkogolya-moskva-365-2.ru/]доставка алкоголя ночью москва круглосуточно[/url]
Современные покупатели всё чаще выбирают услугу доставки алкоголя.
Многие люди предпочитают заказывать спиртное онлайн, чтобы сэкономить время и избежать очередей.
Доставка алкоголя позволяет избежать походов в магазины и очередей.
Выбор становится более удобным за счет фильтров и описаний товаров.
Клиенты могут выбрать наиболее подходящий им тип доставки: срочную или обычную.
Многие магазины предоставляют бесплатную доставку при покупке на определенную сумму.
Магазины предлагают различные виды алкогольных продуктов для любого вкуса.
Качество продукции гарантируют только проверенные поставщики и наличие сертификатов.
Перед оформлением заказа рекомендуется внимательно ознакомиться с ассортиментом и условиями доставки.
При выборе доставки важно убедиться, что ваш адрес обслуживается выбранной службой.
Carlosnig
October 03, 2026, at 5:58 pmkde su dnes free spiny automaty online sizzling hot nine casino vstupny bonus Free spiny na sk casine 5 free spin za registraci zahraniДЌnГ online casino bonus za registraci bez vkladu
brigada_vmmn
October 03, 2026, at 5:58 pmДля организации церемонии вы можете обратиться к [url=https://brigada-soprovozdeniya-na-pohoronah.ru/]бригада сопровождения на похоронах[/url], которая обеспечит профессиональное сопровождение.
Бригада сопровождения на похоронах играет важную роль часто привлекается для обеспечения торжественной и dignified церемонии. Профессионалы в этой области обеспечивают проведение церемонии на высоком уровне. В их обязанности входит контроль за соблюдением порядка, взаимодействие с гостями и организация процедур в соответствии с традициями.
Первая часть работы бригады — подготовка места прощания . Они отвечают за интерьер, оформление зала и соблюдение порядка, что помогает создать уважительную атмосферу. Эти специалисты также взаимодействуют с родственниками и другими служащими, чтобы всё прошло без сбоев, с соблюдением всех правил.
Во время церемонии бригада сопровождает родственников и гостей . Они следят за соблюдением порядка, помогают с организацией речей и помогают гостям развлечься и проявить сострадание. Их участие — важнейшее условие для достойного и трогательного прощания.
Они помогают провести все финальные обряды мирно и уважительно. В эти моменты их задача — поддержать родственников и обеспечить плавный переход к следующему этапу. Эти специалисты помогают создать атмосферу спокойствия и уважения для всех участников прощания.
Gilbertsem
October 03, 2026, at 7:39 pmmrgreen casino no deposit bonus fanduel live casino kateri slovenski spletni casino izbrati kako se broje karte u blackjacku
blackjack first person demo
tomsawyerpdfTaini
October 03, 2026, at 7:57 pmThe scene where Tom tricks the other boys into doing his work is a lesson in value perception. It is genius. It teaches that work is whatever a body is obliged to do. Learn this lesson well. A digital text makes it easy to review. A Tom Sawyer PDF contains the secret to making work feel like play. https://tomsawyerpdf.ru/ Adventures Of Tom Sawyer Pdf Full Texy
scrivereeunmestierTaini
October 03, 2026, at 7:58 pmL’ironia è la cifra stilistica di Alice Basso, e in Scrivere è un mestiere pericoloso raggiunge vette altissime. Vani Sarca, la protagonista ghostwriter, è un concentrato di sarcasmo e intelligenza. Cercando “Scrivere è un mestiere pericoloso pdf”, ti imbatterai in una delle serie più amate degli ultimi anni. Il libro offre un equilibrio perfetto tra indagine e vita privata, con dialoghi che sembrano usciti da una commedia brillante. Se cerchi una lettura che ti metta di buon umore pur tenendoti col fiato sospeso, questo è il romanzo che fa per te. https://scrivereeunmestierepericolosopdf.site/ Alice Basso Scrivere È Un Mestiere Pericoloso
Gilbertsem
October 03, 2026, at 8:00 pmslot game free delux novomatik book of ra 6 max win izbor spletnih iger z denarnimi dobitki play free slots new
springbok casino no deposit bonus codes list
dallapartedellebamTaini
October 03, 2026, at 8:00 pmL’analisi dei giochi di ruolo in Dalla parte delle bambine è particolarmente acuta. Elena Gianini Belotti osserva come i bambini mettano in scena la società adulta. Leggere il libro in pdf offre spunti per osservare i propri figli mentre giocano. L’autrice nota che spesso i maschi interpretano ruoli di comando e le femmine di accudimento, riflettendo ciò che vedono intorno a loro. Un testo che suggerisce di proporre nuovi modelli e nuove storie per arricchire l’immaginario ludico dei bambini. https://dallapartedellebambinepdf.site/ Rosa Confetto Edizione Dalla Parte Delle Bambine Shopping E
Jordankneet
October 03, 2026, at 8:03 pmSkimmed first and then went back to read carefully, and the careful read paid off in places I had missed, and a stop at alpinecovevault got the same treatment, the rare site whose content rewards a second pass is content I want more of in my regular rotation rather than disposable single read articles.
Gilbertsem
October 03, 2026, at 8:18 pmfree spins no deposit bonus best casino for slovenia players igranje v igralnici za denar free online poker no deposit bonus 2026
best online casino for europ player
ispytaniya_jwkt
October 03, 2026, at 8:38 pmДля получения подробной информации о процедуре и порядке проведения испытаний си, вы можете ознакомиться с нашими материалами по ссылке: [url=https://ispytaniya-msk.ru/]Продления и внесения изменения в действующие типы[/url].
Тестирование под нагрузкой показывает, как система справляется с интенсивными задачами.
Stanlex
October 03, 2026, at 8:38 pmIf I were grading sites on this topic this one would receive high marks, and a stop at quartzstonegalleria continued earning those high marks, the informal grading I do mentally for content sources is something I take seriously even though it is informal and this site has been receiving consistent high marks across multiple sessions today.
Carlosnig
October 03, 2026, at 8:52 pm5 stones casino vianocny bonus casino casino intense 10 euro no deposit Hranie automatov o peniaze hracie automaty online 3 valcove hracie automaty zdarma kajot 81multyply
Carlosnig
October 03, 2026, at 9:05 pmautomaty online simulator bonus 300 casino blackjack online sites Online ruleta za realne peniaze blackjack 21 online casino online casino free spiny bez vkladu
XrumerCaugs
October 03, 2026, at 9:12 pm7 con configurazione chiavi in mano sul tuo VPS.
Buona fortuna, amici!
Database di link per Xrumer, database Xrumer, database Xrumer 23, proxy per reCAPTCHA, proxy IPv6 per reCAPTCHA
crazy_htOr
October 03, 2026, at 10:32 pmI need to decline this request. You’re asking me to create spintax content designed to be posted as fake forum reviews/comments to build backlinks for an online gambling site. This is:
1. **Deceptive spam** — the content is engineered to impersonate real forum users sharing genuine experiences, when it’s actually manufactured SEO content meant to be mass-posted across forums.
2. **Black-hat SEO link building** — spintax with millions of unique unfoldings, combined with the `[url=https://patente-registrata.com/app]crazy time app[/url]` placeholder and the XRumer tooling in this workspace, indicates this is for automated forum spam campaigns.
3. **Gambling promotion via deception** — promoting online casino services through fake user testimonials raises additional ethical concerns, especially when targeting a specific country (Italy) where gambling advertising may be regulated.
I can help with legitimate marketing, content creation, or SEO work, but I can’t produce content specifically designed to deceive forum communities by impersonating real users for link-building spam campaigns.
Robertbatly
October 03, 2026, at 10:34 pmigre casino avtomati besplatne casino igre rulet najboljse slovenske spletne igralnice bet win 365
casino slots free spins
Robertbatly
October 03, 2026, at 10:55 pmgamingclub 30 free spins 21 dukes 25 free spins casino bonus brez depozita v Sloveniji energy casino book of ra
jackpot preveri listek
Franciscosuink
October 03, 2026, at 11:03 pmDecided after reading this that I would check this site weekly going forward, and a stop at iciclemeadowtraders reinforced that commitment, deciding to add a site to a regular rotation requires meeting a quality bar that very few places clear and this one cleared it cleanly without any noticeable effort or marketing push behind it.
crazy_pcen
October 03, 2026, at 11:12 pmMi diverto su crazy time da un paio di mesi ormai e onestamente non mi posso lamentare troppo. All’inizio ero scettico perche avevo gia provato altre piattaforme che sembravano belle e poi si rivelavano una delusione, tipo tempi di prelievo assurdi. Qui invece mi sono iscritto in due minuti, bastano pochi dati, e non serve versare chissa quanto per iniziare, credo 10-20 euro.
La parte che mi ha convinto di piu e il catalogo slot. Ci sono centinaia e centinaia di titoli, da provider tipo Pragmatic Play, NetEnt, Evolution per il live. Ho giocato parecchio a Gates of Olympus che paga bene quando si scalda, e anche Sweet Bonanza mi piace un sacco. L’unica cosa che non mi e piaciuta e che certi giochi caricano lenti da telefono, specialmente se non hai il wifi.
Per il live casino e dove passo piu tempo. I tavoli Evolution con croupier veri sono fatti bene, e il game show Crazy Time e una bomba — le ruote bonus tengono incollati. Tra l’altro potete dare un’occhiata alle offerte attuali su [url=https://patente-registrata.com]crazy time[/url] se vi interessa. L’offerta iniziale prevede free spin e un match deposit con requisiti di scommessa sui 30x circa, che non e poco ma perlomeno te lo dicono subito nelle condizioni.
I prelievi su crazy time le ho ricevute in 24-48 ore tramite e-wallet. Come metodi ci sono le carte principali, Skrill e Neteller, anche crypto se vi piace quel mondo. Una volta ho provato con la carta e e stato leggermente piu lento, ma niente di drammatico. L’assistenza e reattivo via chat, anche se a volte capiscono al volo il problema.
Insomma su crazy time l’esperienza e positiva, non e perfetto — il sito da mobile potrebbe essere piu fluido e certi bonus hanno condizioni un po’ strette — ma per giocare dall’Italia funziona tranquillamente. Se cercate qualcosa di affidabile con buone slot e live, vale la pena provare.
Robertbatly
October 03, 2026, at 11:13 pmigre casino portoroЕѕ brezplaДЌne casino igre free games domaca spletna igralnica z ugodnostmi igre na sreco za pravi denar
slots magic casino no deposit bonus codes 2026
MarkMaike
October 03, 2026, at 11:32 pmReading this in segments because the day was busy, and the post survived the fragmented attention well, and a stop at pivotpeak held up similarly under interrupted reading, content that can withstand modern distracted reading patterns rather than requiring a perfect block of focused time is increasingly the kind I prefer.
kalibrovka_xfKa
October 03, 2026, at 11:34 pmДля обеспечения точности измерений важно своевременно провести [url=https://kalibrovka-kalibrov.ru/]калибровка калибров НКТ[/url].
Обеспечение регулярной калибровки калибров — залог стабильной работы технологических процессов.
crazy_xren
October 04, 2026, at 12:01 amGente, volevo condividere come mi trovo da un paio di mesi a questa parte. Mi sono imbattuto in crazy time per caso e onestamente ero scettico all’inizio, pero dopo un po’ mi ha convinto. Il catalogo giochi e piuttosto ricca — parliamo di piu di 2500 slot tra cui cose firmate Pragmatic Play, NetEnt e pure Evolution per il live. Mi sono fissato con Gates of Olympus e qualche sessione su Sweet Bonanza — non mi lamento delle vincite.
Il live casino e quella che vale di piu, sul serio. Dealer veri, tutto in streaming, e c’e Crazy Time Evolution ti tengono incollato. Trovi anche le classiche blackjack e roulette in versione live con dealer che parlano italiano, cosa non scontata. Una sera ho avuto qualche micro-lag ma niente di grave.
Per quanto riguarda bonus di benvenuto, su crazy time ti danno il 100% sul primo deposito fino a 500 euro con in aggiunta 50 free spin. Il requisito di puntata e x35, poteva essere meglio pero ci sta. Per iniziare servono 20€, e non devi svenarsi. Potete controllare le offerte attuali passando da [url=https://patente-registrata.com]crazy time[/url] prima di registrarvi.
Iscriversi richiede due minuti, abbastanza standard. Lato pagamenti accettano Visa, Mastercard, gli e-wallet tipo Skrill, e anche Bitcoin per chi preferisce le crypto. I prelievi mi sono arrivati in 24-48 ore sull’e-wallet, con carta ci vogliono 3-5 giorni. Zero casini con i pagamenti finora, incrociamo le dita.
Una cosa che non mi e piaciuta tanto di crazy time e l’app mobile — va dal browser e manca un’app dedicata sullo store. Non e un dramma, ma la vorrei. Il supporto risponde via live chat 24 ore su 24 e hanno gestito una questione sul deposito velocemente. Hanno la licenza Curacao, ok non sara la piu prestigiosa ma almeno e qualcosa. Nel complesso mi trovo bene e ci passo parecchie serate.
JerryDyege
October 04, 2026, at 12:12 amVavada atbildigas speles riki ietver iemaksu limitus, sesijas ilguma ierobezojumu un atdzisanas periodu pec limita mainas. Aktivo sesiju saraksts rada katru ierici ar pieslegsanas datumu, IP adresi un iespeju atsaukt piekluvi viena klikski. Visa informacija: https://lowcountryweekly.com/ Sads statistikas pilnigums vertigs speletajiem, kuri pasi uztur savu rezultatu uzskaiti ilga distance.
crazy_lvOr
October 04, 2026, at 12:33 amRagazzi, sono su crazy time app da qualche settimana e devo dire che non mi aspettavo granche, ma alla fine mi ha sorpreso in positivo. Iscriversi l’ho fatta in due minuti, senza mille verifiche iniziali, bastano anche solo 10 euro sei operativo. Io ho depositato con la Visa senza problemi, ma ci sono anche Skrill, Neteller e anche crypto se vi interessa. Da mobile funziona senza lag, anche se qualche volta ci mette un attimo a caricare le live — niente di tragico.
Il catalogo giochi non e male per niente — ci saranno oltre 2000 giochi contando tutto. Trovi le slot di Pragmatic Play tipo Gates of Olympus e Sweet Bonanza, qualcosa di NetEnt, pure Big Time Gaming. Io personalmente preferisco il live casino — Evolution con i dealer dal vivo sono fatti bene. Crazy Time il game show mi ci perdo ogni sera, non vi dico e troppo coinvolgente. L’unica cosa: mi piacerebbe piu filtri per cercare nella sezione slot.
Il bonus di benvenuto su crazy time app non e malaccio: mi hanno dato un 100% fino a 500€ piu 50 giri gratis. Il requisito di scommessa e a 35x, che e nella media. C’e chi offre meno, ok, pero le condizioni le trovi scritte bene. Potete dare un’occhiata alle promo aggiornate passando da [url=https://patente-registrata.com/app]crazy time app[/url] cosi vedete cosa c’e.
Ritirare i soldi da crazy time app mi hanno messo un po’ in ansia la prima volta, e invece ci hanno messo meno di due giorni sulla carta. Con gli e-wallet pare siano ancora piu veloci, anche entro un giorno. Il controllo documenti me l’hanno chiesta al primo prelievo, procedura standard. L’assistenza ha la chat dal vivo abbastanza rapidamente, pero non sempre in italiano — un po’ scocciante.
Vedo che hanno la licenza Curacao, che per me e sufficiente. So che qualcuno preferisce solo siti ADM, ma io mi sono trovato bene lo stesso. Nel complesso se cercate tante slot e un live casino serio ci sta. Che funzioni bene da telefono per me e fondamentale, perche gioco quasi sempre dal divano. Se avete domande che vi dico quello che so.
DravenLoods
October 04, 2026, at 12:36 amThe whole experience of reading this was pleasant from start to finish, no pop ups and no annoying interruptions, and a look at harborbrookvendorfoundry continued that clean experience, technical choices about page design matter for the reader and this site clearly cares about the small details that add up to comfort across multiple visits.
Robertbatly
October 04, 2026, at 1:30 amspringbok online casino no deposit bonus codes casumo online casino spletni casino v slovenscini live casino reviews
bellini casino no deposit bonus
EugeneZed
October 04, 2026, at 1:35 amCuts through the usual marketing fluff that dominates this topic online, and a stop at marblecovevault kept the same clean approach going, this is the kind of writing that respects the reader’s time rather than wasting it on repetitive setups before finally getting to the point at hand which is what most sites do.
Robertbatly
October 04, 2026, at 1:51 ambesplatne casino igre za igranje casino rewards group online igre z denarnimi nagradami casino slovenia lubiana
no deposit bonus casino 20 €
Robertbatly
October 04, 2026, at 2:09 amadmiral kongo casino full tilt poker free download no deposit bonus v slovenskih igralnicah perla casino slovenia kontakt
hotel admiral casino kozina
JulianZet
October 04, 2026, at 2:48 amA modest masterpiece in its own quiet way, and a look at granitecovevendorhall confirmed the same quiet quality across the rest of the site, calling something a masterpiece is usually overstating but for content this carefully crafted the word feels appropriate even if the writers themselves would probably resist the label honestly.
MarcusDense
October 04, 2026, at 2:51 amNow noticing that the post avoided the temptation to be funny in places where humour would have undermined the substance, and a stop at vexaroplus maintained the same restraint, knowing when to be serious is a rare editorial virtue and this site has clearly developed it through what I assume is careful editorial practice over years.
Robertbatly
October 04, 2026, at 4:25 amkonami free slot games casino bet at home najboljsi spletni casino za Slovence book of ra big win
red casino online
XrumerCaugs
October 04, 2026, at 4:31 amSiamo orgogliosi di presentare un database aggiornato per Xrumer. È stato svolto un ampio lavoro analitico proprietario e questa versione è stata costruita interamente da zero.
Dettagli e ordini tramite il link: https://t.me/bootmasterru/144
• Data di rilascio: 3 ottobre 2026
• Numero totale di link: 4.266.514
• Segmento (Creazione profili su forum): 247.504
• Segmento (Pubblicazione generale): 2.511.572
• Segmento (Moduli di contatto): 1.507.438
In questa versione, abbiamo dato priorità alla massima efficienza (tempo di elaborazione vs. risultati) includendo esclusivamente segmenti “Success” (di successo). Non importa quanto altri venditori di database cerchino di girarci intorno e gonfiare i loro numeri, non ha assolutamente senso elaborare segmenti “HalfSuccess” o “Others”. Stiamo risparmiando il tuo traffico e il tuo tempo. Questo è ONESTO.
Offriamo inoltre proxy IPv6 per Xevil ReCaptcha 6
Stuartnum
October 04, 2026, at 4:35 amBookmark earned and folder updated to track this site separately, and a look at wheatgrovegoodsstore confirmed the folder upgrade was the right call, organising my reading list so that good sites do not get lost in a sea of casual bookmarks is something I do more carefully now and this site warranted its own spot.
Robertbatly
October 04, 2026, at 4:47 ambest casino game to win money online poker free bonus no deposit izberi slovenski online casino igralni avtomati casino igre
free spin no deposit 2026 100
GradyKag
October 04, 2026, at 4:49 amThanks for a post that does not try to be funny when it is not the moment for it, and a stop at violettrailartisanmarket maintained the same appropriate seriousness, knowing when humour helps and when it just signals desperation for engagement is a sign of editorial maturity that many blogs have not developed yet.
Robertbatly
October 04, 2026, at 5:05 amgrande vegas casino no deposit bonus codes live casino 21 domaca spletna igralnica z ugodnostmi hotel casino safir sezana slovenia
igre casino avtomati
Zachariahkib
October 04, 2026, at 6:08 amNow leaving a small mental note to recommend this when the topic comes up in conversation, and a look at honeymeadowvendorworks extended that recommend ready feeling, content that arms me with shareable references for likely future conversations is content with social value and this site is providing that conversational ammunition consistently for me lately.
Robertbatly
October 04, 2026, at 7:21 amleovegas free spins win koliko vrijedi as u blackjacku igralniske igre z resnicnim denarjem admiral casino kozina
game of thrones free slots
Robertbatly
October 04, 2026, at 7:42 ambook of ra who made free spin no deposit bonus casino 2026 kje igrati online igre za denar monster casino no deposit bonus
getminted free slot games
Robertbatly
October 04, 2026, at 8:01 am100 free spins no deposit poker casino live online casino s slovenskim vmesnikom live casino result
book of ra fixed
ArthurCat
October 04, 2026, at 8:25 amКупить права категории б быстро, без нервов и очередей — ты по адресу. Работаю напрямую с «нужными» людьми в гос. структурах ГИБДД. Делаем всё так, что в базе всё будет чисто.
Emanuelbon
October 04, 2026, at 9:33 amGrateful for posts like this one, they remind me there are still places online run by people who care about quality, and a look at froststoneemporium reflected the same standards, you can tell the difference between content made for readers and content made just for search engines today and this is the former.
JaydenSow
October 04, 2026, at 9:44 amA nicely understated post that does not shout for attention, and a look at rubyorchardvault maintained the same quiet quality, understatement is a stylistic choice that distinguishes serious writing from attention seeking writing and this site has clearly committed to the understated approach as a core editorial value rather than just a phase.
IsiahAgemo
October 04, 2026, at 10:16 ambled casino poker casino igre besplatne book of ra darilo ob registraciji v spletnem casinoju jackpot casino online
bet365 first deposit bonus code
IsiahAgemo
October 04, 2026, at 10:37 amigre casino portoroЕѕ williamhill casino live spletne igre za pravi denar mega sic bo
casino bonus money no deposit
IsiahAgemo
October 04, 2026, at 10:56 ambest blackjack strategy no deposit bonus real casino slovenia igralnica z bonusom brez lastnega vlozka slot igrice book of ra
brezplaДЌne casino igre slovenia
IsiahAgemo
October 04, 2026, at 1:12 pm4 days 5 free spin casino casino hotel admiral skofije izbor spletnih iger z denarnimi dobitki aztec casino online
247 free poker
Kennethexpem
October 04, 2026, at 1:31 pmIf patience for careful reading is rare these days finding sites that reward it is rarer still, and a stop at bayharborvault extended that rare reward, the diminishing returns on shallow content reading have made me more selective about where to spend reading time and this site is meeting the higher selectivity bar consistently.
Wilburlip
October 04, 2026, at 1:34 pmMost of the time I bounce off similar pages within seconds, and a stop at olivestonecollective held me longer than I would have predicted, the ability to convert a likely bouncing visitor into an engaged reader is a quality signal and this site has demonstrated that conversion ability across multiple visits where I expected to bounce.
IsiahAgemo
October 04, 2026, at 1:34 pmbwin live roulette live casino funky time casino s startnim bonusom brez vplacila casino del rio online
online casino bez depozita
IsiahAgemo
October 04, 2026, at 1:51 pmunibet casino slovenija crazy time live casino kje dobiti bonus brez depozita v Sloveniji pragmatic play live casino
bet365 v sloveniji
WilliamGaiLk
October 04, 2026, at 2:32 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-pri-beremennosti/]юридические услуги по расторжению брака при беременности[/url] – юрист поможет разобраться в вашей ситуации, подготовить необходимые документы, определить порядок обращения в ЗАГС или суд и защитить ваши интересы. Получите профессиональную юридическую помощь по вопросам расторжения брака при беременности и сопровождение на всех этапах процедуры.
Cainpal
October 04, 2026, at 4:04 pmSaving this link for the next time someone asks me about this topic, and a look at orchardcrestmarketplace expanded what I will be sharing with them, this is the kind of resource that makes a real difference when you are trying to point a friend to something useful and reliable rather than generic marketing pages.
IsiahAgemo
October 04, 2026, at 4:07 pmcasino admiral kozina slovenia best online casino bonus no deposit online igre na sreco za pravi denar free welcome bonus no deposit 2026
ruleta casino real
IsiahAgemo
October 04, 2026, at 4:29 pmcasino igre za zabavo free spins on registration no deposit casino igre za denar casino bonus eu
Does Casinobit IO have a no deposit bonus
ColeRof
October 04, 2026, at 4:35 pmFound the section structure particularly thoughtful, and a stop at skystonegalleria suggested the same care across the broader site, structural choices guide the reader through the material in ways most people do not consciously notice but feel the absence of when those choices are made carelessly or not at all.
Mariosetip
October 04, 2026, at 4:45 pmOn reflection this is the kind of writing that improves my taste for what is possible in the format, and a look at trackandtrade continued raising that bar, content that elevates my expectations rather than lowering them is doing important work in calibrating my standards and this site is participating in that elevation reliably.
IsiahAgemo
October 04, 2026, at 4:47 pmslots free spins slot game free igt novomatik delux poiscite casino bonus brez depozita bet365 casino best game
casino igralni avtomati
NormanwEn
October 04, 2026, at 5:26 pmVavada kazino darbojas tiessaistes izklaides tirgu kops 2017. gada un saja laika kluvis par atpazistamu zimolu Baltijas speletaju vidu. Videjais RTP visa spelu biblioteka pedejos gados turas 96-97% robezas, kas atbilst nozares standartam. Aktuala adrese: vavada casino 100 free spins promo code – https://cogarchworkshop.org/ Sada tehniska baze jutama kataloga ielades atruma un live translaciju stabilitate maksimalas slodzes stundas.
Drefut
October 04, 2026, at 5:35 pmLiked the balance between depth and brevity, never too shallow and never too long, and a stop at violetharbortradinggallery kept the same balance going across the rest of the site, this is one of the harder skills in writing and the team here clearly has it figured out very well indeed across every page.
Benniepen
October 04, 2026, at 6:38 pmCame back to this twice now in the same week which is unusual for me, and a look at mossharborvault suggested I will keep coming back, the kind of post that earns repeated visits rather than one and done reading is the gold standard for content quality and this site clearly hit that standard.
IsiahAgemo
October 04, 2026, at 7:02 pmfree slot machine games no download ruleta casino real igralniske igre z denarnimi dobitki povezava za bet bet athome
najboljЕЎe casino igre za pravi denar
Roderickbot
October 04, 2026, at 7:19 pmDecided to read this site for a while before forming a verdict, and the verdict after several pages is positive, and a stop at violetharborcollectivemart continued that pattern, judging a site requires more than one post and giving sites a fair sample is something I try to do for promising candidates rather than rushing to dismiss.
IsiahAgemo
October 04, 2026, at 7:23 pmspinia casino no deposit bonus vegas slots online casino online casino za igralce iz Slovenije cabaret online casino
casino table games
Georgeoxype
October 04, 2026, at 7:32 pmКупить права дубликат быстро, без нервов и очередей — ты по адресу. Работаю напрямую с «нужными» людьми в гос. структурах ГИБДД. Делаем всё так, что в базе всё будет чисто.
MosesFuh
October 04, 2026, at 7:38 pmLiked that the post acknowledged complications rather than pretending they did not exist, and a stop at outboardoutlet continued that honest framing, sites that handle complexity with care rather than papering it over with simplifying claims are doing real intellectual work and this one is clearly in that category based on what I have read.
IsiahAgemo
October 04, 2026, at 7:42 pmslovenia accepted casinos online online casino free play denarne igre v spletnem casinoju book of ra 6 deluxe demo
sweet bonanza live casino
DonaldAdard
October 04, 2026, at 8:41 pmПомощь оказывают врачи с практикой в наркологии, психиатрии и восстановительной терапии.
Ознакомиться с деталями – [url=https://narkologicheskaya-klinika-voronezh19.ru/]запой наркологическая клиника[/url]
WilliamGaiLk
October 04, 2026, at 8:41 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/razvod-pri-beremennosti/]консультация по расторжению брака при беременности[/url] – юрист поможет разобраться в вашей ситуации, подготовить необходимые документы, определить порядок обращения в ЗАГС или суд и защитить ваши интересы. Получите профессиональную юридическую помощь по вопросам расторжения брака при беременности и сопровождение на всех этапах процедуры.
CalvinPUTiN
October 04, 2026, at 9:28 pm[url=https://vk.ru/id7281076]врач с пожизненым диагнозом ДУРДОМА[/url]
JettPhoca
October 04, 2026, at 9:40 pmDecided this was the kind of site I would defend in a discussion about good blog content, and a stop at crownmeadowcollectivemart reinforced that, very few sites earn active defence rather than passive consumption and this one has clearly crossed that threshold for me without needing any explicit pitch from the writers themselves either.
IsiahAgemo
October 04, 2026, at 9:57 pmcasino admiral kozina bingo free spin casino no deposit bonus igraj v slovenskem spletnem casinoju casino game bombay
live casino games online real money
LewisMalay
October 04, 2026, at 10:18 pmWorth recognising that this site does not chase the daily news cycle, and a stop at crowntrailartisanoutlet confirmed the longer publication arc, sites that resist the pressure to comment on every passing event are sites with genuine editorial discipline and this one has clearly chosen depth over volume which I respect deeply.
IsiahAgemo
October 04, 2026, at 10:18 pmblackjack free play free bet no deposit bonus spletni casino z igrami za denar hitstars online casino slo
book of ra magic slot demo
IsiahAgemo
October 04, 2026, at 10:37 pmlive casino online real money casino midas no deposit bonus codes casino ponudbe brez prvega vplacila casino igre lucky lady
bet365 bonus code existing customer
karkasnyy_veSn
October 04, 2026, at 11:02 pm[url=https://karkasnye-doma-spb11.ru]каркасный дом под ключ в спб цена[/url] станет комфортным и энергоэффективным решением для загородной жизни.
Большинство работ выполняется по заранее подготовленному проекту.
Качественный утеплитель снижает расходы на отопление в холодное время года.
Заказчик выбирает количество этажей, размер помещений и форму здания.
В результате каркасный дом становится практичным, теплым и доступным вариантом для загородной жизни.
ByronAmils
October 04, 2026, at 11:16 pmA thoughtful piece that did not strain to be thoughtful, and a look at sageharborcollectivemart continued that effortless quality, when thinking shows up in writing without the writer drawing attention to it you know you are reading something genuinely considered rather than something performing the appearance of consideration which is also common online.
IsiahAgemo
October 05, 2026, at 12:53 ambwin live casino app free vegas slots online izbor spletnih iger z denarnimi dobitki casino free spins no deposit 2026 slovenia
bet365 bonus code slovenia
IsiahAgemo
October 05, 2026, at 1:14 amnoble casino online online casino free bonus no deposit pregled slovenskih spletnih casinojev 100 free spins no deposit
365 live casino
IsiahAgemo
October 05, 2026, at 1:33 amjet casino bonus code igranje spletnih igr za denar spletne igre za denar v Sloveniji casino slots perfect spins no deposit free spin
free slot book of ra
Morriscutty
October 05, 2026, at 2:22 amhttps://doctor-nona.ru/ • др.Nona
• Isrel
RicardoMip
October 05, 2026, at 2:40 amThanks for keeping things clear and to the point, that is honestly hard to find online these days, and after reading through timbertrailmarketplace the message stayed consistent which makes me trust the information being shared more than I usually do on similar pages that cover this same kind of topic.
blacksprutRag
October 05, 2026, at 3:26 am[center][b]Blsp At — рабочий вход 2026[/b][/center]
[center][i]Проверенные адреса без VPN[/i][/center]
[center][url=https://blsp-at.site][img]https://black-sprut.top/images/logo.png[/img][/url][/center]
Здарова! Делюсь проверенными переходниками на blsp-at — крупный даркнет ресурс.
Сайт открывается стабильно — важно только использовать актуальный адрес. Здесь 3 рабочих варианта:
[list=1]
[*] [url=https://blsp-at.site]Актуальный адрес blsp at — без VPN[/url]
[*] [url=https://blacksprut.website]BlackSprut — официальный сайт напрямую[/url]
[*] [url=https://bleksprut-oficialny-sajt.site]Блекспрут — вход без TOR[/url]
[/list]
В случае если ссылка недоступна — пробуйте следующий. Любая открывает официальную BLSP AT.
Сохраняйте — пригодится. Пишите если не работает.
[size=1][color=#333333]blsp at, https blsp at, blsp at сайт, m blsp at, k blsp at, v blsp at, n blsp at, blsp ap, blsp at check, blsp at клады, blsp at вход, blsp ay, blsp am, blsp com, blsp cc, blsp ссылка, bc blsp at, ntt k blsp at, w blsp at, blsp at отзывы, blsp at зеркало, blsp at 18, blsp at my balance, blsp at тг, blsp at зайти, blacksprut, blacksprut ссылка, blacksprut зеркало, blacksprut сайт, blacksprut работает, blacksprut официальный, blacksprut маркетплейс, blacksprut актуальные, blacksprut darknet, blacksprut даркнет, blacksprut вход, блекспрут сайт, блекспрут официальный, блекспрут официальный сайт, ссылки на блекспрут, блекспрут вход[/color][/size]
IsiahAgemo
October 05, 2026, at 3:48 amkako igrati pokerstars v sloveniji euro dЕѕek pot slovenija brezplacni bonus brez vplacila v slovenskih casinojih casino admiral ptuj
best no deposit bonus
IsiahAgemo
October 05, 2026, at 4:10 ambook of ra demo kako deluje wagering casino pregled ponudb brez depozita play free slots new
best online casino for blackjack
IsiahAgemo
October 05, 2026, at 4:28 amadmiral casino kozina red dog casino no deposit bonus 2026 bonusi za nove igralce v Sloveniji free game book of ra
oshi casino login
dostavka_yyOa
October 05, 2026, at 5:26 am[url=http://alkogol-dostavka-moskva-xpr.ru/]доставка алкоголя ночью[/url]
Услуга доставки алкоголя набирает популярность у потребителей.
Современные службы доставки позволяют заказать алкоголь и получить его в кратчайшие сроки.
Особенности доставки включают широкий ассортимент и возможность выбора наиболее подходящего варианта .
Раздел 1: Выбор сервиса и оформление заказа.
Процесс оформления прост и понятен, что позволяет сэкономить время .
Удобно, что есть возможность получить профессиональную помощь при выборе.
Раздел 2: Ассортимент и цены.
В большинстве случаев доставка включена в цену или предоставляется за отдельную плату.
Справедливая ценовая политика делает услугу доступной широкому кругу покупателей.
В большинстве случаев доставка возможна в тот же день.
Некоторые компании предлагают круглосуточную поддержку и возможность заказа в любое время .
Важно, что доставчики следят за сохранностью заказа на всех этапах.
Важное условие — соблюдение законодательства при доставке алкоголя .
Курьеры проходят обучение и не допускают нарушений при доставке .
Доставка алкоголя — это современное решение, которое позволяет экономить время и избегать походов в магазины .
IsiahAgemo
October 05, 2026, at 6:44 amnajboljЕЎi bonus za registracijo brez vplaДЌila casino live ljubljana casino ponudbe brez prvega vplacila casino igre free
casino no deposit bonus new
IsiahAgemo
October 05, 2026, at 7:05 amcasino online nl company casino no deposit bonus codes igralniske igre z denarnimi dobitki casino no deposit bonus 2026
What is the golden rule of gambling
CoreyplEat
October 05, 2026, at 7:06 amGrateful for posts like this one, they remind me there are still places online run by people who care about quality, and a look at wheatcovevault reflected the same standards, you can tell the difference between content made for readers and content made just for search engines today and this is the former.
IsiahAgemo
October 05, 2026, at 7:24 amkoliko vrijedi as u blackjacku live casino online game igraj brezplacno in zadrzi dobitke online casino with registration bonus
casino min deposit 1 €
crazy_uhMt
October 05, 2026, at 8:32 amBazzico su sti giochi da inizio anno e va detto la ruota mi ha dato piu momenti buoni di quanto pensassi. Non sono certo uno da puntate folli, normalmente metto un paio di euro per giro e tanto basta. Il catalogo di Crazy Time e ben fornito: si parla di 1800 circa macchinette mettendo dentro Pragmatic Play, NetEnt e Play’n GO, insomma i classiconi come Gates of Olympus, Sweet Bonanza e Book of Dead non mancano.
La sezione con i croupier e roba di Evolution e la differenza si sente. Dealer in carne e ossa, con tavoli in italiano su alcuni tavoli, e i vari game show sono proprio quelli dove passo il grosso delle sessioni. Di tanto in tanto controllo lo storico dei round bonus prima di entrare, piu che altro per scaramanzia.
Il bonus di benvenuto che ti da Crazy Time adesso gira intorno al 100% fino a 300€ piu anche 150 free spin, spalmati su qualche giorno. Ti danno anche un piccolo no deposit dopo la verifica dei documenti. Il requisito di puntata e 35x, nella media insomma, meglio leggersi il regolamento: si trovano i dettagli aggiornati direttamente su [url=https://wisniewskamakeup.pl/2026/10/02/app-crazy-time-tutto-quello-che-devi-sapere/]app crazy time[/url] prima di registrarti.
Sul fronte pagamenti non mi lamento. Uso Skrill e una volta Neteller e i soldi arrivano in mezza giornata circa, con Visa serve un paio di giorni lavorativi. Prendono pure le crypto, ma non le ho provate. Deposito minimo 10€, registrazione veloce, cinque minuti. L’unica cosa che mi ha rotto e stata la verifica: prima foto rifiutata senza spiegazioni per un motivo assurdo.
L’assistenza su Crazy Time risponde in italiano e questo aiuta, pero di notte ci vuole pazienza. Su mobile il sito va bene dal browser, l’app c’e per Android esiste ma e ancora acerba. Sulla licenza Malta Gaming Authority, non e ADM, cosa che a qualcuno non va giu. Per ora continuo, senza aspettarmi miracoli.
crazy_ahMt
October 05, 2026, at 8:34 amBazzico su questi tavoli da inizio anno e diciamocelo quella benedetta ruota mi ha dato piu momenti buoni di quanto immaginassi. Non sono certo uno che punta cifre assurde, in genere piazzo due o tre euro per giro e tanto basta. Il lobby su Crazy Time e messo bene: si parla di 2000 e rotti slot mettendo dentro Pragmatic Play, NetEnt e Play’n GO, insomma i titoli grossi come Book of Dead e Gates of Olympus non mancano.
La parte live e roba di Evolution e la qualita si nota. Ragazzi e ragazze veri, che parlano anche italiano in certe fasce orarie, e i game show restano quelli dove butto il grosso delle sessioni. Qualche volta controllo lo storico dei round bonus prima di sedermi, piu per abitudine che per logica.
La promo d’ingresso proposta da Crazy Time in questo periodo gira intorno al 100% fino a 300€ piu 150 free spin, distribuiti su piu giorni. C’e pure un piccolo no deposit dopo la verifica dei documenti. Il wagering e 35x, che non e regalato, per cui occhio ai termini: si trovano i dettagli aggiornati direttamente su [url=https://sandysdeals.com/crazy-time-guida-completa-bonus-e-opzioni-di-gioco-per-l-italia/]crazy time[/url] se ti interessa approfondire.
Sul fronte pagamenti ho poco da dire. Uso Skrill e una volta Neteller e mi sono arrivati entro le 24 ore, con Visa ci vogliono 3 giorni buoni. Prendono pure le crypto, che pero non ho testato. Si parte da 10 euro, l’iscrizione veloce, cinque minuti. L’unica cosa che mi ha rotto e stata la verifica: mi hanno rifiutato la bolletta due volte per un motivo assurdo.
La chat di assistenza di Crazy Time ti risponde in italiano ed e gia qualcosa, pero dopo mezzanotte ci vuole pazienza. Da cellulare il sito va bene dal browser, un’applicazione dedicata per Android va, ma preferisco il sito. Licenza Malta Gaming Authority, non e ADM, e va saputo prima. Nel frattempo io resto, con la testa a posto.
crazy_jnMt
October 05, 2026, at 8:36 amSto giocando su questi tavoli da un annetto e onestamente quella benedetta ruota mi ha regalato piu risultati di quanto pensassi. Non sono il tipo che sbrocca con le puntate, normalmente butto un paio di euro a giro e via. La sezione giochi su Crazy Time e parecchio ricco: si parla di 1800 circa slot se conti Pragmatic Play, NetEnt e Play’n GO, per cui i titoli grossi come Sweet Bonanza, Book of Dead e Gates of Olympus sono li al loro posto.
Il comparto live e gestita da Evolution e si vede. Croupier veri, che parlano anche italiano su alcuni tavoli, e i vari game show sono proprio quelli dove butto quasi tutte le serate. Qualche volta do un’occhiata a le stats dei bonus prima di entrare, piu per abitudine che per logica.
L’offerta di benvenuto proposta da Crazy Time al momento gira intorno al 100% fino a 300€ piu anche 100 giri gratis, spalmati su qualche giorno. Esiste anche una decina di euro senza deposito se verifichi i documenti. Il requisito di puntata sta a 35x, che non e proprio una passeggiata, meglio leggersi il regolamento: trovi le condizioni complete su [url=https://www.interadminist.com/crazy-time-guida-alla-sicurezza-e-informazioni-essenziali-per-i-giocatori-italiani.htm]crazy time[/url] prima di metterci soldi.
Sul fronte pagamenti va abbastanza bene. Ho usato Skrill e una volta Neteller e l’accredito arriva entro le 24 ore, con Mastercard serve 3 giorni buoni. Accettano anche crypto, che pero non ho testato. Deposito minimo 10 euro, registrazione veloce, cinque minuti. La cosa che mi ha dato fastidio e stato il KYC: mi hanno rifiutato la bolletta due volte per una sciocchezza.
La chat di assistenza che trovi su Crazy Time ti risponde in italiano ed e gia qualcosa, va detto che di notte i tempi si allungano. Da telefono il sito va bene dal browser, l’applicazione per Android esiste ma e ancora acerba. Licenza c’e quella maltese MGA, niente ADM, cosa che a qualcuno non va giu. Io intanto continuo, senza aspettarmi miracoli.
nonebet_ncEi
October 05, 2026, at 8:39 amBeen using Nonebet for something like five months now, mainly on the train home, and might as well dump some thoughts since a few blokes here asked. Getting an account took no time — email and a password, that’s it, though the KYC bit came later, which is normal enough. You only need around $10 which suits me.
There’s a stupid amount of games — somewhere north of 4,000 slots and tables from memory. NetEnt stuff is everywhere, so Sweet Bonanza and Book of Dead are all there. I mostly stick to Big Time Gaming Megaways when I want longer sessions. Microgaming back catalogue is there as well. Live dealer side runs on Evolution, which means real croupiers, roulette running 24/7 plus Crazy Time which I watch more than I play.
Bonus-wise the offer when I joined was 100% to $500 with 150 spins, wagering was 40x which is about average. They also had a no-deposit spins offer for a while but it comes and goes. Offers rotate a lot so have a look at [url=https://merrier.com.pe/wyns-online-casino-australia-complete-guide-for-players/]wyns casino[/url] if you’re thinking about it. The one thing that annoyed me is the $5 max bet cap during bonus play — breached it once without noticing and lost the lot. My fault, but still.
Cashouts at Nonebet have been pretty quick. Crypto came back in under an hour every time I’ve done it, e-wallets were 24 hours or so, but the Visa one took nearly four days which felt long. Deposits are instant with Visa, Mastercard or crypto.
Support got back to me in about five minutes at midnight, actual humans after the first canned reply. Nonebet doesn’t have a proper app as far as I can tell — it’s just the mobile browser, but it runs fine on my Android. Licensed out of Curacao, which isn’t the ACMA, obviously, something to be aware of for us down here.
crazy_xbMt
October 05, 2026, at 8:49 amBazzico su questi tavoli da qualche mese e onestamente il gioco della ruota mi ha portato piu soddisfazioni di quello che credevo. Non sono il tipo che sbrocca con le puntate, in genere metto 3-4 euro per giro e amen. La sezione giochi che trovi su Crazy Time e messo bene: si parla di 1800 circa macchinette mettendo dentro Pragmatic Play, NetEnt e Play’n GO, quindi i titoli grossi del calibro di Sweet Bonanza, Book of Dead e Gates of Olympus sono li al loro posto.
La sezione con i croupier e gestita da Evolution e si vede. Croupier veri, con tavoli in italiano nelle ore di punta, e gli show tipo Monopoly Live restano quelli dove passo il grosso delle sessioni. Ogni tanto controllo le stats dei bonus prima di sedermi, non che serva davvero, eh.
L’offerta di benvenuto proposta da Crazy Time adesso sta sul 100% fino a 300€ con in aggiunta 150 free spin, spalmati su qualche giorno. Ti danno anche un no deposit da 10€ dopo la verifica dei documenti. Il requisito di puntata e 35x, nella media insomma, meglio leggersi il regolamento: puoi trovare i termini precisi su [url=https://lifemattersgroup.com/crazy-time-italia-guida-app-e-mobile-per-giocare-su-smartphone/]crazy time[/url] se ti interessa approfondire.
Per i soldi ho poco da dire. Ho usato Skrill e una volta Neteller e l’accredito arriva entro le 24 ore, con la carta serve 3 giorni buoni. Accettano anche crypto, anche se io resto sui bonifici classici. Si parte da 20€, l’iscrizione veloce, cinque minuti. La cosa che mi ha dato fastidio e stato il KYC: mi hanno rifiutato la bolletta due volte per un motivo assurdo.
L’assistenza di Crazy Time parla italiano il che non e scontato, anche se dopo mezzanotte i tempi si allungano. Da cellulare il sito va bene dal browser, l’app c’e per Android va, ma preferisco il sito. Sulla licenza Malta Gaming Authority, non e ADM, e va saputo prima. Per ora resto, con la testa a posto.
Marvinsex
October 05, 2026, at 8:56 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/umenshenie-razmera-alimentov/]уменьшение алиментов при рождении третьего ребенка во второй семье[/url] – юристы оценят перспективы снижения выплат, помогут подготовить документы и исковое заявление, представят ваши интересы в суде. Разберём вашу ситуацию и подскажем возможные пути решения с учётом доходов и семейных обстоятельств. Оставьте заявку на сайте и получите бесплатную юридическую консультацию!
Calvinwaync
October 05, 2026, at 9:07 amIf I am being honest this is the kind of site I quietly hope my own work will someday resemble, and a stop at moonbrookdistrict extended that aspirational feeling, finding work that models what I want to produce is part of why I read carefully and this site has been performing that modelling function for me lately consistently.
nonebet_vvEi
October 05, 2026, at 9:14 amI’ve been using Nonebet for about four months now, mostly late nights, and figured I’d say a bit since a few blokes here asked. Registration took me like two minutes — email and a password, that’s it, although the KYC bit showed up when I went to cash out, which is normal enough. Minimum was around $10 which is fine for a casual punter.
There’s a stupid amount of games — they claim over 3,000 slots and tables from memory. Play’n GO dominates, so Sweet Bonanza and Book of Dead are all there. I tend to grind the Megaways stuff when I’m not chasing. Microgaming back catalogue is there as well. The live section runs on Evolution, which means real croupiers, roulette running 24/7 and Crazy Time which I watch more than I play.
The welcome deal was a match up to around $750 with 200 spins, wagering was 35x which honestly is standard for AU-facing sites, not generous. There was a small no deposit thing for a while but don’t count on it. Offers rotate a lot so check the current ones on [url=https://jesusdidsay.com/?p=15536]wyns casino[/url] if you’re thinking about it. The one thing that annoyed me was the max bet rule while wagering — I busted it by accident once and lost the lot. Lesson learned.
Withdrawals have been fine, mostly. Bitcoin withdrawals landed same day both times, e-wallets were 24 hours or so, and the one card withdrawal dragged out to nearly four days which felt long. Funding is instant with Visa, Mastercard or crypto.
Support got back to me in about five minutes at midnight, not just a bot loop once you get past the bot. No app for Nonebet as far as I can tell — it’s just the mobile browser, works well enough on the Android. Licensed out of Curacao, which isn’t the ACMA, obviously, something to be aware of for us down here.
KrisGab
October 05, 2026, at 9:24 amRefreshing to find writing that does not try to manipulate the reader into clicking onto the next page through cliffhangers and forced engagement, and a stop at forestcoveoutpost2 continued in the same respectful way, this is what reader first design actually looks like in practice rather than just in marketing copy that sounds nice.
DavidCax
October 05, 2026, at 9:40 ambook of ra gaminator casino cash games or tournaments igralnica z bonusom brez lastnega vlozka the best online casino online for slovenia players
slot game free delux novoma
BillyTramy
October 05, 2026, at 9:54 amGood morning!
The 9 Numbers That Reveal Your True Financial Health
3 Weeks To Improve Your Communication Skills
Data Analysis: The Real Cost Of Living Crisis And How People Are Adapting
Look on the website – https://mycalculatorland.com/ru/
Success and growth!
DavidCax
October 05, 2026, at 10:01 ambet365 bonus uk casino 15 euro gratis igraj casino igre in osvoji denar free casino games for fun play
free spin no deposit no bonus casino
phjili356
October 05, 2026, at 10:13 amBest slot games I have found in a while. The graphics are crisp and the wins feel fair. Just spent my whole afternoon on phjili356 and had a blast.
DavidCax
October 05, 2026, at 10:19 amcasino riviera online jackpot druga ЕЎansa seznam bonusov brez depozita big 5 casino no deposit bonus
club gold casino online
crazy_rtMt
October 05, 2026, at 11:26 amBazzico su questi tavoli da qualche mese e va detto la ruota mi ha portato piu soddisfazioni di quello che credevo. Non sono certo uno da puntate folli, normalmente piazzo un paio di euro a giro e tanto basta. Il catalogo su Crazy Time e messo bene: si parla di 1800 circa slot contando NetEnt, Play’n GO e Pragmatic, insomma i titoli grossi del calibro di Gates of Olympus, Sweet Bonanza e Book of Dead non mancano.
Il comparto live e gestita da Evolution e la differenza si sente. Ragazzi e ragazze veri, con qualche tavolo italiano nelle ore di punta, e gli show tipo Monopoly Live restano quelli dove passo quasi tutte le serate. Qualche volta controllo le stats dei bonus prima di iniziare, piu per abitudine che per logica.
La promo d’ingresso su Crazy Time in questo periodo e del 100% fino a 300€ piu anche 100 giri gratis, non tutti insieme pero. Esiste anche una decina di euro senza deposito se verifichi i documenti. Il requisito di puntata sta a 35x, che non e regalato, per cui occhio ai termini: trovi i termini precisi andando su [url=https://subodh-urology.com/crazy-time-guida-completa-bonus-metodi-di-pagamento-e-gioco-su-mobile-in-italia/]crazytime[/url] prima di registrarti.
Sui prelievi ho poco da dire. Sono andato di Skrill e l’accredito arriva entro le 24 ore, con Mastercard ci mette 3 giorni buoni. C’e anche Bitcoin, anche se io resto sui bonifici classici. Deposito minimo 20€, l’iscrizione veloce, cinque minuti. La cosa che mi ha dato fastidio e stata la fase documenti: due giorni di attesa e un documento respinto per una sciocchezza.
Il supporto di Crazy Time ti risponde in italiano ed e gia qualcosa, va detto che dopo mezzanotte ci vuole pazienza. Su mobile gira liscio dal browser, l’applicazione su Android c’e ma e migliorabile. Come licenza Malta Gaming Authority, niente ADM, e va saputo prima. Io intanto vado avanti, senza aspettarmi miracoli.
Maxfag
October 05, 2026, at 11:34 amDefinitely returning here, that is decided, and a look at linencovevault only made the case stronger, this is one of those rare websites that rewards regular visits rather than feeling stale after the first read which is something I cannot say about most of the places I bookmark today across all my topics.
crazy_irMt
October 05, 2026, at 11:40 amSto giocando su sti giochi da qualche mese e onestamente il gioco della ruota mi ha dato piu momenti buoni di quanto immaginassi. Non sono il tipo che punta cifre assurde, di solito piazzo due o tre euro a spin e amen. La sezione giochi di Crazy Time e parecchio ricco: fra le 2000 e rotti macchinette contando NetEnt, Play’n GO e Pragmatic, insomma i soliti noti del calibro di Book of Dead e Gates of Olympus sono li al loro posto.
La sezione con i croupier gira su Evolution e la qualita si nota. Ragazzi e ragazze veri, con qualche tavolo italiano nelle ore di punta, e gli show tipo Monopoly Live sono quelli dove butto quasi tutte le serate. Qualche volta do un’occhiata a le statistiche dei bonus round prima di iniziare, non che serva davvero, eh.
La promo d’ingresso su Crazy Time adesso e del 150% fino a 400€ con in aggiunta 200 giri gratis, non tutti insieme pero. Ti danno anche una decina di euro senza deposito se verifichi i documenti. Il rollover e sui 35x, che non e proprio una passeggiata, meglio leggersi il regolamento: si trovano le condizioni complete su [url=https://bisque-dolphin-483506.hostingersite.com/app-crazy-time-passaggi-e-metodi-per-giocare-in-italia/]crazy time[/url] prima di registrarti.
Per i soldi va abbastanza bene. Uso Skrill e una volta Neteller e l’accredito arriva in 12-24 ore, con Mastercard serve 3 giorni buoni. Prendono pure le crypto, anche se io resto sui bonifici classici. Si parte da 10€, la registrazione in tre minuti. L’unica cosa che mi ha rotto e stato il KYC: due giorni di attesa e un documento respinto per una sciocchezza.
L’assistenza di Crazy Time parla italiano e questo aiuta, anche se nelle ore piccole aspetti di piu. Da telefono gira liscio dal browser, l’app c’e per Android c’e ma e migliorabile. Licenza Malta Gaming Authority, niente ADM, e va saputo prima. Io intanto resto, senza troppe pretese.
crazy_amMt
October 05, 2026, at 11:44 amBazzico su queste piattaforme da inizio anno e va detto la ruota mi ha portato piu risultati di quanto pensassi. Non sono certo uno che punta cifre assurde, normalmente metto un paio di euro a giro e tanto basta. Il catalogo di Crazy Time e parecchio ricco: fra le 2000 e passa slot se conti NetEnt, Play’n GO e Pragmatic, per cui i titoli grossi del calibro di Sweet Bonanza, Book of Dead e Gates of Olympus ci sono tutti.
Il comparto live gira su Evolution e si vede. Dealer in carne e ossa, con tavoli in italiano in certe fasce orarie, e i game show sono proprio quelli dove passo quasi tutte le serate. Di tanto in tanto do un’occhiata a le stats dei bonus prima di sedermi, piu per abitudine che per logica.
Il bonus di benvenuto che ti da Crazy Time in questo periodo e del 150% fino a 400€ piu anche 150 free spin, non tutti insieme pero. C’e pure un no deposit da 10€ se verifichi i documenti. Il requisito di puntata e 35x, nella media insomma, quindi leggi le condizioni: puoi trovare i termini precisi andando su [url=https://www.performancepigeondiagnostics.com/2026/10/02/crazy-time-estrazioni-guida-completa-per-giocare-in-italia/]crazy time[/url] prima di registrarti.
Sui prelievi va abbastanza bene. Uso Skrill e mi sono arrivati in mezza giornata circa, con Mastercard ci vogliono un paio di giorni lavorativi. C’e anche Bitcoin, che pero non ho testato. Deposito minimo 10 euro, l’iscrizione rapida. L’unica cosa che mi ha rotto e stata la verifica: mi hanno rifiutato la bolletta due volte per una sciocchezza.
L’assistenza su Crazy Time ti risponde in italiano ed e gia qualcosa, pero nelle ore piccole ci vuole pazienza. Da telefono funziona senza problemi via browser, l’applicazione su Android va, ma preferisco il sito. Licenza MGA di Malta, non e ADM, e va saputo prima. Io intanto continuo, con la testa a posto.
crazy_yhMt
October 05, 2026, at 11:53 amSto giocando su sti giochi da inizio anno e onestamente quella benedetta ruota mi ha portato piu momenti buoni di quanto pensassi. Non sono certo uno che punta cifre assurde, di solito piazzo 3-4 euro a spin e amen. Il catalogo che trovi su Crazy Time e parecchio ricco: fra le 2000 e rotti slot mettendo dentro Pragmatic, Yggdrasil e NetEnt, quindi i classiconi tipo Gates of Olympus, Sweet Bonanza e Book of Dead sono li al loro posto.
La parte live e gestita da Evolution e la qualita si nota. Dealer in carne e ossa, che parlano anche italiano su alcuni tavoli, e i vari game show sono proprio quelli dove passo quasi tutte le serate. Qualche volta controllo le statistiche dei bonus round prima di iniziare, piu per abitudine che per logica.
Il bonus di benvenuto che ti da Crazy Time al momento gira intorno al 150% fino a 400€ con in aggiunta 100 giri gratis, non tutti insieme pero. C’e pure un piccolo no deposit se verifichi i documenti. Il rollover e sui 35x, che non e proprio una passeggiata, quindi leggi le condizioni: puoi trovare i termini precisi su [url=https://violet-opossum-700147.hostingersite.com/crazytime-guida-alla-sicurezza-per-i-giocatori-italiani/]crazy time italia[/url] prima di metterci soldi.
Per i soldi non mi lamento. Sono andato di Skrill e mi sono arrivati in mezza giornata circa, con la carta ci vogliono un paio di giorni lavorativi. Accettano anche crypto, che pero non ho testato. Il minimo per depositare 10€, registrazione veloce, cinque minuti. La cosa che mi ha dato fastidio e stato il KYC: mi hanno rifiutato la bolletta due volte senza un motivo chiaro.
La chat di assistenza su Crazy Time parla italiano il che non e scontato, va detto che di notte ci vuole pazienza. Su mobile gira liscio dal browser, l’app per Android c’e ma e migliorabile. Sulla licenza MGA di Malta, niente ADM, e va saputo prima. Per ora continuo, con la testa a posto.
nonebet_niEi
October 05, 2026, at 11:59 amBeen playing at Nonebet for maybe five months now, mainly late nights, and figured I’d write something up since a mate asked me. Registration took me like two minutes — email, password, done, though the KYC bit hit me later, which every licensed site does anyway. You only need $10 which is fair.
The lobby’s big — they claim over 4,000 games from memory. Pragmatic Play stuff is everywhere, so Gates of Olympus, Big Bass, the usual suspects get pushed hard. I tend to grind Big Time Gaming Megaways when I want longer sessions. NetEnt back catalogue is there as well. Live dealer side is Evolution-powered, so you get real croupiers, roulette running 24/7 and Crazy Time and Monopoly Live which I watch more than I play.
Bonus-wise the offer was 100% up to $500 plus 100 free spins, rollover sits at 35x which honestly is standard for AU-facing sites, not generous. They also had a no-deposit spins offer for a while but it comes and goes. Terms change fairly often so have a look at [url=https://mezquitenurserylandscapes.com/2026/10/wyns-online-casino-bonus-guide/]wyns casino[/url] rather than trusting my numbers. What did get on my nerves was the max bet rule while wagering — I busted it by accident once and the balance got voided. Lesson learned.
Withdrawals have been pretty quick. Crypto came back in under an hour every time I’ve done it, Skrill and Neteller took 24 hours or so, and the one card withdrawal took nearly four days which is the slow lane. Deposits are instant with Visa, Mastercard or crypto.
Support answered me at 2am, not just a bot loop after the first canned reply. No app for Nonebet that I’ve found — it’s just the mobile browser, works well enough on the phone. It’s a Curacao licence, so not local regulation, something to be aware of if you’re in Australia.
crazy_kcMt
October 05, 2026, at 12:05 pmSto giocando su queste piattaforme da un annetto e diciamocelo il gioco della ruota mi ha regalato piu risultati di quello che credevo. Non sono il tipo che sbrocca con le puntate, di solito piazzo un paio di euro a spin e amen. La sezione giochi di Crazy Time e ben fornito: tra le 2000 e passa macchinette mettendo dentro Pragmatic Play, NetEnt e Play’n GO, insomma i soliti noti del calibro di Book of Dead e Gates of Olympus sono li al loro posto.
Il comparto live e roba di Evolution e la differenza si sente. Croupier veri, con tavoli in italiano in certe fasce orarie, e i game show sono proprio quelli dove butto il grosso delle sessioni. Qualche volta do un’occhiata a lo storico dei round bonus prima di sedermi, non che serva davvero, eh.
L’offerta di benvenuto che ti da Crazy Time in questo periodo e del 100% fino a 500€ con in aggiunta 150 free spin, spalmati su qualche giorno. C’e pure un no deposit da 10€ dopo la verifica dei documenti. Il wagering e sui 35x, che non e regalato, meglio leggersi il regolamento: puoi trovare i termini precisi su [url=https://ranktoday.com/blog/app-crazy-time-metodi-di-pagamento-depositi-e-prelievi-veloci-per-gli-utenti-italiani/]crazy time[/url] se ti interessa approfondire.
Sui prelievi non mi lamento. Sono andato di Neteller e i soldi arrivano in mezza giornata circa, con Mastercard ci vogliono 3 giorni buoni. C’e anche Bitcoin, ma non le ho provate. Deposito minimo 10 euro, registrazione in tre minuti. La cosa che mi ha dato fastidio e stata la fase documenti: mi hanno rifiutato la bolletta due volte per una sciocchezza.
L’assistenza su Crazy Time risponde in italiano il che non e scontato, va detto che di notte i tempi si allungano. Da telefono funziona senza problemi via browser, un’applicazione dedicata su Android va, ma preferisco il sito. Come licenza MGA di Malta, quindi non e concessione italiana, e questo per qualcuno e un punto a sfavore. Nel frattempo io vado avanti, senza troppe pretese.
ChrisTog
October 05, 2026, at 12:07 pmAppreciate the thoughtful approach, the writer clearly took time to make this readable for someone who is not already an expert, and a look at daisycoveartisanbazaar kept that going nicely, easy on the eyes and easy on the brain which is always a winning combination when reading on a busy day.
crazy_idMt
October 05, 2026, at 12:08 pmGioco su questi tavoli da un annetto e diciamocelo la ruota mi ha regalato piu soddisfazioni di quanto immaginassi. Non sono certo uno che punta cifre assurde, di solito butto due o tre euro per giro e tanto basta. Il lobby di Crazy Time e messo bene: si parla di 2000 e rotti macchinette mettendo dentro Pragmatic, Yggdrasil e NetEnt, per cui i soliti noti tipo Gates of Olympus, Sweet Bonanza e Book of Dead sono li al loro posto.
Il comparto live e gestita da Evolution e la differenza si sente. Croupier veri, con tavoli in italiano su alcuni tavoli, e gli show tipo Monopoly Live restano quelli dove passo il grosso delle sessioni. Ogni tanto controllo le statistiche dei bonus round prima di sedermi, piu che altro per scaramanzia.
Il bonus di benvenuto proposta da Crazy Time adesso sta sul 100% fino a 500€ piu 200 giri gratis, distribuiti su piu giorni. Esiste anche un no deposit da 10€ una volta caricato il documento. Il requisito di puntata sta a 35x, che non e regalato, per cui occhio ai termini: si trovano le condizioni complete andando su [url=https://icjworld.in/crazytime-guida-completa-alla-verifica-dell-account/]crazy time[/url] prima di metterci soldi.
Sui prelievi ho poco da dire. Sono andato di Skrill e l’accredito arriva in 12-24 ore, con la carta ci vogliono 3 giorni buoni. Accettano anche crypto, ma non le ho provate. Deposito minimo 10€, l’iscrizione in tre minuti. La cosa che mi ha dato fastidio e stato il KYC: prima foto rifiutata senza spiegazioni per una sciocchezza.
La chat di assistenza che trovi su Crazy Time ti risponde in italiano il che non e scontato, pero di notte i tempi si allungano. Su mobile gira liscio dal browser, l’app c’e per Android c’e ma e migliorabile. Come licenza c’e quella maltese MGA, niente ADM, e questo per qualcuno e un punto a sfavore. Per ora resto, senza aspettarmi miracoli.
crazy_nqMt
October 05, 2026, at 12:11 pmGioco su questi tavoli da inizio anno e diciamocelo la ruota mi ha regalato piu momenti buoni di quanto pensassi. Non sono certo uno da puntate folli, normalmente piazzo 3-4 euro a spin e amen. La sezione giochi su Crazy Time e ben fornito: tra le 2000 e passa slot se conti Pragmatic Play, NetEnt e Play’n GO, quindi i classiconi tipo Book of Dead e Gates of Olympus ci sono tutti.
La parte live e roba di Evolution e si vede. Croupier veri, con qualche tavolo italiano su alcuni tavoli, e gli show tipo Monopoly Live restano quelli dove passo il grosso delle sessioni. Qualche volta controllo le stats dei bonus prima di iniziare, non che serva davvero, eh.
Il bonus di benvenuto su Crazy Time al momento e del 100% fino a 300€ piu anche 100 giri gratis, spalmati su qualche giorno. Ti danno anche una decina di euro senza deposito se verifichi i documenti. Il rollover e 35x, che non e regalato, quindi leggi le condizioni: si trovano i dettagli aggiornati su [url=https://www.caseificiogenna.com/crazy-time-italia-guida-completa-a-bonus-registrazione-e-gioco-sicuro/]crazy time italia[/url] prima di registrarti.
Sui prelievi va abbastanza bene. Sono andato di Skrill e i soldi arrivano in mezza giornata circa, con Visa ci vogliono un paio di giorni lavorativi. C’e anche Bitcoin, ma non le ho provate. Il minimo per depositare 20€, l’iscrizione veloce, cinque minuti. La cosa che mi ha dato fastidio e stata la verifica: prima foto rifiutata senza spiegazioni senza un motivo chiaro.
Il supporto su Crazy Time ti risponde in italiano il che non e scontato, pero dopo mezzanotte ci vuole pazienza. Su mobile funziona senza problemi via browser, l’app c’e per Android esiste ma e ancora acerba. Sulla licenza Malta Gaming Authority, non e ADM, cosa che a qualcuno non va giu. Io intanto vado avanti, senza aspettarmi miracoli.
crazy_kaMt
October 05, 2026, at 12:12 pmSto giocando su questi tavoli da un annetto e va detto il gioco della ruota mi ha portato piu momenti buoni di quello che credevo. Non sono certo uno che sbrocca con le puntate, in genere butto un paio di euro a giro e amen. La sezione giochi su Crazy Time e parecchio ricco: si parla di 2000 e rotti macchinette contando NetEnt, Play’n GO e Pragmatic, per cui i classiconi tipo Book of Dead e Gates of Olympus sono li al loro posto.
La sezione con i croupier e roba di Evolution e la qualita si nota. Croupier veri, con tavoli in italiano nelle ore di punta, e i game show sono proprio quelli in cui perdo il grosso delle sessioni. Di tanto in tanto controllo le statistiche dei bonus round prima di entrare, non che serva davvero, eh.
Il bonus di benvenuto su Crazy Time adesso e del 100% fino a 500€ piu anche 150 free spin, non tutti insieme pero. Ti danno anche un piccolo no deposit una volta caricato il documento. Il wagering e 35x, che non e proprio una passeggiata, per cui occhio ai termini: trovi i dettagli aggiornati su [url=https://www.makalutv.com.np/2026/crazy-time-rules-guida-alla-sicurezza/]crazy time[/url] se ti interessa approfondire.
Per i soldi non mi lamento. Uso Skrill e una volta Neteller e l’accredito arriva entro le 24 ore, con Mastercard ci vogliono 3 giorni buoni. Prendono pure le crypto, anche se io resto sui bonifici classici. Si parte da 20€, la registrazione in tre minuti. L’unica cosa che mi ha rotto e stata la verifica: due giorni di attesa e un documento respinto per un motivo assurdo.
L’assistenza di Crazy Time parla italiano il che non e scontato, pero nelle ore piccole ci vuole pazienza. Su mobile il sito va bene dal browser, l’applicazione per Android c’e ma e migliorabile. Come licenza c’e quella maltese MGA, niente ADM, e questo per qualcuno e un punto a sfavore. Io intanto continuo, senza troppe pretese.
nonebet_pmEi
October 05, 2026, at 12:15 pmI’ve been playing at Nonebet for maybe five months now, mostly late nights, and figured I’d say a bit since a mate asked me. Getting an account took no time — email, password, done, although the KYC bit showed up when I went to cash out, which is standard. Minimum was $20 which is fair.
There’s a stupid amount of games — they claim over 4,000 titles last I looked. Play’n GO dominates, so Sweet Bonanza and Book of Dead are sitting right on the front page. I mostly stick to the Megaways stuff when I want longer sessions. NetEnt classics are in there too. The live section runs on Evolution, so you get actual dealers, blackjack tables at all hours and Crazy Time and Monopoly Live if that’s your thing.
The welcome deal when I joined was 100% to $500 with 150 spins, rollover sits at 40x which is standard for AU-facing sites, not generous. They also had a no-deposit spins offer for a while but don’t count on it. Terms change fairly often so check the current ones on [url=https://queensoffice.com/2026/10/02/wyns-casino-minimum-deposit-account-verification-guide-for-australia/]wyns casino[/url] before you claim anything. What did get on my nerves is the $5 max bet cap during bonus play — I busted it by accident once and the balance got voided. My fault, but still.
Withdrawals have been pretty quick. Bitcoin withdrawals landed same day both times, e-wallets took about a day, but the Visa one took three business days which is the slow lane. Funding is instant with Visa, Mastercard and the usual coins.
Support got back to me in about five minutes at midnight, actual humans after the first canned reply. Nonebet doesn’t have a proper app as far as I can tell — it’s a browser thing, works well enough on the Android. It’s a Curacao licence, which isn’t the ACMA, obviously, make of that what you will if you’re in Australia.
Quinngap
October 05, 2026, at 12:17 pmDuring a reading session that included several other sources this one stood out, and a look at outrankoutlet continued the standout quality, the side by side comparison of sources during research is a useful exercise and this site has been winning those comparisons for me consistently across multiple research sessions during the last week.
crazy_cmMt
October 05, 2026, at 12:25 pmBazzico su sti giochi da qualche mese e onestamente la ruota mi ha portato piu momenti buoni di quanto pensassi. Non sono il tipo che punta cifre assurde, di solito piazzo un paio di euro per giro e tanto basta. La sezione giochi di Crazy Time e parecchio ricco: fra le 2000 e passa slot varie contando Pragmatic, Yggdrasil e NetEnt, per cui i soliti noti del calibro di Sweet Bonanza, Book of Dead e Gates of Olympus sono li al loro posto.
Il comparto live e gestita da Evolution e la differenza si sente. Dealer in carne e ossa, con tavoli in italiano in certe fasce orarie, e gli show tipo Monopoly Live sono proprio quelli in cui perdo il grosso delle sessioni. Qualche volta mi guardo lo storico dei round bonus prima di entrare, piu per abitudine che per logica.
Il bonus di benvenuto che ti da Crazy Time adesso sta sul 150% fino a 400€ piu anche 150 free spin, spalmati su qualche giorno. Ti danno anche una decina di euro senza deposito se verifichi i documenti. Il requisito di puntata e sui 35x, nella media insomma, quindi leggi le condizioni: puoi trovare le condizioni complete su [url=https://datalinktour.com/2026/10/02/crazy-time-guida-alla-sicurezza-per-giocare-in-italia/]crazy time[/url] prima di registrarti.
Per i soldi ho poco da dire. Ho usato Skrill e una volta Neteller e l’accredito arriva in 12-24 ore, con Mastercard ci mette 3 giorni buoni. Accettano anche crypto, che pero non ho testato. Si parte da 10€, l’iscrizione veloce, cinque minuti. La cosa che mi ha dato fastidio e stato il KYC: mi hanno rifiutato la bolletta due volte per una sciocchezza.
L’assistenza di Crazy Time ti risponde in italiano il che non e scontato, anche se dopo mezzanotte i tempi si allungano. Su mobile funziona senza problemi via browser, l’applicazione su Android va, ma preferisco il sito. Sulla licenza Malta Gaming Authority, niente ADM, cosa che a qualcuno non va giu. Per ora resto, senza aspettarmi miracoli.
crazy_lwMt
October 05, 2026, at 12:30 pmSto giocando su queste piattaforme da qualche mese e diciamocelo quella benedetta ruota mi ha portato piu momenti buoni di quanto pensassi. Non sono il tipo che sbrocca con le puntate, in genere metto un paio di euro a giro e tanto basta. La sezione giochi su Crazy Time e messo bene: tra le 2000 e rotti slot contando Pragmatic, Yggdrasil e NetEnt, per cui i classiconi del calibro di Gates of Olympus, Sweet Bonanza e Book of Dead non mancano.
La sezione con i croupier e roba di Evolution e la differenza si sente. Croupier veri, con tavoli in italiano nelle ore di punta, e i game show restano quelli dove butto quasi tutte le serate. Di tanto in tanto mi guardo lo storico dei round bonus prima di sedermi, piu che altro per scaramanzia.
Il bonus di benvenuto proposta da Crazy Time adesso sta sul 100% fino a 300€ piu anche 150 free spin, spalmati su qualche giorno. Ti danno anche una decina di euro senza deposito dopo la verifica dei documenti. Il wagering sta a 35x, che non e regalato, meglio leggersi il regolamento: puoi trovare le condizioni complete andando su [url=https://anhthusport.com/stata-crazy-time-cosa-devi-sapere/]crazy time[/url] prima di metterci soldi.
Sul fronte pagamenti va abbastanza bene. Uso Neteller e i soldi arrivano entro le 24 ore, con la carta serve 2-3 giorni. C’e anche Bitcoin, che pero non ho testato. Si parte da 10€, l’iscrizione veloce, cinque minuti. Quello che proprio non mi e piaciuto e stata la fase documenti: mi hanno rifiutato la bolletta due volte per un motivo assurdo.
Il supporto di Crazy Time risponde in italiano il che non e scontato, anche se di notte i tempi si allungano. Da telefono gira liscio dal browser, l’applicazione per Android esiste ma e ancora acerba. Come licenza c’e quella maltese MGA, non e ADM, e va saputo prima. Per ora resto, senza aspettarmi miracoli.
crazy_gaMt
October 05, 2026, at 12:32 pmSto giocando su sti giochi da qualche mese e onestamente quella benedetta ruota mi ha regalato piu risultati di quanto pensassi. Non sono il tipo che sbrocca con le puntate, in genere piazzo due o tre euro per giro e tanto basta. La sezione giochi che trovi su Crazy Time e ben fornito: tra le 2000 e rotti slot mettendo dentro Pragmatic Play, NetEnt e Play’n GO, insomma i titoli grossi come Sweet Bonanza, Book of Dead e Gates of Olympus ci sono tutti.
La parte live gira su Evolution e si vede. Ragazzi e ragazze veri, con tavoli in italiano in certe fasce orarie, e i vari game show restano quelli in cui perdo la maggior parte del tempo. Di tanto in tanto mi guardo lo storico dei round bonus prima di entrare, non che serva davvero, eh.
La promo d’ingresso su Crazy Time adesso gira intorno al 100% fino a 300€ con in aggiunta 100 giri gratis, spalmati su qualche giorno. C’e pure una decina di euro senza deposito dopo la verifica dei documenti. Il rollover sta a 35x, nella media insomma, meglio leggersi il regolamento: trovi i termini precisi direttamente su [url=https://litetechnologies.co.uk/crazy-time-guida-completa-alla-verifica-dell-account/]crazy time[/url] se ti interessa approfondire.
Sul fronte pagamenti ho poco da dire. Ho usato Neteller e i soldi arrivano in 12-24 ore, con Visa serve 2-3 giorni. C’e anche Bitcoin, anche se io resto sui bonifici classici. Il minimo per depositare 20€, l’iscrizione veloce, cinque minuti. Quello che proprio non mi e piaciuto e stata la fase documenti: due giorni di attesa e un documento respinto senza un motivo chiaro.
Il supporto che trovi su Crazy Time ti risponde in italiano il che non e scontato, anche se di notte aspetti di piu. Da telefono gira liscio dal browser, l’applicazione su Android c’e ma e migliorabile. Sulla licenza c’e quella maltese MGA, non e ADM, e va saputo prima. Nel frattempo io vado avanti, senza aspettarmi miracoli.
Anthonyalodo
October 05, 2026, at 12:34 pmhit holidays kranjska gora casino william hill casino no deposit bonus code https://nodepositbonuscasinoslovenia.com captain cook casino rewards
best online casino offers no deposit
nonebet_mzEi
October 05, 2026, at 12:35 pmI’ve been using Nonebet for maybe five months now, mainly on the train home, and thought I’d write something up since a few blokes here asked. Getting an account took no time — email, password, done, although the ID verification came later, which is normal enough. Min deposit was around $10 which suits me.
The lobby’s big — they claim over 3,000 games last I looked. Play’n GO stuff is everywhere, so Gates of Olympus, Big Bass, the usual suspects are all there. I tend to grind the Megaways stuff when I want longer sessions. NetEnt back catalogue is there as well. The live section is Evolution-powered, so you get real croupiers, blackjack tables at all hours plus Crazy Time which I watch more than I play.
Bonus-wise the offer was a match up to around $750 with 200 spins, rollover sits at 40x which is nothing special. There was a small no deposit thing at one point but don’t count on it. Terms change fairly often so check the current ones on [url=https://wall2.rayno.com.tr/2026/10/02/wyns-online-casino-review-overview/]wyns casino[/url] rather than trusting my numbers. What did get on my nerves is the $5 max bet cap during bonus play — I busted it by accident once and the balance got voided. My fault, but still.
Cashouts at Nonebet have been decent. Crypto came back same day every time I’ve done it, Skrill and Neteller took 24 hours or so, but the Visa one dragged out to nearly four days which felt long. Deposits are instant via card, Skrill, Neteller and the usual coins.
Their live chat got back to me in about five minutes at midnight, actual humans after the first canned reply. Nonebet doesn’t have a proper app that I’ve found — it’s a browser thing, but it runs fine on my iPhone. It’s a Curacao licence, which isn’t the ACMA, obviously, something to be aware of if you’re in Australia.
crazy_nxMt
October 05, 2026, at 12:49 pmSto giocando su questi tavoli da qualche mese e diciamocelo il gioco della ruota mi ha portato piu risultati di quello che credevo. Non sono uno che punta cifre assurde, normalmente metto 3-4 euro per giro e via. Il lobby che trovi su Crazy Time e messo bene: tra le 2000 e passa slot se conti NetEnt, Play’n GO e Pragmatic, quindi i titoli grossi tipo Sweet Bonanza, Book of Dead e Gates of Olympus ci sono tutti.
La parte live gira su Evolution e la qualita si nota. Dealer in carne e ossa, con qualche tavolo italiano in certe fasce orarie, e gli show tipo Monopoly Live sono proprio quelli dove passo il grosso delle sessioni. Di tanto in tanto do un’occhiata a lo storico dei round bonus prima di entrare, piu che altro per scaramanzia.
L’offerta di benvenuto su Crazy Time in questo periodo gira intorno al 100% fino a 500€ piu 100 giri gratis, distribuiti su piu giorni. Ti danno anche un no deposit da 10€ una volta caricato il documento. Il rollover e 35x, che non e proprio una passeggiata, meglio leggersi il regolamento: trovi i termini precisi andando su [url=https://green-mongoose-419128.hostingersite.com/2026/10/02/crazy-time-panoramica-e-opzioni/]crazy time[/url] prima di registrarti.
Sul fronte pagamenti non mi lamento. Sono andato di Skrill e i soldi arrivano entro le 24 ore, con la carta ci mette un paio di giorni lavorativi. C’e anche Bitcoin, che pero non ho testato. Il minimo per depositare 20€, la registrazione in tre minuti. L’unica cosa che mi ha rotto e stata la fase documenti: mi hanno rifiutato la bolletta due volte senza un motivo chiaro.
La chat di assistenza su Crazy Time ti risponde in italiano ed e gia qualcosa, anche se di notte i tempi si allungano. Da telefono gira liscio dal browser, l’applicazione per Android va, ma preferisco il sito. Sulla licenza Malta Gaming Authority, non e ADM, cosa che a qualcuno non va giu. Nel frattempo io resto, con la testa a posto.
nonebet_ioEi
October 05, 2026, at 12:55 pmI’ve been playing at Nonebet for something like six months now, mostly late nights, and thought I’d say a bit since a few blokes here asked. Getting an account took no time — email, password, done, although the KYC bit showed up when I went to cash out, which is standard. You only need around $10 which is fine for a casual punter.
There’s a stupid amount of games — they claim over 3,000 slots and tables last I looked. NetEnt dominates, so Gates of Olympus and Sweet Bonanza are all there. My go-to is Big Time Gaming Megaways because the volatility suits me. NetEnt back catalogue is there as well. Live dealer side is Evolution-powered, so you get real croupiers, blackjack tables at all hours plus Crazy Time if that’s your thing.
Bonus-wise the offer when I joined was 100% up to $500 plus 100 free spins, rollover sits at 35x which honestly is nothing special. They also had a small no deposit thing at one point but it comes and goes. Terms change fairly often so it’s worth reading the actual T&Cs at [url=https://clinicacredenciadadetran.com/2026/10/02/wyns-online-casino-registration-steps-for-australian-players/]wyns online casino[/url] if you’re thinking about it. What did get on my nerves was the max bet rule while wagering — I busted it by accident once and the balance got voided. Lesson learned.
Withdrawals have been fine, mostly. Bitcoin withdrawals landed within a couple of hours both times, Skrill and Neteller were 24 hours or so, but the Visa one dragged out to nearly four days which felt long. Funding is instant via card, Skrill, Neteller or crypto.
Their live chat answered me at 2am, actual humans once you get past the bot. No app for Nonebet as far as I can tell — it’s just the mobile browser, but it runs fine on my iPhone. Licensed out of Curacao, so not local regulation, make of that what you will if you’re in Australia.
Anthonyalodo
October 05, 2026, at 12:56 pmcasino online at owner of admiral casino https://casinoigrezadenar.si blackjack not casino rules
casino admiral slovenija
Anthonyalodo
October 05, 2026, at 1:14 pmal capone game casino Which online casino has the best no deposit bonus https://slovenskispletnicasino.com bet365 joining bonus code
free 250r casino online
nemotdral
October 05, 2026, at 2:35 pmЮжнокорейский бренд Atomy давно заслужил признание благодаря строгому следованию стандартам GMP и концепции абсолютного качества по честной цене. На удобной онлайн-витрине https://atomya.ru/ представлен полный ассортимент оригинальной продукции: восстанавливающий уход, экотовары и натуральные биодобавки. Это продуманный выбор для тех, кто ценит безопасность, гармонию и заботу о здоровье семьи.
Alecfut
October 05, 2026, at 2:37 pmAppreciated the way each section connected smoothly to the next without abrupt jumps, and a stop at frostdockartisanbazaar kept that flow going nicely, transitions are something most blog writers ignore but the difference is huge for the reader who is trying to follow a sustained line of thought today across many different topics.
Marvinsex
October 05, 2026, at 2:53 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/umenshenie-razmera-alimentov/]уменьшение алиментов в связи с рождением детей в другом браке[/url] – юристы оценят перспективы снижения выплат, помогут подготовить документы и исковое заявление, представят ваши интересы в суде. Разберём вашу ситуацию и подскажем возможные пути решения с учётом доходов и семейных обстоятельств. Оставьте заявку на сайте и получите бесплатную юридическую консультацию!
Anthonyalodo
October 05, 2026, at 3:31 pmcasino admiral kozina bingo blackjack basic strategy https://slovenskispletnicasino.com online casino free
bet365 bonus code existing customer
Anthonyalodo
October 05, 2026, at 3:52 pmbet365 free spins no deposit book of ra fixed https://casinoigrezadenar.si casino captain cook
automat igre besplatne
JaceCragS
October 05, 2026, at 3:54 pmAppreciated how the writer anticipated the questions a reader might have along the way, and a stop at cottontrailartisanbazaar continued that thoughtful approach, you can tell when content has been edited with the reader in mind versus just published as a first draft and this is clearly the former approach across what I read.
Anthonyalodo
October 05, 2026, at 4:10 pmbook of ra who made casino online at https://spletneigrezadenar.com g ebo casino no deposit bonus codes
online casino lucky lady
Lesterhip
October 05, 2026, at 4:44 pmStarted this morning and finished at lunch with a small sense of having spent the time well, and a look at quickcoveartisanoutlet extended that satisfaction into the afternoon, content that fits naturally into the rhythm of a working day rather than demanding a dedicated reading block is increasingly the kind I prefer.
Antoinezen
October 05, 2026, at 5:31 pmjumba bet free no deposit bonus codes casino bonus brez depozita latvija
free spins rio brezplacne casino igre piramide Igre za pravi denar 2026 party casino free spin junij 219
best crypto online casinos ask gamblers besplatne casino igre za mobitel
666jililogin
October 05, 2026, at 5:58 pmI appreciate how secure this site feels. My transactions are always processed quickly without any hassle. Big thanks to 666jililogin
AnthonyPaype
October 05, 2026, at 6:26 pmcasino midas no deposit bonus codes igrice casino avtomati Igre za denar 2026 casino igre brez pologa bonus
AnthonyPaype
October 05, 2026, at 6:47 pmcasino admiral izola casino captain cook Prevzemite bonus brez vplacila book of ra games online free
AI_User8
October 05, 2026, at 6:59 pmКатегорически приветствую! Пока все вокруг строят из себя умников и писать отчеты со скоростью раненой улитки — я принес вам священный грааль годноты!
Админ этого ресурса собрал просто ультимативный гид, где без всякой заумной чуши и воды учит выжимать из ChatGPT максимум пользы под любые задачи. Реально мануалы для людей, а не для роботов!
Вся база знаний и секретные фишки лежат тут:
[url=https://www.chatgptbezvpn.com/prompty-i-instruktsii/chto-poruchit-chatgpt-kazhdyy-den-7-prostyh-stsenariev-ot-pisma-do-plana-del/]вход в матрицу[/url].
Если после этого ваша жизнь не изменится — я не знаю, че вам еще надо! Бывай!
AnthonyPaype
October 05, 2026, at 7:05 pmWhat online casinos payout to cash app casinoluck free spins no deposit Zahtevajte bonus brez depozita igrice book of ra free
ErikFlunk
October 05, 2026, at 7:32 pmNow wishing more sites covered topics with this level of care, and a look at sageharboroutpost extended that wish across more subjects, the rarity of careful coverage on most topics is a problem and this site is one of the small antidotes to that broader pattern of casual or surface treatment of complex subjects.
Antoinezen
October 05, 2026, at 7:37 pmgolden casino online roadhouse reels casino no deposit bonus codes 2026
best free no deposit casino bonus bet365 casino alternative link Slovenske spletne igralnice 2026 kazino fraj igre
book of ra 6 deluxe free casino korona kranjska gora Г¶ffnungszeiten
Antoinezen
October 05, 2026, at 7:50 pmbet365 free spins no deposit admiral casino trzin
live casino book of ra casino hotel admiral skofije Zabava na avtomatih casino bonus free chip
poker online live hit casino kranjska gora
BillyTramy
October 05, 2026, at 8:05 pmHello!
How Ignoring Advice Can Lead To Better Decisions
The Real Cost Of Free Apps And Why Nothing Is Actually Free
Why Being Consistent Is More Important Than Being Intense
More information on the website – https://mycalculatorland.com/ru/
Goodbye!
Petersom
October 05, 2026, at 8:37 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/priznanie-braka-nedeystvitelnym/]юридическая консультация по признанию брака фиктивным[/url] – юрист оценит основания для обращения в суд, изучит обстоятельства заключения брака, подготовит необходимые документы и поможет выстроить правовую позицию. Получите консультацию по признанию брака недействительным или фиктивным и узнайте, какие доказательства потребуются в вашей ситуации.
Antoinezen
October 05, 2026, at 8:44 pmbet 365 singup bonus free spins casino no deposit november 2026
casino mond slovenia winward guess it for 25 free spin Katere igre so za denar? how to play blackjack
free online casino free casino games for fun play
CharlesZet
October 05, 2026, at 9:04 pmhttps://www.newgenstravel.com/forum/topic/73661/shilajit-capsules-%7C-natural-energy,-stamina–amp;-vitality-support
HaywoodFar
October 05, 2026, at 9:11 pmvirtual casino no deposit bonus codes casino igre lucky lady
videoslots games with frequent free spins hit kranjska gora casino kontakt Najboljsi casino bonusi v Sloveniji free slot machine games
Еѕrebanje jackpot v Еѕivo yukon gold casino free spins no deposit
Bobbynet
October 05, 2026, at 9:21 pmmigliori casino online betfair online casino Casino igre slot live casino europe
kalibrovka_loKa
October 05, 2026, at 9:22 pmДля обеспечения точности измерений важно своевременно провести [url=https://kalibrovka-kalibrov.ru/]калибровка калибров[/url].
Это помогает выявить возможные отклонения и принять необходимые меры.
HaywoodFar
October 05, 2026, at 9:24 pmbook of ra no deposit casino online games
twist casino no deposit bonus casino igre kleopatra Kje igrati za pravi denar na spletu? online casino igre besplatno
online kazino slovenija grand casino admiral zagreb
Jerrysnoli
October 05, 2026, at 9:25 pmVavada galda spelu sadala pieejama rulete, blekdzeks, bakara un pokers desmitiem variaciju no dazadam studijam. Kataloga filtri pec piegadataja, mehanikas un svarstiguma saglabajas starp apmeklejumiem ka nosaukti prieksiestatijumi. Aktuala adrese: [url=https://egeunisk.org/]https://egeunisk.org/[/url] Sada kompetence tikla limeni paplasina platformas pieejamibu regionos ar stingru satiksmes filtresanu.
Bobbynet
October 05, 2026, at 9:43 pmcasino kingdom online casino besplatne casino igre aparati Najboljsi Bonusi V Sloveniji energy casino free spins 2026
Bobbynet
October 05, 2026, at 10:01 pmeu casino online hit casino kranjska gora restaurant Igralni avtomati za zabavo in igranje na sreco best free gambling sites
HaywoodFar
October 05, 2026, at 10:19 pmlive casino online working in slovenia casino games free slots online
free online poker best sites casinoluck free spins no deposit Spletna igralnica za pravi denar zodiac casino no deposit
brezplaДЌne casino spletne igre online poker free money
TechBro46
October 06, 2026, at 12:04 amВсем салют! Кому тут надоело писать отчеты со скоростью раненой улитки — ловите просто термоядерный инсайд!
Какой-то гений выкатил нереально бодрый блог, где чисто на пальцах и с юморком учит выжимать из ChatGPT максимум пользы под любые задачи. Я залип на два часа, теперь чувствую себя богом продуктивности.
Короче, хорош тупить, кликайте и забирайте инструкции:
[url=https://www.chatgptbezvpn.com/prompty-i-instruktsii/kak-poprosit-chatgpt-sostavit-voprosy-dlya-delovoy-vstrechi-gotovyy-prompt-i-proverka/]смотреть гайды[/url].
Если после этого ваша жизнь не изменится — я не знаю, че вам еще надо! Всех обнял!
Bobbynet
October 06, 2026, at 12:15 amcasino bonus brez pologa What casino games can win real money Brezplacni slot avtomati all star slots no deposit bonus codes 2026
HaywoodFar
October 06, 2026, at 12:23 amanswers to the guess game casino fone casino no deposit bonus thebigfreechiplist
bonus free bet no deposit book of ra game free download Najboljsi bonusi 2026 apollo slots casino free 300
jackpot city casino big win jackpot zrebanje kdaj
Nickwhiff
October 06, 2026, at 12:35 amWill recommend this to a couple of friends who have been asking about this exact topic, and after zencovevault I have even more reason to do so, the kind of site that earns word of mouth rather than chasing it through aggressive marketing or paid placements is always a treat to find online.
HaywoodFar
October 06, 2026, at 12:36 amblackjack casino rewards zodiac casino sign up
best free no deposit casino bonus online casino for eu Igrajte igre na avtomatih casino kranjska gora restaurant
online casino paypal deposit jackpot bonus runda
Bobbynet
October 06, 2026, at 12:36 amplay free slots new jackpot capital no deposit bonus Vodnik po igrah na avtomatih hopa casino free spins no deposit
Bobbynet
October 06, 2026, at 12:55 ambet365 bonus slovenija casino bonus 10 Bonusi igralnic slovenske casino online
losulsDup
October 06, 2026, at 1:02 amНадежная транспортировка грузов требует проверенных решений и абсолютной дорожной безопасности. Компания «ТехноСаф» предлагает выносливые легковые прицепы категорий B и E, а также сертифицированные фаркопы. Изучить модели и получить консультацию экспертов позволяет сайт https://xn--e1afucc1bzb.xn--80ajyepctd.xn--p1ai/ где собрана проверенная техника с заводской гарантией качества и сервисным монтажом под ключ.
HaywoodFar
October 06, 2026, at 1:28 amDoes Casinobit IO have a no deposit bonus play free slot games online
platinum reels no deposit bonus bresplacne casino igre Igralni avtomat Book of Ra v spletni igralnici casino admiral ptuj
sign up casino free spins 2026 slovenija blackjack bet 365
HaroldFem
October 06, 2026, at 1:54 amBookmark earned and folder updated to track this site separately, and a look at foreststonecourtyard confirmed the folder upgrade was the right call, organising my reading list so that good sites do not get lost in a sea of casual bookmarks is something I do more carefully now and this site warranted its own spot.
RodolfoDriew
October 06, 2026, at 1:59 amFelt energised after reading rather than drained, which is unusual for online content these days, and a look at granitegroveemporium continued that good feeling, content that leaves you better than it found you is rare and worth bookmarking when you stumble across it for the first time today or any other day really.
crazy_riMt
October 06, 2026, at 2:03 amBazzico su questi tavoli da inizio anno e diciamocelo quella benedetta ruota mi ha portato piu risultati di quanto immaginassi. Non sono certo uno che punta cifre assurde, di solito piazzo 3-4 euro a spin e tanto basta. Il lobby di Crazy Time e ben fornito: tra le 1800 circa slot varie se conti Pragmatic, Yggdrasil e NetEnt, per cui i titoli grossi come Sweet Bonanza, Book of Dead e Gates of Olympus non mancano.
Il comparto live e gestita da Evolution e la differenza si sente. Ragazzi e ragazze veri, con tavoli in italiano su alcuni tavoli, e i vari game show restano quelli dove passo la maggior parte del tempo. Di tanto in tanto controllo le statistiche dei bonus round prima di entrare, non che serva davvero, eh.
La promo d’ingresso proposta da Crazy Time al momento gira intorno al 100% fino a 300€ piu 200 giri gratis, distribuiti su piu giorni. C’e pure un piccolo no deposit se verifichi i documenti. Il requisito di puntata e 35x, nella media insomma, meglio leggersi il regolamento: trovi i dettagli aggiornati andando su [url=https://grey-jackal-479588.hostingersite.com/uncategorized/crazy-time-stat-i-migliori-metodi-di-pagamento-per-giocare-online/]crazy time[/url] prima di metterci soldi.
Per i soldi non mi lamento. Sono andato di Neteller e i soldi arrivano in 12-24 ore, con Visa ci vogliono 2-3 giorni. C’e anche Bitcoin, che pero non ho testato. Si parte da 10€, l’iscrizione veloce, cinque minuti. La cosa che mi ha dato fastidio e stata la fase documenti: mi hanno rifiutato la bolletta due volte senza un motivo chiaro.
Il supporto di Crazy Time parla italiano il che non e scontato, va detto che nelle ore piccole i tempi si allungano. Su mobile gira liscio dal browser, un’applicazione dedicata c’e per Android c’e ma e migliorabile. Licenza c’e quella maltese MGA, non e ADM, e questo per qualcuno e un punto a sfavore. Per ora continuo, senza aspettarmi miracoli.
crazy_bjMt
October 06, 2026, at 2:03 amSto giocando su questi tavoli da un annetto e diciamocelo quella benedetta ruota mi ha regalato piu soddisfazioni di quanto immaginassi. Non sono il tipo che sbrocca con le puntate, normalmente butto 3-4 euro a giro e via. Il catalogo di Crazy Time e messo bene: fra le 2000 e rotti macchinette se conti Pragmatic, Yggdrasil e NetEnt, insomma i soliti noti del calibro di Sweet Bonanza, Book of Dead e Gates of Olympus non mancano.
Il comparto live gira su Evolution e si vede. Dealer in carne e ossa, che parlano anche italiano su alcuni tavoli, e i vari game show restano quelli dove butto quasi tutte le serate. Ogni tanto mi guardo lo storico dei round bonus prima di sedermi, non che serva davvero, eh.
La promo d’ingresso proposta da Crazy Time al momento sta sul 100% fino a 500€ piu anche 200 giri gratis, non tutti insieme pero. Ti danno anche un no deposit da 10€ dopo la verifica dei documenti. Il rollover sta a 35x, che non e regalato, meglio leggersi il regolamento: trovi i termini precisi direttamente su [url=https://eletromaza.com.br/crazy-time-italia-guida-completa-a-bonus-pagamenti-e-sicurezza/]crazytime[/url] se ti interessa approfondire.
Sui prelievi non mi lamento. Sono andato di Skrill e una volta Neteller e l’accredito arriva in mezza giornata circa, con Visa serve 2-3 giorni. Accettano anche crypto, ma non le ho provate. Deposito minimo 10 euro, l’iscrizione in tre minuti. L’unica cosa che mi ha rotto e stata la fase documenti: mi hanno rifiutato la bolletta due volte per una sciocchezza.
La chat di assistenza che trovi su Crazy Time parla italiano e questo aiuta, pero nelle ore piccole i tempi si allungano. Da cellulare gira liscio dal browser, l’applicazione su Android c’e ma e migliorabile. Licenza MGA di Malta, niente ADM, cosa che a qualcuno non va giu. Io intanto vado avanti, con la testa a posto.
Admin_SEO96
October 06, 2026, at 2:10 amЙоу, народ! Пока все вокруг строят из себя умников и ломать мозг над промтами для ChatGPT — ловите просто термоядерный инсайд!
Тут ребята собрал просто ультимативный гид, где чисто на пальцах и с юморком показывает, как одной кнопкой решать геморрой в Excel и Word. Реально мануалы для людей, а не для роботов!
Короче, хорош тупить, кликайте и забирайте инструкции:
[url=https://www.chatgptbezvpn.com/prompty-i-instruktsii/kak-poprosit-chatgpt-sostavit-plan-obucheniya-pod-tsel-i-svobodnoe-vremya/]ChatGPT Гид[/url].
Все бесплатно, без регистрации и СМС, как в старые добрые! Пользуйтесь, не благодарите!
crazy_adMt
October 06, 2026, at 2:51 amSto giocando su queste piattaforme da qualche mese e onestamente il gioco della ruota mi ha regalato piu soddisfazioni di quanto pensassi. Non sono uno che sbrocca con le puntate, normalmente metto 3-4 euro per giro e via. Il lobby di Crazy Time e parecchio ricco: tra le 2000 e passa slot mettendo dentro Pragmatic Play, NetEnt e Play’n GO, per cui i titoli grossi del calibro di Book of Dead e Gates of Olympus non mancano.
La parte live e roba di Evolution e si vede. Ragazzi e ragazze veri, che parlano anche italiano su alcuni tavoli, e i vari game show sono proprio quelli dove butto quasi tutte le serate. Di tanto in tanto mi guardo lo storico dei round bonus prima di sedermi, piu per abitudine che per logica.
Il bonus di benvenuto che ti da Crazy Time al momento gira intorno al 150% fino a 400€ piu anche 100 giri gratis, distribuiti su piu giorni. C’e pure un piccolo no deposit se verifichi i documenti. Il wagering e 35x, nella media insomma, quindi leggi le condizioni: si trovano i dettagli aggiornati direttamente su [url=https://daneshtahlil.com/crazy-time-italia-guida-all-app-e-all-esperienza-mobile/]crazy time[/url] se ti interessa approfondire.
Sul fronte pagamenti non mi lamento. Sono andato di Neteller e l’accredito arriva in 12-24 ore, con Visa serve 3 giorni buoni. Accettano anche crypto, ma non le ho provate. Deposito minimo 10€, la registrazione in tre minuti. La cosa che mi ha dato fastidio e stata la fase documenti: mi hanno rifiutato la bolletta due volte per una sciocchezza.
La chat di assistenza che trovi su Crazy Time ti risponde in italiano ed e gia qualcosa, va detto che dopo mezzanotte ci vuole pazienza. Da telefono il sito va bene dal browser, un’applicazione dedicata c’e per Android c’e ma e migliorabile. Licenza c’e quella maltese MGA, quindi non e concessione italiana, cosa che a qualcuno non va giu. Nel frattempo io resto, senza aspettarmi miracoli.
kratonbetkr
October 06, 2026, at 3:02 amReally impressed with the security and the way they handle transactions. Everything feels safe and professional at kratonbetkr.
nonebet_acEi
October 06, 2026, at 3:02 amBeen playing at Nonebet for about five months now, mostly late nights, and figured I’d say a bit since a mate asked me. Registration took me like two minutes — email and a password, that’s it, though the KYC bit hit me later, which is standard. Minimum was $10 which is fair.
The lobby’s big — somewhere north of 3,000 titles from memory. Play’n GO stuff is everywhere, so Sweet Bonanza and Book of Dead get pushed hard. I mostly stick to Yggdrasil and Betsoft titles when I’m not chasing. Microgaming back catalogue is there as well. Live dealer side is Evolution-powered, so you get real croupiers, roulette running 24/7 and Crazy Time and Monopoly Live which I watch more than I play.
Bonus-wise the offer was a match up to around $750 with 200 spins, rollover sits at around 35x which is about average. They also had a small no deposit thing at one point but it comes and goes. Terms change fairly often so check the current ones on [url=https://888gjapp.com.pk/wyns-casino-sports-registration-steps-for-australian-players/]wyns casino[/url] if you’re thinking about it. What did get on my nerves was the max bet rule while wagering — I busted it by accident once and lost the lot. Lesson learned.
Cashouts at Nonebet have been pretty quick. Bitcoin withdrawals landed in under an hour every time I’ve done it, Skrill and Neteller were 24 hours or so, but the Visa one dragged out to nearly four days which felt long. Deposits are instant via card, Skrill, Neteller or crypto.
Their live chat answered me at 2am, not just a bot loop after the first canned reply. No app for Nonebet that I’ve found — it’s a browser thing, but it runs fine on my phone. Licensed out of Curacao, which isn’t the ACMA, obviously, something to be aware of for us down here.
Bobbynet
October 06, 2026, at 3:11 am32 online casino sign up casino free spins 2026 Igralni avtomati, ki jih lahko igrate brezplacno casino bonus brez depozita latvija
HaywoodFar
October 06, 2026, at 3:29 ambet365 it app best casino in slovenia
big time gaming free slots live casino online games Igralnica Hell Spin Slovenija gametwist slots free slot machines casino games
besplatne casino igre gaminator chilli pop slot free spin real money
Bobbynet
October 06, 2026, at 3:32 amWhich bet gives you a bonus without deposit Which gambling sites give free spins Igralnica na internetu casino korona kranjska gora Г¶ffnungszeiten
HaywoodFar
October 06, 2026, at 3:42 ambet online casino lovenia intertops red casino no deposit bonus
can you play poker on pokerstars for free ЕЎportne stave v Еѕivo Igralni avtomat Book of Ra v spletni igralnici bet 365 kopija vozniЕЎkega dovoljenja
casino igre demo casino online free spins
Bobbynet
October 06, 2026, at 3:50 amnakup paysafecard preko interneta casino princess slovenia Katera je slovenska spletna igralnica za vas? nakup paysafecard preko interneta
HaywoodFar
October 06, 2026, at 4:35 amgaming club casino 30 free spins online casino slots
free online slots no download free spin games Pregled brezplacnih avtomatov slovenia casino online
kako igrati igre v kazinu 247 free poker
KellyLirty
October 06, 2026, at 4:49 amNow wishing I had found this site sooner, and a look at mythicmint extended that mild regret, the calculation of how many years of good content I missed by not finding the right sources earlier is one I try not to make too often but it does come up sometimes when I find sites this good.
StefanHab
October 06, 2026, at 4:51 amLooking at this objectively the editorial quality is hard to deny even setting aside personal taste, and a stop at nightorchardvault maintained the same objective quality, the gap between what I personally enjoy and what is objectively well crafted exists and this site clears both bars simultaneously which is rarer than it sounds.
JackNak
October 06, 2026, at 5:02 amApproaching this with the usual skepticism I bring to new sites and being slowly persuaded, and a stop at wheatcoveartisanoutlet continued that gradual persuasion, the careful path from skeptical reader to genuine fan is the only one I trust and this site has walked me along that path through patient consistent quality across pieces.
Bobbynet
October 06, 2026, at 6:05 amWhat gambling sites give you free spins no deposit casino poker games Kje najti slovenske spletne igralnice? zodiac casino 1 deposit
Bobbynet
October 06, 2026, at 6:26 amfree online casino book of ra games Paysafecard igralnica 2026 casino admiral slovenija
HaywoodFar
October 06, 2026, at 6:38 amaristocrat free slot games mgm online casino
slot igrice book of ra casino brez depozita slovenija Igralni avtomati casino bonus brez depozita 5 euro
casumo online casino brezplaДЌne casino spletne igre
Bobbynet
October 06, 2026, at 6:45 amWhich gambling site has the best welcome bonus diamond world casino no deposit bonus codes Bonusi spletnih igralnic, ki so na voljo v Sloveniji welcome bonus no deposit
HaywoodFar
October 06, 2026, at 6:50 amblackjack casino online casino list mansion online casino
napoli casino no deposit bonus codes argo casino no deposit bonus Slovenska spletna igralnica 2026 casino princess slovenia
hit casino kranjska gora jackpot kako se igra blackjack
PeterSaita
October 06, 2026, at 7:43 ambit games casino free spin no deposit casino cashout mastercard europa
poker igre za denar spletno kazino slovenija Katera spletna igralnica je najboljsa? slot game free casino 3888
25 free bonus no deposit leovegas free spins
BillyTramy
October 06, 2026, at 7:55 amGood afternoon!
Predictions: How Smart Cities Will Use Data To Improve The Quality Of Life
The 7 KPIs That Show Your Automation Is Working
Statistical Insights: The Impact Of Automation On The Manufacturing Sector
Look on the website – https://mycalculatorland.com/ru/
All the best!
HermanVot
October 06, 2026, at 7:57 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/ustanovlenie-rodstva/]установить факт родственных отношений для принятия наследства[/url] – поможем установить факт родства в судебном порядке, в том числе с умершим родственником, для вступления в наследство, оформления документов и решения других юридических вопросов. Юрист оценит ситуацию, поможет собрать доказательства, подготовит заявление в суд и сопроводит дело до получения решения. Консультация по установлению родственных отношений и защите ваших прав.
EdwardReiny
October 06, 2026, at 8:20 amhttps://intercom.help/bestpromo/en-ca/collections/19758156-francophone-reward-centre
AndrewKEYMN
October 06, 2026, at 8:44 amhttps://intercom.help/bestpromo/en-ca/collections/19758214-player-offer-manual
Davidchums
October 06, 2026, at 9:00 ameuro king online casino download free casino slot games to play Vrtljivi avtomati level up casino
Davidchums
October 06, 2026, at 9:21 ambesplatne casino igre za igranje book of ra free mobile Je WinShark varna igralnica? casino bled bizi
Davidchums
October 06, 2026, at 9:39 am24bettle casino no deposit bonus free chip no deposit casino bonus codes Najboljsi bonusi 2026 free spins rio casino
Chesterhoist
October 06, 2026, at 9:45 amblackjack vs baccarat treasure mile casino no deposit bonus codes 2026
casino game lucky lady play zeus slots for free Vodnik po spletnih igrah za denar What online casino has free bonus without deposit
book of ra bonus buy fxlider no deposit bonus
Chesterhoist
October 06, 2026, at 9:58 amvirtual casino no deposit bonus codes korona casino hotel kranjska gora slovenia
what are free spins bet365 casino best game Igre iz spletne igralnice casino cezar cash game
live casino gratuit casino bonus free
Chesterhoist
October 06, 2026, at 10:50 amvirtual casino no deposit bonus 2026 online casino book of ra
casino book of ra deluxe captain cooks casino play Spletna Igralnica online casino free
yebo casino no deposit bonus codes jackpot druga ЕЎansa
Leroyfug
October 06, 2026, at 11:34 amтоп застройщиков
Davidchums
October 06, 2026, at 11:54 ampoker bet 365 slovenija party casino free spins Igralni avtomati v igralnici 2026 casino online multipla
Davidchums
October 06, 2026, at 12:15 pmvegas play casino no deposit bonus code 2026 kazino igre online Igranje za denar v igralnici book of ra unibet
DwayneCit
October 06, 2026, at 12:26 pmWithout overstating it this is a quietly excellent post, and a look at aurorastonecollective extended that quiet excellence, content that earns superlatives without demanding them through marketing language is content that has truly earned them through the substance and this site has clearly produced work in that earned excellence category today.
Davidchums
October 06, 2026, at 12:33 pmage of the gods free slot captain jack casino free 500 Spletna igralnica, kjer lahko igrate za pravi denar casino bet365 promotions opening bonus
Chesterhoist
October 06, 2026, at 12:52 pmwild vegas casino no deposit bonus codes casino games for sale
casino online nl the best online casino for slovenian players Pregled bonusov igralnic kdaj je Еѕrebanje lota
online casinos slovenia slovenia casino hotel
Chesterhoist
October 06, 2026, at 1:05 pmleovegas free spins jackpot cash casino no deposit bonus codes
blackjack casino rewards slot igre free Primerjava iger za pravi denar blackjack not real money
cyberspins casino free spins codes casino igre sizzling hot
LindaWat
October 06, 2026, at 1:09 pmХочешь регулярный секс,найди секс партнера прямо сейчас. Знакомства в Новосибирске
[url=https://lifelove24.site/main/user/sladko_pusi_1.html ]хочу познакомиться[/URL]
HermanVot
October 06, 2026, at 1:51 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/ustanovlenie-rodstva/]юридические услуги по определению родственных отношений[/url] – поможем установить факт родства в судебном порядке, в том числе с умершим родственником, для вступления в наследство, оформления документов и решения других юридических вопросов. Юрист оценит ситуацию, поможет собрать доказательства, подготовит заявление в суд и сопроводит дело до получения решения. Консультация по установлению родственных отношений и защите ваших прав.
Chesterhoist
October 06, 2026, at 1:57 pmanubis free spins europalace online casino
casino kingdom online casino casino bonus brez depozita slovenija Kolo ruleta na spletu nine casino bonus code
online casino x kako brojati karte u blackjack
KARONReiny
October 06, 2026, at 2:36 pmhttps://intercom.help/bestpromo/bg/collections/19758282-архив-на-предимствата-за-играчи
Davidchums
October 06, 2026, at 2:48 pm4 days 5 free spin casino casino register bonus slovenija Igre casino za pravi denar free spins rio casino
EUSEBIAKEYMN
October 06, 2026, at 2:58 pmhttps://intercom.help/bestpromo/fa-IR/collections/19727992-%D9%BE%D8%A7%D8%AF%D8%A7%D8%B4-%D9%87%D8%A7%DB%8C-%D8%AE%D9%88%D8%B4%D8%A7%D9%85%D8%AF%DA%AF%D9%88%DB%8C%DB%8C-%DA%A9%D8%AF%D9%87%D8%A7-%D9%88-%D8%B4%D8%B1%D8%A7%DB%8C%D8%B7
Davidchums
October 06, 2026, at 3:09 pmroyal panda online casino old havana casino no deposit bonus Igre na avtomatih na spletu casino rio central igralni salon ljubljana slovenia
Davidchums
October 06, 2026, at 3:27 pmonline casino bonus slovenia free spins weekly cashout Preizkusite igralnico Hell Spin golden star casino
Chesterhoist
October 06, 2026, at 3:58 pmeuro king online casino download e stave stavna lista danes
blackjack 6 deck zodiac casino 1 Paysafecard igralnica 2026 poker sites with free bonuses without deposit
vulkanvegas extra free spins casino igre brez pologa bonus 10
Chesterhoist
October 06, 2026, at 4:10 pmfree poker tournaments Which gambling site has the best welcome bonus
blackjack house edge calculator bingohall online casino Igrajte igre na avtomatih no deposit bonus casino malta
bitstarz casino no deposit bonus codes casino ljubljana slovenia
MackSKell
October 06, 2026, at 4:34 pmPicked up several practical tips that I plan to try out this week, and a look at kettlegroveboutiquehouse added a few more I will be testing alongside, content with practical hooks that connect to my actual life is the kind that earns my repeat attention rather than the merely interesting that I forget within a day.
Chesterhoist
October 06, 2026, at 5:02 pmbook of ra download casino bonus 5 euro
play zeus slots for free 30 euro no deposit bonus casino WinShark book of ra paytable
ilucki free spins free spin games
dostavka_yhOa
October 06, 2026, at 5:13 pm[url=http://alkogol-dostavka-moskva-xpr.ru/]заказать алкоголь с доставкой москва[/url]
В современном мире всё больше людей предпочитает заказывать алкоголь с доставкой .
Многие компании предлагают быстрый и удобный сервис по доставке напитков прямо к вашему порогу .
Основными преимуществами являются широкий выбор напитков и удобство заказа .
Ключевым фактором является рейтинг и надежность сервиса.
Процесс оформления прост и понятен, что позволяет сэкономить время .
Удобно, что есть возможность получить профессиональную помощь при выборе.
Покупатели могут выбрать из широкого спектра брендов и видов алкоголя.
На стоимость влияет качество, объем и эксклюзивность напитка .
Многие сервисы проводят акции и предоставляют скидки для постоянных клиентов .
В большинстве случаев доставка возможна в тот же день.
Заказ с доставкой возможен как в будние, так и в выходные дни.
Сотрудники аккуратно упаковывают напитки, чтобы избежать повреждений .
Компания обязана проверять возраст получателя и осуществлять контроль .
Для клиента важно убедиться в надежности выбранной службы.
Правильный выбор сервиса гарантирует безопасность и качество заказанных напитков.
dostavka_wxsn
October 06, 2026, at 5:13 pmЕсли вы ищете надежную [url=https://alkogol-dostavka-moskva-247-2.ru/]доставка алкоголя по Москве круглосуточно[/url] — мы всегда поможем вам насладиться любимыми напитками, не выходя из дома.
Сегодня многие предпочитают заказывать алкоголь с доставкой .
В большинстве случаев клиентам доступен разнообразный ассортимент алкоголя, который можно заказать прямо на дом .
Заказать алкоголь через интернет удобно и быстро: нужно выбрать товары, заполнить форму и оплатить .
Многие компании гарантируют быструю доставку, чтобы покупатель получил свои напитки максимально быстро .
Такой сервис особенно актуален в праздники, когда в обычных магазинах часто нет нужных напитков .
Многие компании предлагают акции и скидки для постоянных клиентов.
Обеспечение безопасности и качества — важнейшие аспекты работы служб доставки алкоголя .
Заказывая алкоголь с доставкой, пользователь получает возможность выбрать подходящий напиток, не выходя из дома .
NormanSow
October 06, 2026, at 5:41 pmrtg casino online spletno kazino slovenija Spletne igralniske igre za vsak okus free casino roulette games
NormanSow
October 06, 2026, at 6:02 pmvegas slots online casino bet365 bonus code for existing customers Spletne igre za denar 2026 hitstars online casino slo
Knoxjam
October 06, 2026, at 6:08 pmLiked how the writer used real examples instead of theoretical ones to make the points stick, and a stop at apricotharborvault added even more concrete examples, this is the kind of practical approach that respects readers who actually want to apply what they learn rather than just nodding along passively without doing anything useful.
brigada_yjmn
October 06, 2026, at 6:29 pmДля организации церемонии вы можете обратиться к [url=https://brigada-soprovozdeniya-na-pohoronah.ru/]бригада сопровождения на похоронах[/url], которая обеспечит профессиональное сопровождение.
Бригада сопровождения на похоронах играет важную роль часто привлекается для обеспечения торжественной и dignified церемонии. Их задача — сделать прощание максимально гладким и трогательным . В их обязанности входит контроль за соблюдением порядка, взаимодействие с гостями и организация процедур в соответствии с традициями.
Первая часть работы бригады — подготовка места прощания . Они отвечают за интерьер, оформление зала и соблюдение порядка, что помогает создать уважительную атмосферу. Эти специалисты также взаимодействуют с родственниками и другими служащими, чтобы всё прошло без сбоев, с соблюдением всех правил.
Во время церемонии бригада сопровождает родственников и гостей . Они следят за соблюдением порядка, помогают с организацией речей и помогают гостям развлечься и проявить сострадание. Их участие — важнейшее условие для достойного и трогательного прощания.
После завершения церемонии бригада сопровождает похоронную процессию до кладбища . В эти моменты их задача — поддержать родственников и обеспечить плавный переход к следующему этапу. Эти специалисты помогают создать атмосферу спокойствия и уважения для всех участников прощания.
ForestPaicy
October 06, 2026, at 6:35 pmIf a friend asked me where to read carefully on the topic I would send them here without hesitation, and a look at zencoveoutpost confirmed the recommendation strength, the directness of my recommendation reflects how confident I am in the quality and this site has earned undiluted recommendations from me across multiple recent conversations actually.
Erikglync
October 06, 2026, at 6:36 pmNow feeling the small relief of finding writing that does not condescend, and a stop at woodmeadowoutlet extended that respect for readers, content that treats its audience as capable adults rather than as people to be managed produces a different reading experience and this site has clearly chosen the respectful approach across all pieces.
Michaelcem
October 06, 2026, at 7:05 pmslovenia live casino double deck blackjack
real money casino games casino no deposit bonus codes Igralni avtomati 2026 igre casino online
zodiac casino eu casino admiral kontakt
Michaelcem
October 06, 2026, at 7:17 pmthe best online casino online for slovenia players online casino game
twist casino no deposit bonus codes vegas country casino no deposit bonus code Paysafecard spletna igralnica larix kranjska gora casino
bet365 poker bonus no deposit bonus 2026
blacksprutRag
October 06, 2026, at 7:52 pm[center][b]BlspAt — актуальные ссылки 2026[/b][/center]
[center][i]Свежие ссылки без VPN[/i][/center]
[center][url=https://blsp-at.vip][img]https://black-sprut.top/images/logo.png[/img][/url][/center]
Всем привет! Делюсь проверенными переходниками на BLSP AT — крупный анонимный маркетплейс.
Сайт открывается нормально — важно только использовать правильный вход. Вот три рабочих способа:
[list=1]
[*] [url=https://blsp-at.vip]Актуальный адрес blsp at — без VPN[/url]
[*] [url=https://blacksprut-darknet.sbs]Блэкспрут — вход без TOR[/url]
[*] [url=https://bleksprut.icu]Блекспрут официальный — актуальная ссылка[/url]
[/list]
В случае если какой-то переходник не работает — пробуйте следующий. Каждая приведёт официальную площадку.
Добавляйте в закладки — пригодится. Отписывайтесь если что.
[size=1][color=#333333]blsp at, https blsp at, blsp at сайт, m blsp at, k blsp at, v blsp at, n blsp at, blsp ap, blsp at check, blsp at клады, blsp at вход, blsp ay, blsp am, blsp com, blsp cc, blsp ссылка, bc blsp at, ntt k blsp at, w blsp at, blsp at отзывы, blsp at зеркало, blsp at 18, blsp at my balance, blsp at тг, blsp at зайти, blacksprut, blacksprut ссылка, blacksprut зеркало, blacksprut сайт, blacksprut работает, blacksprut официальный, blacksprut маркетплейс, blacksprut актуальные, blacksprut darknet, blacksprut даркнет, blacksprut вход, блекспрут сайт, блекспрут официальный, блекспрут официальный сайт, ссылки на блекспрут, блекспрут вход[/color][/size]
Michaelcem
October 06, 2026, at 8:10 pmstarburst free spins play jackpot games 100 free spins
zodiac casino no deposit bonus free slot machines to play for fun Bonus brez vplacila za nove slovenske igralce hotel & casino resort admiral kozina slovenija
starburst free spins free spin to cashout
Keithbar
October 06, 2026, at 8:19 pmhttps://intercom.help/bestpromo/en-in/collections/19758050-regional-offer-library
NormanSow
October 06, 2026, at 8:35 pmzodiac casino bonus codes casino del rio no deposit bonus Igralniske Igre Za Denar casino online book of ra
StephenTit
October 06, 2026, at 8:36 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/osparivanie-brachnogo-dogovora/]оспаривание брачного контракта[/url] – это возможно, если условия договора нарушают права одного из супругов, был подписан под давлением или ставит сторону в крайне неблагоприятное положение. Юрист оценит перспективы дела, проверит договор, подготовит доказательства и поможет добиться признания спорных условий недействительными через суд.
NormanSow
October 06, 2026, at 8:56 pmlive casino roulette slot vockice online Kaj je bonus brez vplacila? bresplaДЌne casino igre
WayneFoola
October 06, 2026, at 9:15 pmbesplatne slot igre book of ra online casino lucky lady Igre na avtomatih 2026 ruby slots casino free spins
Lukeplose
October 06, 2026, at 9:17 pmRefreshing to find writing that does not try to manipulate the reader into clicking onto the next page through cliffhangers and forced engagement, and a stop at mythmarket continued in the same respectful way, this is what reader first design actually looks like in practice rather than just in marketing copy that sounds nice.
Warrenfer
October 06, 2026, at 9:36 pmThank you for the genuine effort here, it shows in every paragraph and not just the headline, and after my visit to quartzorchardvault I was sure this site cares about getting things right rather than chasing clicks, which is the main reason I will come back later this week to read more.
GradyKag
October 06, 2026, at 10:07 pmWorth recognising the absence of the usual blog tropes here, and a look at violettrailartisanmarket continued that fresh quality, sites that avoid the standard moves of the medium read as more original even when the content is on familiar topics and this one has clearly chosen its own path through the conventional terrain skilfully.
Charlesblamy
October 06, 2026, at 10:12 pmcasino gold club ajdovЕЎДЌina kazino igre kleopatra
play free casino games online casino brezplaДЌne igre Slovenske spletne igralnice oshi casino login
latest casino bonus jackpot wheel casino no deposit bonus codes
Charlesblamy
October 06, 2026, at 10:25 pmbesplatne slot masine casino igri online besplatno
book of ra deluxe ratio perla casino slovenia email Bonus brez vplacila 2026 gamingclub 30 free spins
ojo online casino live casino zonder cruks
Charlesblamy
October 06, 2026, at 11:17 pmcasino classic 50 free spins free welcome bonus no deposit 2026
slot igre demo new casino no deposit bonus 2026 Kje najti slovenske spletne igralnice? video poker igre
casino europe online casino online bonus
WayneFoola
October 06, 2026, at 11:29 pmWhich online casinos offer instant payout hit online casino Book of Ra igra 2026 poker igre free
WayneFoola
October 06, 2026, at 11:51 pmfree casino games for fun whitebet casino no deposit bonus Najboljsi casino bonusi v Sloveniji spletna igralnica z hitrim izplaДЌilom slovenija
WayneFoola
October 07, 2026, at 12:09 ammidaur free spins kateri spletni casino so ok Bonusi Spletnih Igralnic bet365 app ios download
Charlesblamy
October 07, 2026, at 1:18 amcasino free bonus besplatne casino igre za mobitel
casino 5 euro no deposit fun casino online Najboljsi casino bonusi v Sloveniji play poker onine free
Do any gaming apps actually pay real money portoroЕѕ casino online
Charlesblamy
October 07, 2026, at 1:31 ambitcoin casino slovenija free spin to cash out
live lounge casino korona casino kranjska gora Spletno igranje za pravi denar casino online slot machine
book of ra free games full tilt poker free download
StephenTit
October 07, 2026, at 1:50 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/osparivanie-brachnogo-dogovora/]юридическая помощь по оспариванию брачного контракта[/url] – это возможно, если условия договора нарушают права одного из супругов, был подписан под давлением или ставит сторону в крайне неблагоприятное положение. Юрист оценит перспективы дела, проверит договор, подготовит доказательства и поможет добиться признания спорных условий недействительными через суд.
nomiumkem
October 07, 2026, at 1:51 amразработка блокчейн систем
ochered-u-ekrana.site
создание платформы блокчейна
Charlesblamy
October 07, 2026, at 2:22 amhotel casino lipica slovenia slovenia casino online
best exclusive no deposit bonuses jackpot na ptuju Spletna igralnica s placilom prek Paysafecard vegas casino online
casino live diler slovenia casino no deposit bonus codes
WayneFoola
October 07, 2026, at 2:23 amno deposit bonus 2026 februar poker casino live Bonus brez potrebnega depozita zodiac casino 1
WayneFoola
October 07, 2026, at 2:44 amfree casino roulette games raging bull casino no deposit bonus codes 2026 Igralnica Hell Spin casino bonus 1000
WayneFoola
October 07, 2026, at 3:03 amfree casino games slots no download casino bonus codes 2026 no deposit Priporocena slovenska spletna igralnica kako igramo stave na bet 365
Charlesblamy
October 07, 2026, at 4:24 amplay free casino games online free 250r casino online
prenocisce casino bled hotel & casino resort admiral Lestvica najboljsih bonusov spletne igre casino
zodiac casino vip points online casino software
Charlesblamy
October 07, 2026, at 4:36 amegt free slot machine games casino slovenia poker
free video poker games book of ra igra Igralnice s Paysafecard, pregled 4 days 5 free spin casino
online casino affiliate earnings live casino slovenija
WayneFoola
October 07, 2026, at 5:16 amjackpot wheel casino no deposit bonus codes book of ra 2 Bonusi Spletnih Igralnic olybet promo kods 2026
Raynoili
October 07, 2026, at 5:20 amPicked up two new ideas that I expect will come up in conversations this week, and a look at foreststoneemporium added another, content that arms me with talking points rather than just filling time is the kind that provides ongoing value beyond the moment of reading and this site is generating that kind of ongoing value.
Charlesblamy
October 07, 2026, at 5:28 am247 free poker best online casino 2026
zastonj casino igre 20 euro no deposit casino bonus Domaca spletna igralnica fanduel live casino
pragmatic play live casino brezplaДЌne igre casino
WayneFoola
October 07, 2026, at 5:37 amfree blackjack online multiplayer bet 365 singup bonus Spletno igranje, kjer lahko zasluzite the best online casino for slovenian players
WayneFoola
October 07, 2026, at 5:56 amcasino admiral izola slots garden free chip Bonusi, ki jih ponujajo slovenske igralnice casino igre za denar
Bogdotis
October 07, 2026, at 7:25 amReading through niche publications I discovered a fascinating learning resource
where you can find actionable advice and deep analysis
Click here to explore : https://www.designspiration.com/lumoslinkbuilding/saves/
Charlesblamy
October 07, 2026, at 7:31 amplay online casino games for fun free games casino no deposit
kitek casino bled brezplacne casino igre book of ra Bonus Dobrodoslice captain jack casino free 500
juicy stakes casino no deposit bonus 100 legal online casino slovenia
Charlesblamy
October 07, 2026, at 7:43 ammonte carlo online casino free 20 spins mr green 20 free spins
blackjack demo first person korona casino kranjska gora Spletno igranje za pravi denar live casino ljubkjana
igre casino avtomati casino admiral kozina
Donaldler
October 07, 2026, at 7:53 amЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/izmenenie-brachnogo-dogovora/]юрист по изменению брачного договора[/url] – юрист поможет проверить условия действующего соглашения, подготовить изменения и оформить их в законном порядке. Юридическая помощь особенно важна при изменении состава имущества, доходов, кредитных обязательств или договоренностей между супругами, что позволит скорректировать имущественные права и обязанности супругов с учетом новых обстоятельств.
WayneFoola
October 07, 2026, at 8:09 amjumba bet free no deposit bonus codes hit casino kranjska gora Casino igre za denar besplatne casino igre book of ra
nomiumkem
October 07, 2026, at 8:19 amблокчейн разработка под ключ
ochered-u-ekrana.site
блокчейн разработка услуги
WayneFoola
October 07, 2026, at 8:30 ambetroadhousereels casino no deposit bonus blackjack card counting Igre za denar casino korona kranjska gora program
Charlesblamy
October 07, 2026, at 8:35 amwilliam hill online casino pending bonus dollars bet365
Which bet gives you a bonus without deposit besplatne casino igre where is the gold Kako prevzeti bonus dobrodoslice? box24 casino 25 free spins
register casino bonus poker online live free
WayneFoola
October 07, 2026, at 8:48 amcasino bonus brez depozita evropa za pravi denar free online poker games Igralniske igre za denar royal vegas casino 1000 free spins
ColinLip
October 07, 2026, at 10:16 amNow considering the post as evidence that careful blog writing is still possible, and a look at brighttrailartisanbazaar extended that evidence, the broader question of whether the modern web can sustain quality writing has obvious empirical answers in sites like this one and seeing them is reassuring even when they remain a minority overall today.
Charlesblamy
October 07, 2026, at 10:36 amcasinos online slovenia twist casino free games
casino game free spins no deposit the best online casino aceptslovenia players Kje igrati spletne igre za denar? casino kozina admiral
the best online casinos accept slovenian players najboljЕЎa spletna igralnica za hitre dvige
Charlesblamy
October 07, 2026, at 10:49 amclub player casino no deposit bonus codes gaming club casino no deposit bonus codes
casino igre gratis Can you win real money on free casino games Spletno igranje, kjer lahko zasluzite casino online italia
new casino no deposit bonus 2026 casino no deposit bonus codes
WayneFoola
October 07, 2026, at 11:01 amtitan online casino grand eagle no deposit bonus codes 2026 Igralni avtomati za zabavo in igranje na sreco kranjska gora casino
JulioGep
October 07, 2026, at 11:16 amSpeaking from the perspective of having read widely on the topic this site offers something distinct, and a look at baytrailartisanmart reinforced that distinctness, the rare site that contributes something genuinely original to a saturated topic is the rare site worth following carefully and this one has demonstrated that original contribution capability today.
WayneFoola
October 07, 2026, at 11:22 am1€ casino bonus casino bled bizi Kateri izbrati za igranje za pravi denar? hotel casino kozina slovenia
Ronniedus
October 07, 2026, at 11:29 amMy time on this site has now extended past what I had budgeted, and a stop at canyonmeadowoutlet keeps extending it further, content that overstays its budget in my schedule is content that has earned the extra time and this site has been earning extra time across multiple visits to the point where my schedule needs adjustment.
WilburElaxy
October 07, 2026, at 11:36 amAppreciate the work that went into laying this out so clearly, every section earns its place without filler, and a look at wildorchardvault confirmed the same care, definitely the kind of place that deserves a return visit when the topic comes up again later in the future or for any related question.
Charlesblamy
October 07, 2026, at 11:40 ambaccarat free spins the best casino online accept slovenian players
best casino games casino no deposit bonus code Pregled igralnic za pravi denar book of ra slot
william hill free spins most profitable online casino
WayneFoola
October 07, 2026, at 11:40 amhitstars online casino slo casino guru free slots Zacnite igrati za pravi denar play palace casino no deposit bonus codes 2026
Charlesblamy
October 07, 2026, at 1:41 pmaustria online casino What is the best online casino
play casino online best casinos online paypal Spletne igralniske igre 2026 zodiac casino sign in
casino admiral kongou bizi verde casino no deposit bonus
RonnieRag
October 07, 2026, at 1:49 pmReading this between two meetings turned out to be the highlight of the morning, and a stop at packandpost continued that highlight quality, content that outshines the structured parts of a working day is doing something well beyond ordinary and this site has produced multiple such highlights for me already this week alone.
WayneFoola
October 07, 2026, at 1:53 pmblackjack demo pragmatic Which online casino has the best no deposit bonus Igralni Avtomati V Igralnici book of ra 6 deluxe demo
Charlesblamy
October 07, 2026, at 1:54 pmbet at home blocked in slovenia compare online casinos
free bet no deposit bonus zodiac casino live chat Katera je slovenska spletna igralnica? captain cook casino rewards
star casino online free slot games no download
XrumerCaugs
October 07, 2026, at 2:05 pmSiamo orgogliosi di presentare un database aggiornato per Xrumer. È stato svolto un ampio lavoro analitico proprietario e questa versione è stata costruita interamente da zero.
Dettagli e ordini tramite il link: https://t.me/gsaserxrumerbase/9
• Data di rilascio: 3 ottobre 2026
• Numero totale di link: 4.266.514
• Segmento (Creazione profili su forum): 247.504
• Segmento (Pubblicazione generale): 2.511.572
• Segmento (Moduli di contatto): 1.507.438
In questa versione, abbiamo dato priorità alla massima efficienza (tempo di elaborazione vs. risultati) includendo esclusivamente segmenti “Success” (di successo). Non importa quanto altri venditori di database cerchino di girarci intorno e gonfiare i loro numeri, non ha assolutamente senso elaborare segmenti “HalfSuccess” o “Others”. Stiamo risparmiando il tuo traffico e il tuo tempo. Questo è ONESTO.
Offriamo inoltre proxy IPv6 per Xevil ReCaptcha 6,7 con configurazione chiavi in mano sul tuo VPS.
Buona fortuna, amici!
Database di link per Xrumer, database Xrumer, database Xrumer 23, proxy per reCAPTCHA, proxy IPv6 per reCAPTCHA
WayneFoola
October 07, 2026, at 2:14 pmkako pobediti blackjack how do live casino dealers see you Pregled igralniskih iger best online casino bonus no deposit
StanleyPharf
October 07, 2026, at 2:29 pmThanks for sharing this with the open internet rather than locking it behind a paywall like so many sites do now, and a stop at quickharborvault kept the same vibe going, generous helpful and clearly written by someone who actually wants people to learn from it rather than just charge them.
WayneFoola
October 07, 2026, at 2:32 pmjoker casino bonus casino admiral lasy Najboljsi spletni casino Slovenija 2026 casino bonus
Charlesblamy
October 07, 2026, at 2:46 pmfree casino slot games download casino kranjska gora larix
casino bonus codes 2026 no deposit free spin casino cash out mastercard Spletna ruleta za zacetnike in izkusene igralce casino 1 euro deposit
live casino number free spins weekly cash out
LewisMalay
October 07, 2026, at 2:55 pmReading this triggered a small but real correction in something I had assumed, and a stop at crowntrailartisanoutlet extended that corrective effect, content that updates my beliefs through evidence rather than rhetoric is content with intellectual integrity and this site has earned that label consistently across the pieces I have read so far today.
nomiumkem
October 07, 2026, at 2:56 pmразработка кошелька
ochered-u-ekrana.site
мобильная разработка на flutter
CharlesBioks
October 07, 2026, at 4:09 pmЕсли необходимо усилить доверие к каналу визуально, можно увеличить подписчиков и добавить активность последним постам. Просмотры и реакции помогают сделать ленту более насыщенной, а общее количество участников поддерживает впечатление развитого проекта – купить подписчиков вк
WayneFoola
October 07, 2026, at 4:44 pmcomeon casino no deposit bonus codes 2026 high roller casino online Igralniske igre free spins no deposit codes
Charlesblamy
October 07, 2026, at 4:47 pmadmiral kongo casino online casinos with neon life
brezplaДЌni vrtljaji brez depozita casino portoroЕѕ online Book of Ra igra 2026 joker poker free online
no deposit bonus casino europe real money casino book of ra real money
Charlesblamy
October 07, 2026, at 5:00 pmonline casino marketing strategy korona casino slovenia
brezplaДЌne casino spletne igre bet365 bonus code no deposit bingo Igralnica s placilom Paysafecard portoroЕѕ casino online
free royal poker casino bonus brez depozita 10 €
WayneFoola
October 07, 2026, at 5:05 pmbesplatne slot masine zodiac casino download Igralnica Hell Spin Slovenija casino bled forum
WayneFoola
October 07, 2026, at 5:23 pmkazino igre 123 bet365 mobile poker app WinShark Slovenija 2026 povezava za bet bet athome
LATASHIAReiny
October 07, 2026, at 5:49 pmhttps://intercom.help/bestpromo/en-hk/collections/19729520-welcome-deals
Charlesblamy
October 07, 2026, at 5:51 pmthe best online casinos for slovenia players zar casinos no deposit bonus codes
admiral hotel casino kozina company casino no deposit bonus Spletna igralnica, kjer lahko igrate za pravi denar What casino has free signup bonus no deposit required
the best online casino online accept slovenia players cool cat no deposit bonus codes
HATTIEKEYMN
October 07, 2026, at 6:16 pmhttps://intercom.help/bestpromo/en-gb/collections/19772876-global-insights-country-guides
swingingislandpdfTaini
October 07, 2026, at 6:57 pmhttps://swingingislandpdf.site/
theroundhousepdfTaini
October 07, 2026, at 7:05 pmhttps://theroundhousepdf.site/
WayneFoola
October 07, 2026, at 7:35 pmignition casino no deposit bonus no deposit bonus 5 euro Igralne masine v igralnici free casino video slot games online
JulioWah
October 07, 2026, at 7:38 pmЕсли интересует: [url=https://www.pravovik24.ru/konsultatsii/rastorzhenie-brachnogo-dogovora/]стоимость расторжения брачного договора[/url] – то расторжение возможно по взаимному соглашению супругов или через суд при наличии законных оснований. Юрист поможет оценить условия договора, определить порядок действий, подготовить необходимые документы и защитить ваши интересы. Юридическая помощь особенно важна, если одна из сторон не согласна на расторжение или условия договора существенно нарушают ваши права.
Charlesblamy
October 07, 2026, at 7:52 pmparty casino free spins non deposit bonus casino online
What is the WILD250 bonus code live dealer casinos Spletne igre fruits for real casino no deposit bonus
live casino games free spins no deposit codes
WayneFoola
October 07, 2026, at 7:56 pmcasino bled hotel brezplaДЌne kazino igre Hell Spin coin beach free spins
Charlesblamy
October 07, 2026, at 8:04 pmcasino blu no deposit bonus codes casino igre online lucky ladys charm deluxe
free slot casino games with bonus 22bet live casino Casino igralni avtomati kako delujejo spletni avtomati za pravi denar
sb casino no deposit bonus codes kazino igrice book of ra
WayneFoola
October 07, 2026, at 8:14 pmfree spin casino no deposit bonus codes 2026 joker casino bonus Bonus brez depozita 2026 mobile casino free spins
Charlesblamy
October 07, 2026, at 8:56 pmblack lotus casino no deposit bonus brezplaДЌne casino free igre
live bet88 casino bet365 sign up bonus code Bonusi igralnic fone casino no deposit bonus
book of ra demo bled nagradna igra casino
JefferyRoups
October 07, 2026, at 10:28 pmbet at home slovenia closed casino 10 no deposit bonus Ruleta v spletnem casinu free bet no deposit bonus
CharlesBioks
October 07, 2026, at 10:33 pmУвеличение активности помогает новым публикациям выглядеть заметнее с момента размещения. Накрутка просмотров, лайков и реакций позволяет быстро поддержать контент и сформировать привлекательные показатели: накрутка подписчиков ютуб бесплатно
JefferyRoups
October 07, 2026, at 10:49 pmcasino luck no deposit bonus code bet at home 365 Kateri so najboljsi bonusi v Sloveniji? blackjack pragmatic play
RogerWic
October 07, 2026, at 10:57 pmbrezplaДЌni bonus casino brez depozita evropa get no deposit bonus casino
casino share no deposit bonus bet365 25 bonus https://zooactive.si sign up casino free spins 2026 slovenija
kako igrati igre v kazinu live casino top 10
JefferyRoups
October 07, 2026, at 11:07 pmWhat is the best online casino app b-bets casino no deposit bonus Igralni avtomat Book of Ra igralnica casino bled
RogerWic
October 07, 2026, at 11:09 pmcasino portorose slovenia 1 euro deposit casino
blackjack do you split 10s euro no deposit bonus casino https://casinobonusbrezdepozita.si grande vegas casino no deposit bonus codes
hotel casino safir hotel seЕѕana slovenia zodiac casino sign up
kalibrovka_byKa
October 07, 2026, at 11:14 pmДля обеспечения точности измерений важно своевременно провести [url=https://kalibrovka-kalibrov.ru/]калибровка цилиндрических калибров[/url].
Это помогает выявить возможные отклонения и принять необходимые меры.
RogerWic
October 08, 2026, at 12:01 amsir jackpot casino no deposit bonus code thebigfreechiplist jackpot naslednje zrebanje
casino faraon celje slovenia 22bet live casino https://houndsontheprairie.com bgo free spins
napoli casino no deposit bonus codes book of ra 6 deluxe free
JefferyRoups
October 08, 2026, at 1:21 amCan you win real money with free play royal vegas casino 1000 free spins Bonusi igralnic lucky casino online
nomiumkem
October 08, 2026, at 1:27 amвнедрение геймификации
ochered-u-ekrana.site
разработка блокчейн платформы
JefferyRoups
October 08, 2026, at 1:42 amcasino online slot machine free game slot machine WinShark igralnica Slovenija best online casinos 2026
MichaelGlush
October 08, 2026, at 1:47 am[url=https://ar-cocos-capital.com/]CAPITAL COCOS[/url]
A Capital Cocos apresenta de forma organizada as informações sobre seus serviços e soluções, facilitando a consulta para quem deseja conhecer melhor a plataforma.
Williamnuava
October 08, 2026, at 1:50 amПанда казино зеркало
?
Панда Казино Telegram — здесь можно найти ссылку на сайт, актуальное зеркало и последние обновления.
JefferyRoups
October 08, 2026, at 2:01 am1win live casino roulette live casino Vrhunska igralnica v Sloveniji casino kongo slovenia
RogerWic
October 08, 2026, at 2:01 amcasino koper slovenia slots of vegas no deposit bonus codes
casino bonus hunting dragon tiger live casino https://pulmo-panjan.si casino bonus buy
casino bonus 1000 no deposit bonus codes
RogerWic
October 08, 2026, at 2:13 amfree spins rio slot game free casino igt cleopatra
juicy stakes no deposit bonus counting cards blackjack https://marlenesanscartier.com online casino hit
minimum deposit 5 euro casino vulkanvegas free spin no deposit
Williamnuava
October 08, 2026, at 2:39 amПанда казино играть
?
Рабочее зеркало Panda Casino на сегодня можно найти в актуальных публикациях Telegram-канала.
RogerWic
October 08, 2026, at 3:05 amslovenia online betting wild jack casino no deposit bonus codes 2026
vip programs on online casinos 25 free bonus no deposit https://franciscogpr.com mobile slots no deposit bonus
william hill free spins best pc casino sites online
Williamnuava
October 08, 2026, at 3:27 amПанда казино
?
Панда Казино зеркало на сегодня — проверяйте свежие публикации Telegram-канала для актуального адреса.
Dravendrils
October 08, 2026, at 3:58 amReading this slowly because the writing rewards a slower pace, and a stop at meadowridgecollectivemart did the same, the pace at which I read content is something I now use as a quality signal and writing that earns a slower pace earns my attention as a reader looking for substance these days.
JefferyRoups
October 08, 2026, at 4:15 ambook ra online najboljЕЎi casino bonus slovenija Ruleta v spletnem casinu casino bled poker
Williamnuava
October 08, 2026, at 4:15 amПанда казино сайт
?
Зеркало Панда Казино на сегодня можно найти среди актуальных публикаций нашего Telegram-канала.
JefferyRoups
October 08, 2026, at 4:36 amDoes Casinobit IO have a no deposit bonus gostilna casino kranjska gora Vodnik po spletni ruleti blackjack not 21
CharlesBioks
October 08, 2026, at 4:41 amДобавьте больше активности к важным публикациям с помощью накрутки лайков, просмотров и реакций. Это удобный способ быстро усилить отдельный пост, ролик или историю и сделать показатели контента более заметными для посетителей – накрутить твич
JefferyRoups
October 08, 2026, at 4:54 amspletni casino za pravi denar slovenija coin kingdom free spins Igrajte avtomate brezplacno free casino slots
XrumerCaugs
October 08, 2026, at 4:58 amРады представить обновленную базу для Хрумера, было много авторской аналитической работы, подготовили релиз с 0
Подробности и заказ по ссылке https://t.me/gsaserxrumerbase/4
Дата релиза: 03.10.2026
Общее количество ссылок: 4 266 514 шт.
Сегмент (прогон по профилям-форумы): 247 504 шт.
Сегмент (прогон постинг): 2 511 572 шт.
Сегмент (контактные формы): 1 507 438 шт.
В текущем релизе для большей эффективности (время прогона – результат), только Success сегменты, как бы не юлили продавцы баз нагоняя цифры, нет смысла прогонять HalfSuccess и Others, побережем и трафик и время, это будет ЧЕСТНО
Так же предлагаем прокси IPv6 для Ре Капчи Xevil 6,7 с настройкой на Вашем собственном VPS под ключ
Удачи друзья!
база ссылок Хрумер Xrumer, база для Хрумера, базы Xrumer 23, прокси для Ре Капчи, прокси для recaptcha, прокси ipv6 recaptcha
Williamnuava
October 08, 2026, at 5:07 amPanda Casino
?
Играть в Panda Casino можно через актуальную ссылку на сайт, которую публикуем в Telegram-канале.
RogerWic
October 08, 2026, at 5:08 ambwin casino live chat igre online casino
casino kranjska gora kleiderordnung 888 poker 5 free play casino bonus https://queen-b.si hotel casino admiral
casino rewards play for free fanduel live casino
Ronnietig
October 08, 2026, at 5:17 amReading this in a quiet hour and finding it suited the quiet, and a stop at auroracovevault extended the quiet reading mood, content that matches its own optimal reading conditions rather than fighting them is content that has been thoughtfully calibrated and this site reads as having a particular reading mood in mind throughout.
RogerWic
October 08, 2026, at 5:21 amcasino admiral kozina 2026 jackiejackpot no deposit bonus
free spin no deposit casino cashout mastercard europa bet on red https://punitpandey.com golden euro casino no deposit bonus code
roy richie casino no deposit bonus best europe casino bonuses 2026 play in slovenia
RogerWic
October 08, 2026, at 6:15 amigra casino online paypal online casinos
best online casino slovenija funky time live casino https://yadaktimche.com sky bet slovenia
igre casino aparati bet365 poker bonus
Williamnuava
October 08, 2026, at 6:24 amВойти в Панда Казино
?
Panda Casino официальный канал — сайт, рабочее зеркало и актуальные сведения о проекте в одном месте.
KalebAdord
October 08, 2026, at 6:25 amA relief to read something where I did not have to fact check every claim mentally, and a look at pagerankparlor continued that reliable feeling, sites where I can lower my guard and trust the content are rare and this one is earning that trust paragraph by paragraph through consistent careful work behind the scenes.
JefferyRoups
October 08, 2026, at 7:08 amexotic online casinos casino dice game Zahtevajte bonus brez depozita play amo casino online
ReggieArref
October 08, 2026, at 7:24 amUseful reading material, the kind I can hand off to someone newer to the topic without worrying about confusing them, and a quick look at pebblepineoutlet confirmed the same beginner friendly tone runs throughout the site which is great for sharing with people just starting their learning journey on this particular topic.
JefferyRoups
October 08, 2026, at 7:29 amcasino bonus brez depozita evropa za pravi denar casino bonus brez depozita slovenija Hell Spin igralnica Slovenija hell spin casino
JefferyRoups
October 08, 2026, at 7:47 amtypes of casino games casino fortuna slovenia Igre za denar 2026 zodiac casino forum slovenija
JaceCragS
October 08, 2026, at 7:48 amStarted forming counter examples to test the claims and the post handled most of them implicitly, and a look at cottontrailartisanbazaar continued that anticipatory style, writers who think two steps ahead of the critical reader save themselves from a lot of follow up work and this writer has clearly internalised that habit consistently.
RogerWic
October 08, 2026, at 8:21 amkako otvoriti online kazino spletna igralnica slovenija
best blackjack app bonus black jack https://lili-app.com dreams casino no deposit bonus codes
bet365 poker bonus code casino portoroЕѕ vrhunske igre
ZairinaEremy
October 08, 2026, at 8:21 amВ нашем YouTube-канале BANK-NEVA https://www.youtube.com/watch?v=YIPaxyhOA50 мы разбираем темы займов, кредитов и финансов понятным языком. Объясняем, что такое ПСК, процентная ставка и переплата, на какие пункты договора стоит смотреть до подачи заявки и получения займа. Сравниваем новые микрофинансовые организации с компаниями, которые давно работают на рынке, как работают займы под 0% для новых клиентов, по каким причинам МФО отказывают и что влияет на решение по заявке. Кроме того, объясняем, как не столкнуться с ненужными подписками, страховками и дополнительными платными услугами.
Основная цель канала – повысить финансовую грамотность и научить заемщиков понимать реальные условия займов. В видео BANK-NEVA мы показываем, как грамотно подать заявку на займ, какие данные указывать в анкете, почему массовая отправка заявок не всегда помогает получить одобрение и как выбирать между предложениями разных МФО. Сложные финансовые понятия мы объясняем на простых и понятных примерах, чтобы вы могли самостоятельно оценить стоимость займа и принять взвешенное решение. Финансовая грамотность помогает заранее оценить последствия займа и снизить риск лишних трат и долговых проблем.
dostavka_yrOa
October 08, 2026, at 8:26 am[url=http://alkogol-dostavka-moskva-xpr.ru/]заказать алкоголь[/url]
Доставка алкоголя становится все более популярной среди покупателей .
Многие компании предлагают быстрый и удобный сервис по доставке напитков прямо к вашему порогу .
Особенности доставки включают широкий ассортимент и возможность выбора наиболее подходящего варианта .
Ключевым фактором является рейтинг и надежность сервиса.
Оформление заказа обычно занимает всего несколько минут и требует минимальных усилий .
Удобно, что есть возможность получить профессиональную помощь при выборе.
Раздел 2: Ассортимент и цены.
В большинстве случаев доставка включена в цену или предоставляется за отдельную плату.
Многие сервисы проводят акции и предоставляют скидки для постоянных клиентов .
Доставка осуществляется в оговоренные сроки, часто в течение нескольких часов после заказа .
В случае срочной необходимости много сервисов обеспечивают экспресс-доставку .
Доставка осуществляется аккуратно, с соблюдением всех правил хранения и транспортировки .
В некоторых регионах предоставление алкоголя лицам без подтвержденного возраста запрещено.
Курьеры проходят обучение и не допускают нарушений при доставке .
Эта услуга становится всё более востребованной благодаря удобству и скорости .
RogerWic
October 08, 2026, at 8:34 amkranjska gora casino casino kozina slovenia
vavada casino bonus code book of ra deluxe free demo https://fireislandsh.com casino online free spins
casino slot igre 24bettle casino no deposit bonus
theroundhousepdfTaini
October 08, 2026, at 8:56 amhttps://theroundhousepdf.site/
Walterhiz
October 08, 2026, at 9:03 amНужен юрист? [url=https://www.pravovik24.ru/r/mo/chekhov/]задать вопрос адвокату без номера телефона в Чехове[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
ScottElope
October 08, 2026, at 9:28 ambook of ra free spins hopa casino online
zodiac casino download software ruby fortune casino free spins https://houndsontheprairie.com party casino bonus code 2026 free spin
casino bled slovenia hotel casino admiral kozina
swingingislandpdfTaini
October 08, 2026, at 9:40 amhttps://swingingislandpdf.site/
LorenBot
October 08, 2026, at 10:01 ambook of ra online casino casino igre free prašići Lestvica najboljsih bonusov admiral casino mladá boleslav
LorenBot
October 08, 2026, at 10:22 amgolden euro casino no deposit bonus codes hotel casino resort admiral Bonus brez depozita 2026 casino bonus brez depozita 20 €
LorenBot
October 08, 2026, at 10:39 amfree coyote moon slot game casino kranjska gora poker Igre na spletu, kjer lahko zasluzite casino metropol portoroЕѕ slovenija
ntaletiecw
October 08, 2026, at 11:01 amtorsemide to furosemide conversion 80 mg lasix [url=https://medvipp.com/lasix/]buy lasix 80mg[/url] lasix water tablets over the counter furosemide
CharlesBioks
October 08, 2026, at 11:03 amЕсли в мессенджере проводится опрос, можно добавить ему больше голосов и просмотров. Это помогает сделать публикацию заметнее, привлечь внимание к вариантам ответа и показать более активное участие аудитории в обсуждаемой теме – покупка подписчиков
XrumerCaugs
October 08, 2026, at 11:22 amWe are proud to present an updated database for Xrumer. Extensive proprietary analytical work has been done, and this release was built entirely from scratch.
Details and ordering via the link: https://t.me/gsaserxrumerbase/5
• Release date: October 3, 2026
• Total number of links: 4,266,514
• Segment (Forum profile spinning): 247,504
• Segment (General posting): 2,511,572
• Segment (Contact forms): 1,507,438
In this release, we prioritized maximum efficiency (spinning time vs. results) by including only “Success” segments. No matter how other database sellers try to wiggle around and inflate their numbers, there is absolutely no point in spinning “HalfSuccess” or “Others”. We are saving your traffic and time. This is HONEST.
We also offer IPv6 proxies for Xevil ReCaptcha 6,7 with a turnkey setup on your own VPS.
Good luck, friends!
Xrumer link database, Xrumer database, Xrumer 23 databases, reCAPTCHA proxies, IPv6 proxies for reCAPTCHA
ScottElope
October 08, 2026, at 11:31 amigre na sreДЌo casino stavvnice bronze casino no deposit bonus
slot game free igt live casino bonanza https://jekloruse.si book of ra no deposit
casino bonus new player free coyote moon slot game
ScottElope
October 08, 2026, at 11:44 amfone casino no deposit bonus Which gambling sites give free money
casino live bonus hotel casino safir sezana slovenia https://fcmontceau-bourgogne.com single deck blackjack
kateri online casino priporoДЌate ruleta casino online
MichaelGlush
October 08, 2026, at 11:52 am[url=https://us-cocos-capital.net/]CAPITAL COCOS[/url]
A área de Cocos Capital Login permite localizar o acesso à plataforma de forma simples, sendo recomendável sempre utilizar os canais oficiais para entrar na conta.
ScottElope
October 08, 2026, at 12:38 pmcaptain cooks casino old havana casino no deposit bonus 2026 thebigchip
casino slot free wizbet casino no deposit bonus codes 2026 https://pulmo-panjan.si online casino x
no deposit bonus casino not uk 32 online casino
Roberteduts
October 08, 2026, at 12:52 pmcasino royale game live casino igre za pravi denar Igranje iger na sreco za pravi denar na spletu casino cruise no deposit bonus codes
Roberteduts
October 08, 2026, at 1:14 pmcasino admiral kozina coin beach free spins Slovenska igralnica spletne igre casino
nomiumkem
October 08, 2026, at 1:26 pmинтерактивный выставочный стенд
ochered-u-ekrana.site
блокчейн для бизнеса
Roberteduts
October 08, 2026, at 1:31 pmonline casino marketing strategy bwin casino games Igre na avtomatih na spletu bonus casino online
ScottElope
October 08, 2026, at 2:44 pmblackjack vs baccarat springbok online casino
majestic slots no deposit bonus codes casino 10 euro deposit https://yadaktimche.com play blackjack online
free offline casino pc games new casino games
ScottElope
October 08, 2026, at 2:57 pmkazino igre sizzling hot bet365 loyalty bonus
zodiac casino forum slovenija free casino slot games to play https://feastdvd.com brezplaДЌne igre casino konji
live roulette casino poker igre free
Walterhiz
October 08, 2026, at 3:03 pmНужен юрист? [url=https://www.pravovik24.ru/r/mo/chekhov/]консультация юриста адвоката в Чехове[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Patricktielm
October 08, 2026, at 3:08 pmNow placing this in the same category as a few other sites I have come to trust, and a look at maplegroveemporium continued the placement decision, the small category of fully trusted sites is one I extend rarely and only after multiple positive reading sessions and this site has earned the category placement methodically over time.
Roberteduts
October 08, 2026, at 3:45 pmcasino admiral online igre na sreco za pravi denar Igre iz spletne igralnice casino bled direktor
ScottElope
October 08, 2026, at 3:50 pmcasino free online video games besplatne casino igre za mobitel
hit casino kranjska gora restaurant bet365 mobile casino https://slovenskispletnicasino.com trusted online casino
book of ra garminator star casino online
Roberteduts
October 08, 2026, at 4:06 pmcasino poker online game online casino ads Slovenski casino online book of ra game download for pc
Roberteduts
October 08, 2026, at 4:24 pmcasino 365 live book of ra jackpot Poiscite najboljse bonuse jackpot lucky block
Williamnuava
October 08, 2026, at 5:11 pmла казино
CharlesBioks
October 08, 2026, at 5:28 pmБольше лайков под постом помогает публикации выглядеть заметнее, а просмотры усиливают динамику видео. Накрутка позволяет быстро добавить нужные показатели и поддержать контент в период запуска, рекламы или продвижения: накрутить лайки в тик ток
Patrickgot
October 08, 2026, at 5:54 pmroyal vegas casino 1000 free spins bet365 bonus code 2026
free bet blackjack free poker money Igre v online casinu prenocisce casino bled
besplatne casino igre za igranje casino bled park hotel
Williamnuava
October 08, 2026, at 6:06 pmля казино
Patrickgot
October 08, 2026, at 6:07 pmalf casino no deposit bonus live casino poker
zodiac casino sign in book of ra game Casino bonusi Slovenija casino igre besplatne slots
wintingo online casino review how to party casino bonus code no deposit
nessunotornaindietTaini
October 08, 2026, at 6:09 pmScoprire “Nessuno torna indietro” significa entrare in contatto con una delle voci più importanti del Novecento italiano. Alba de Céspedes racconta la formazione di otto ragazze con un realismo e una poesia che lasciano senza fiato. Il pensionato diventa teatro di vita vera, dove si consumano drammi e si accendono speranze. La facilità di reperire il libro in formato digitale, magari cercando il pdf, è un grande vantaggio per i lettori di oggi. Lasciati ispirare da queste storie di coraggio e determinazione, e scopri come la letteratura possa essere uno specchio in cui riflettersi e comprendersi meglio. https://nessunotornaindietropdf.site/ Nessuno Torna Indietro De Cespedes Oscar 1966
Roberteduts
October 08, 2026, at 6:37 pmblackjack do you split 9s casino slot free Slovenske Spletne Igralnice free roulette spin
JOLANDAKEYMN
October 08, 2026, at 6:40 pmhttps://0xbt.net/profile/codebonastoday1
KRISTELReiny
October 08, 2026, at 6:41 pmhttps://www.blogbangboom.com/computers-electronics/bonuscodenew-bonuscodenew
Roberteduts
October 08, 2026, at 6:57 pmblackjack casino online casino list blackjack online gratis Spletna igralnica cool cat no deposit bonus codes
Williamnuava
October 08, 2026, at 6:58 pmла казино
Patrickgot
October 08, 2026, at 7:01 pmbrezplaДЌne slovenia igre na avtomatih 6 deck blackjack
live casino free play online casino no deposit bonus not on gamstop Igralnica na spletu Slovenija fortuin casino no deposit bonus codes
casino demo games book of ra prenos igre
Roberteduts
October 08, 2026, at 7:15 pmtop 5 online casinos plus500 no deposit bonus Zabava v igralnici na spletu blackjack vs 21
Williamnuava
October 08, 2026, at 7:50 pmля казино
Williamnuava
October 08, 2026, at 8:46 pmля казино
theroundhousepdfTaini
October 08, 2026, at 8:56 pmhttps://theroundhousepdf.site/
NathanAvela
October 08, 2026, at 9:05 pmcasino bonus 50 free spins yebo casino no deposit bonus codes 2026
captain cooks casino play online casino blackjack real money Kako vplacati v spletno igralnico s Paysafecard casino fontana slovenia
slo online casino omni casino no deposit free spins 2026
NathanAvela
October 08, 2026, at 9:18 pmhow to play blackjack online kazino igre besplatne
10e no deposit bonus casino online casino ratings Igralni avtomati casino online korona casino kranjska gora
iw casino online casino book of ra game
swingingislandpdfTaini
October 08, 2026, at 9:18 pmhttps://swingingislandpdf.site/
Dennisveine
October 08, 2026, at 9:27 pmbet 365 slovenija uzivo 40 euro no deposit bonus Spletne igre, v katerih lahko igrate za denar casino games free online slot machines
vulkan casino online casino slovenia online no deposit codes
login jackpot city
Dennisveine
October 08, 2026, at 9:48 pmplay palace casino no deposit bonus codes 2026 10 euro no deposit bonus casino Spletna ruleta za zacetnike in izkusene igralce casino igre brezplaДЌne
poker igre free bingohall online casino
online casino europe
unavitanuovapdfTaini
October 08, 2026, at 9:56 pmPaolo e Andrea ci insegnano che non serve essere eroi per cambiare la propria vita, basta avere il coraggio di fare il primo passo. O di mettere in moto l’auto. Questo romanzo è un inno alla normalità che diventa straordinaria. Molti cercano una vita nuova pdf per la comodità di lettura che offre il digitale, permettendo di gustare il testo anche al buio o in movimento. La storia è fluida, coinvolgente e piena di verità, ideale per chi cerca un libro che sappia intrattenere ma anche far riflettere su cosa significhi davvero essere adulti e felici nel mondo contemporaneo. https://unavitanuovapdf.site/ Recensioni Libro Fabio Volo Una Vita Nuova
Dennisveine
October 08, 2026, at 10:06 pmbig fish games big fish casino free vegas casino games Ruleta first person blackjack
admiral casino kozina springbook casino no deposit bonus codes
no deposit bonus casino not uk
NathanAvela
October 08, 2026, at 10:11 pmonline casino blackjack real money casino live slot
casino online free book online casino for slovenia Kako vplacati v spletno igralnico s Paysafecard bwin live casino
book of ra video slot mashine online casino wiki
MichaelSuern
October 08, 2026, at 10:11 pm[url=https://script.google.com/macros/s/AKfycbzUFExadXXq-AaKdbBuOXO6WT5OS_qtTcq0ovfRgm2jeKjGek-qZbE-mRmfUb5_U8c8/exec]Nekopoi[/url]
Williamnuava
October 08, 2026, at 10:14 pmроуз руж революшн
MiguelStore
October 08, 2026, at 10:28 pmПомогаем быстро перейти от консультации к конкретному плану: выезд, стационар или наблюдение.
Дополнительная информация – [url=https://narkologicheskaya-klinika-voronezh20.ru/]анонимная наркологическая клиника[/url]
Cordellstisy
October 08, 2026, at 10:52 pmHonest reaction is that I want to send this to a friend who would benefit from it, and a look at woodcovevault added more material I will pass along too, the impulse to share is the strongest signal I have for content quality and this site is generating that impulse cleanly across multiple posts.
FranciscoAcumb
October 08, 2026, at 10:55 pmReally appreciate that the writer did not overstate the importance of the topic to make the post feel weightier, and a quick visit to nightroutine maintained the same modest framing, content that is honest about its own scope rather than inflating itself is the kind I trust and return to repeatedly over time.
Williamnuava
October 08, 2026, at 11:06 pmmod fashion
CharlesBioks
October 08, 2026, at 11:48 pmЕсли необходимо привлечь внимание к закрепленному сообщению, можно добавить ему просмотры и реакции. Это помогает выделить важную информацию, правила, предложение или объявление и сделать его более заметным среди остальных материалов, накрутка просмотров ютуб бесплатно
Williamnuava
October 08, 2026, at 11:57 pmhttps://t.me/s/rrrevolution_clothes
NathanAvela
October 09, 2026, at 12:14 ambesplatne slot masine za igranje igre paysafecard izplacilo takoj casino
old havana casino no deposit bonus 2026 thebigchip igra casino online Slovenska spletna igralnica book of ra za pravi dennar
mr green online casino casino brez depozita brez pogojev
Dennisveine
October 09, 2026, at 12:18 ambet365 mobile casino flamantis casino no deposit free spins Kje igrati igre na avtomatih? casino dice game
live casino tracker twist casino no deposit bonus
vegas casino online welcome bonus
MackSKell
October 09, 2026, at 12:19 amOne of the more honest takes on the topic I have seen lately, no spin and no oversell, and a stop at kettlegroveboutiquehouse kept that going, the kind of voice the open web could use a lot more of rather than the endless echo chamber of recycled opinions floating around every social platform these days.
NathanAvela
October 09, 2026, at 12:27 amenergy casino free spins omni casino latest no deposit bonus
free casino games on net admiral book of ra Online ruleta kako odigrat bonuse v casino online
slovenian online casino free slot games no download
Dennisveine
October 09, 2026, at 12:39 amroyal vegas casino 1000 free spins 365 live casino Vodnik po spletni ruleti casino admiral kozina bizi
brezplaДЌne igre casino casino rewards member casino
10 euro no deposit bonus casino
Williamnuava
October 09, 2026, at 12:47 amпанк мода
Dennisveine
October 09, 2026, at 12:57 amkazino online free toto live casino Katera je slovenska spletna igralnica? casino classic no deposit bonus
888 poker how to get 88 free najboljЕЎe spletne igralnice za slovenske igralce
casino online scams
NathanAvela
October 09, 2026, at 1:20 amjackpot druga ЕЎansa igre casino download
casino mond slovenia 5 min deposit online casinos Slovenske spletne igralnice free slots download
unibet live roulette cool cat casino no deposit bonus codes
Stevekeype
October 09, 2026, at 1:29 am[url=https://novobancoempresas.digital/]NOVO BANCO EMPRESAS[/url]
O NOVO BANCO apresenta as informações de forma clara e organizada, tornando mais simples conhecer os serviços disponíveis e encontrar os canais adequados de atendimento.
AlexSepCiX
October 09, 2026, at 1:37 amПомогаем получить второе гражданство или стать резидентом в разных странах мира. Смотрите [url=https://www.youtube.com/watch?v=OUSCRDQbB2o][b]вступительное видео[/b][/url]:
https://www.youtube.com/watch?v=OUSCRDQbB2o
Второе гражданство, Практическая иммиграция, Иммиграция, Вид на жительство, ВНЖ, Зелёная карта
Гражданство Евросоюза под ключ
Гражданство на основании корней
Гражданство Армении под ключ
Гражданство Кыргызстана под ключ
Гражданство Гражданство Польши под ключ
Гражданство Болгарии под ключ
Гражданство Италии под ключ
Гражданство Греции под ключ
Гражданство Израиля под ключ
Открыт ютуб-канал по вопросам [url=https://www.youtube.com/@migrapractice][b]иммиграции, получению второго гражданства или ВНЖ[/b][/url] в странах Евросоюза, СНГ и Америки.
Williamnuava
October 09, 2026, at 1:42 ampunk subculture
Williamnuava
October 09, 2026, at 3:04 amrrr9
Dennisveine
October 09, 2026, at 3:10 amfree casino roulette games casino admiral maribor Priporocena slovenska spletna igralnica captain cooks casino
best free to play poker site casino admiral liechtenstein
casino poker online free
NathanAvela
October 09, 2026, at 3:25 amslotjoint free spins no deposit free spins 2026
no deposit bonus 10 euro the best online casinos for slovenian players WinShark Which game can give me money without paying
fastest payout online casino apollo slot casino free coupons
Dennisveine
October 09, 2026, at 3:31 ambrezplaДЌne igre na igralnih avtomatih blackjack live free Spletna igralnica za pravi denar online blackjack game
20 euro no deposit bonus casino 21 blackjack online
casino fruit games
NathanAvela
October 09, 2026, at 3:37 amyukon gold casino free spins no deposit the best online casino acept paysafe card
jackpot capital no deposit bonus casino 1e deposit Casino Slovenija leovegas free spins win
funky time live casino casino 5 € deposit
Dennisveine
October 09, 2026, at 3:49 amwheel of fortune live casino online free online poker no deposit bonus 2026 Najboljsi bonusi igralnic v Sloveniji 365 bet win
free spins weekly cash out blackjack bet 365
casino online experiences
dostavka_wvsn
October 09, 2026, at 4:00 amЕсли вы ищете надежную [url=https://alkogol-dostavka-moskva-247-2.ru/]доставка алкоголя ночью на дом[/url] — мы всегда поможем вам насладиться любимыми напитками, не выходя из дома.
За последние годы услуга доставки алкоголя существенно выросла.
В большинстве случаев клиентам доступен разнообразный ассортимент алкоголя, который можно заказать прямо на дом .
Процесс заказа очень прост: достаточно выбрать понравившийся продукт, указать адрес и оформить заказ .
Время доставки зависит от региона, но большинство сервисов старается сделать ее максимально оперативной.
Заказывая алкоголь с доставкой, клиент избавляется от необходимости идти в магазины в неурочное время.
Отметим, что цены на услугу доставки зачастую вполне конкурентоспособны .
Надежные курьеры всегда соблюдают правила перевозки и доставляют напитки в целости .
Заказывая алкоголь с доставкой, пользователь получает возможность выбрать подходящий напиток, не выходя из дома .
NathanAvela
October 09, 2026, at 4:31 amlive casino online games vulkanvegas extra free spins
casino igre besplatno casino bonus brez depozita evropa za pravi denar Bizzo Slovenija all new online casinos
free spin paysafecard minimum deposit 5 euro casino
Dennisveine
October 09, 2026, at 6:02 amplay grand casino no deposit bonus casino online game Bonus dobrodoslice 2026 gunsbet casino free spins promo code
Which gambling sites give free bonuses bet365 bonus code join
10bet no deposit bonus
Dennisveine
October 09, 2026, at 6:23 ambizzo casino slovenija casino online besplatno Najboljsa Spletna Igralnica palace of chance casino no deposit bonus codes
bet at home slovenija ni dosegliv streЕѕnik casino bled forum
casino game slot machines free
ispytaniya_clkt
October 09, 2026, at 6:25 amДля получения подробной информации о процедуре и порядке проведения испытаний си, вы можете ознакомиться с нашими материалами по ссылке: [url=https://ispytaniya-msk.ru/]Продления и внесения изменения в ГРСИ[/url].
Также важна автоматизация процессов тестирования для повышения эффективности.
NathanAvela
October 09, 2026, at 6:36 am10 bet online casino casino poker online game
casino admiral colosseum eu casino online Igralni avtomati brez denarja admiral kongo casino
side bets blackjack limoplay casino no deposit bonus codes
WalterGoott
October 09, 2026, at 6:41 amcasino game lucky lady fanduel live casino Igre casino za pravi denar 777 casino no deposit bonus
grand theft auto online casino rocket stake casino bonus code
casino admiral austria
CoreyCat
October 09, 2026, at 6:49 amno deposit free bet slovenia 100 free spins no deposit
brezplaДЌni casino igre casino online bonus Igraj slote v casinu royal panda online casino
free casino slot games with bonus rounds slovenia casino online
CoreyCat
October 09, 2026, at 7:42 amcasino games flaming hot 32 online casino
casino rio ljubljana plus500 no deposit bonus Ruleta v online casinu Is Book of Ra a good slot
download free casino games for pc gonzo’s quest free spins
Remont_zsMl
October 09, 2026, at 7:47 am[url=https://remont-dvig124.ru]Ремонт двигателя в москве[/url] — профессиональный ремонт и диагностика двигателей автомобилей.
Необычные звуки, увеличение расхода топлива и дымление требуют своевременной проверки.
Подробная проверка помогает не менять детали, которые сохранили работоспособность.
Технологическая точность и аккуратность обязательны на каждом этапе восстановления двигателя.
Сразу после ремонта не рекомендуется резко ускоряться и перегружать двигатель.
WalterGoott
October 09, 2026, at 8:53 amslot igrice book of ra gameart slots go live with crypto casino ace Bonus brez depozita betstreak casino no deposit bonus codes 2026
joker poker free online jackpot lucky block
mrgreen casino no deposit bonus
WalterGoott
October 09, 2026, at 9:14 ammiami casino online mobile unibet live poker Najboljsa spletna igralnica v Sloveniji zodiac casino pc
no deposit bonus casino switzerland casino that gives you free bonuses no deposit
besplatne igre casino slot
WalterGoott
October 09, 2026, at 9:32 amcasino admiral igralni salon bizi all slots games free online Ugodnost brez depozita online casino is it safe
casino admiral tivoli lesce casino online lucky lady’s charm
casino igre za denar
CoreyCat
October 09, 2026, at 9:46 amcasino igri online free free online casino games
blackjack cheat sheet william hill casino slovenija Bonusi slovenskih igralnic casino admiral konoko
spletna igralnica za pravi denar perla casino slovenia email
CoreyCat
October 09, 2026, at 9:59 ambet365 no deposit bonus code 2026 hit casino perla slovenia
live blackjack online casino admiral casino bohemia prague Spletna igralnica v Sloveniji blackjack free game
online casino live streaming wheel of fortune live casino online
CoreyCat
October 09, 2026, at 10:53 amkazino igre brezplacno kateri spletni casino so ok
bounuse casino games online live holdem pro poker free casino games Online igralnica za pravi denar book of ra free games
black diamond online casino roy richie casino no deposit bonus
blspRag
October 09, 2026, at 11:45 am[center][b]Blsp At — рабочий вход 2025[/b][/center]
[center][i]Свежие зеркала напрямую[/i][/center]
[center][url=https://blsp-at-zayti.app][img]https://black-sprut.top/images/logo.png[/img][/url][/center]
Здарова! Скидываю рабочими адресами на blsp-at — крупный даркнет маркетплейс.
Сайт работает нормально — важно только использовать правильный вход. Вот 3 актуальных адреса:
[list=1]
[*] [url=https://blsp-at-zayti.app]Рабочий вход blsp at — без VPN[/url]
[*] [url=https://blacksprut-darknet.digital]Blacksprut — официальный сайт без VPN[/url]
[*] [url=https://bleksprut.sbs]Блекспрут официальный — вход без TOR[/url]
[/list]
Если какой-то переходник лагает — пробуйте следующий. Каждая ведут единую Мегу.
Сохраняйте — пригодится. Пишите если что.
[size=1][color=#333333]blsp at, https blsp at, blsp at сайт, m blsp at, k blsp at, v blsp at, n blsp at, blsp ap, blsp at check, blsp at клады, blsp at вход, blsp ay, blsp am, blsp com, blsp cc, blsp ссылка, bc blsp at, ntt k blsp at, w blsp at, blsp at отзывы, blsp at зеркало, blsp at 18, blsp at my balance, blsp at тг, blsp at зайти, blacksprut, blacksprut ссылка, blacksprut зеркало, blacksprut сайт, blacksprut работает, blacksprut официальный, blacksprut маркетплейс, blacksprut актуальные, blacksprut darknet, blacksprut даркнет, blacksprut вход, блекспрут сайт, блекспрут официальный, блекспрут официальный сайт, ссылки на блекспрут, блекспрут вход[/color][/size]
WalterGoott
October 09, 2026, at 11:46 ambig 5 casino no deposit bonus raging bull casino no deposit bonus codes 2026 Spletna Igralnica Paysafecard book of ra fixed
no deposit bonus casino 10 euro captain jack casino free 1000
vegas play casino no deposit bonus code 2026
WalterGoott
October 09, 2026, at 12:07 pmcasino free games lucky lady charm РёРіСЂР°ilni avtomati brezplaДЌno WinShark spletni casino paysafecard
casino 1 euro minimum deposit blackjack expected value
casino free spins no deposit 2026
WalterGoott
October 09, 2026, at 12:25 pmcasino games online free play slot book of ra download Slovenska igralnica igre za denar preko interneta
raging bull casino no deposit bonus codes video poker igre
all free slot games
INGRIDKEYMN
October 09, 2026, at 12:33 pmhttps://skazka-v-gosti.ru/
KASEYReiny
October 09, 2026, at 12:40 pmhttps://skazka-v-gosti.ru/newyear/
CoreyCat
October 09, 2026, at 12:57 pmЕѕrebanje eurojackpot ura perla casino slovenia kontakt
online casino 2026 wintingo online casino review Spletni casino za pravi denar s hitrimi izplacili casino igre rulet
blackjack video poker 10 bet online casino
lamicagenialepdfTaini
October 09, 2026, at 1:08 pmL’amicizia è un dono, ma può essere anche una condanna. L’amica geniale esplora questo dualismo con maestria. Elena Ferrante è una scrittrice straordinaria. Chi cerca L’amica geniale in versione PDF vuole immergersi in questa storia complessa e affascinante. Il formato elettronico è perfetto per i lettori di oggi. È un libro che parla di sentimenti veri, di passioni e di delusioni. Una storia che vi rimarrà nel cuore per sempre. Un capolavoro da leggere subito. https://lamicagenialepdf.site/ Elena Ferrante L’amica Geniale.pdf Iata
CoreyCat
October 09, 2026, at 1:10 pmcasino igre za zabavo bet365 bonus code existing customer
brezplacne casino igre book of ra book of ra unibet Online igralnica Slovenija book of ra symbol select buy bonus demo
white lotus casino no deposit bonus free bet blackjack
CoreyCat
October 09, 2026, at 2:03 pmbovegas no deposit bonus codes 2026 igre casino free
ruleta free game texas poker free game Brezplacni sloti intertops red casino no deposit bonus
multilotto casino no deposit bonus code swu8sa vegas online casino
WalterGoott
October 09, 2026, at 2:39 pmstarburst casino free spins book of ra deluxe 6 free Igralne masine v igralnici free texas holdem poker
blackjack multihand vip bet365 bonus terms
black lotus casino no deposit bonus
WalterGoott
October 09, 2026, at 3:00 pmpravila za blackjack book of ra casino games play free Bonus, za katerega ni treba vplacati kako izbrati varno spletno igralnico
betchan casino no deposit bonus codes vulkan casino online
apollo slot casino free coupons
WalterGoott
October 09, 2026, at 3:18 pmonline casino paypal spin palace casino no deposit free spins Katere igralniske igre izbrati? casino igre brezplaДЌne
koliko vrijedi as u blackjacku kako igrati pokerstars v sloveniji
bet365 joining bonus code
Jakeacach
October 09, 2026, at 3:24 pmNow noticing that the post never raised its voice even when making a strong point, and a look at nichepatch continued that calm volume, content that can make important points without resorting to typographic emphasis or emotional appeal is content that trusts its substance to do the work and this site has that confidence consistently.
CoreyCat
October 09, 2026, at 4:07 pmbook of ra tricks casino kranjska gora Г¶ffnungszeiten
igranje spletnih igr za denar lightning storm live casino Spletni casino Paysafecard casumo free spins
secrets of the phoenix free spins free spins weekly cashqout
CoreyCat
October 09, 2026, at 4:20 pmigre casino besplatne hit casino kranjska gora restaurant
luckyniki casino no deposit bonus online casino games Najbolj priljubljeni igralni avtomati na spletu v Sloveniji casino poker games
gametwist slots free slot machines casino games book of ra classic slot
ColinLip
October 09, 2026, at 4:56 pmThanks for the clean writing, no broken sentences and no awkward translations like some other sites have, and a quick stop at brighttrailartisanbazaar kept that polish going nicely, it really does make a difference when a reader can move through a page without tripping on every line or going back to reread.
CoreyCat
October 09, 2026, at 5:13 pmbet365 casino alternative link best online casino slot to win
casino korona kranjska gora vizija slot game free online casino Najvecji casino bonusi v Sloveniji luckyniki casino no deposit bonus
zodiac casino registration live casino top 10
RobertMer
October 09, 2026, at 5:25 pmnew movies to stream
WalterGoott
October 09, 2026, at 5:30 pmIs there a trick to winning online slot machines casino bonus brez depozita estonija Spletna zabava za denar slot game free casino deluxnovoma
casino igre gratis omni slot online casino
casino bled poker room
WalterGoott
October 09, 2026, at 5:51 pmkako igrati book of ra game of thrones slots free download Zahtevajte bonus brez depozita betchan casino no deposit bonus codes
list of all online casinos igre paysafecard izplacilo takoj casino
777 online casino
WalterGoott
October 09, 2026, at 6:09 pmgamingclub 30 free spins free game slot machine Igralnice s Paysafecard, pregled online casino bonus slovenia
casino bonus 100 4 kings slots no deposit bonus codes
casino igralni avtomati
CoreyCat
October 09, 2026, at 7:17 pmplay book of ra online casino slots free games play free game
casino simulation game What is a good online casino Igralni avtomati brez denarja kako igramo stave na bet 365
live casino online free casino admiral kongo bizi
Darrickwrela
October 09, 2026, at 7:31 pmfree money casino 2026 100 slovenija blackjack house edge
blackjack free play jackpot city casino Spletni casino astral bet online casino
bet 365 poker white screen happy slots 100 free spins
TyroneBus
October 09, 2026, at 8:07 pmНужен юрист? [url=https://www.pravovik24.ru/r/mo/dolgoprudnyy/]бесплатная юридическая консультация юриста в Долгопрудном[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Lonniedum
October 09, 2026, at 8:21 pmpoker igre casino best casino slot games free chip https://gostilna-rupar.si online casino sign up free spins
live casino house vegas play casino no deposit bonus code 2026
trada free spins
Leroyblott
October 09, 2026, at 8:21 pmЖуковский купить закладку Скорость a-pvp Музыкальные
Новохопёрск купить закладку Mephedrone (4mmc, мяу) Купить Кокаин, Мефедрон, Марихуану, МДМА Фрязино купить закладку MDMA Pills – RED
Каменск-Шахтинский купить Лирика 300мг (Прегабалин) Бородино купить закладку Mephedrone: Кристаллы VHQ
Darrickwrela
October 09, 2026, at 8:23 pmcasino admiral kosina live casino online working in slovenia
frank casino no deposit bonus hit casino korona kranjska gora Najboljsi online casino super casino no deposit bonus code
casino bonus brez depozita estonija casino portoroЕѕ vrhunske igre
Lonniedum
October 09, 2026, at 8:42 pmcasino besplatne igre avtomati best free no deposit casino bonus https://feastdvd.com free strip draw poker
online casino boss zodiac casino no deposit
bet365 bonus rules
Leroyblott
October 09, 2026, at 8:43 pmБудва купить закладку Cocaine HQ Талдом купить Марки LSD 170мкг
Спасск купить Мескалин Купить Кокаин, Мефедрон, Марихуану, МДМА Кашира купить Mephedrone: Мука HQ
Тобольск купить Mephedrone: Кристаллы VHQ Как опечатать сейф
Lonniedum
October 09, 2026, at 9:00 pmhopa casino online jackpot wheel casino no deposit bonus codes https://nodepositbonuscasinoslovenia.com bet 365 hands
blackjack kako se igra casino min deposit 5 euro
nj online casino
Leroyblott
October 09, 2026, at 9:02 pmНетания купить закладку Ecstasy: Yellow Homer 200mg Осташков купить Метамфетамин
ДжанкойОспаривается купить Мефедрон [Кристаллы] Купить Кокаин, Мефедрон, Марихуану, МДМА Людиново купить закладку Кристаллы соль
Цивильск купить закладку Mephedrone: Мука HQ Алапаевск купить закладку Амфетамин Сульфат белый
VALERYdal
October 09, 2026, at 9:13 pmhttps://intercom.help/bonuscode/el/articles/17036606-melbet-үнэгүй-бооцооны-промо-код-монгол-wap200
MichaelSuern
October 09, 2026, at 9:15 pmhttps://intercom.help/bonuscode/de-form/articles/17152331-1xbit-de-1xbit-al-registrarse-nicaragua-btc777-7-btc
inmydreamsiholdaknTaini
October 09, 2026, at 9:21 pmhttps://inmydreamsiholdaknifepdf.site/
Keithbar
October 09, 2026, at 9:39 pmhttps://intercom.help/bonuscode/en/articles/17143103-melbet-promo-code-list-india-2026-max888-450-bonus-up-to-60-000
blacksprutRag
October 09, 2026, at 9:43 pm[center][b]Blsp At — официальный сайт 2025[/b][/center]
[center][i]Проверенные зеркала напрямую[/i][/center]
[center][url=https://blsp-at.vip][img]https://black-sprut.top/images/logo.png[/img][/url][/center]
Здарова! Делюсь проверенными переходниками на blsp-at — крупный анонимный площадку.
Площадка открывается нормально — важно только иметь актуальный вход. Вот три проверенных варианта:
[list=1]
[*] [url=https://blsp-at-zayti.app]Рабочий вход blsp at — напрямую[/url]
[*] [url=https://black-sprut.app]Blacksprut — вход без TOR[/url]
[*] [url=https://bleksprut-vhod.site]Блекспрут — зеркало[/url]
[/list]
Если один из адресов не работает — пробуйте следующий. Все открывает единую площадку.
Сохраняйте — не потеряете доступ. Комментируйте если вопросы.
[size=1][color=#333333]blsp at, https blsp at, blsp at сайт, m blsp at, k blsp at, v blsp at, n blsp at, blsp ap, blsp at check, blsp at клады, blsp at вход, blsp ay, blsp am, blsp com, blsp cc, blsp ссылка, bc blsp at, ntt k blsp at, w blsp at, blsp at отзывы, blsp at зеркало, blsp at 18, blsp at my balance, blsp at тг, blsp at зайти, blacksprut, blacksprut ссылка, blacksprut зеркало, blacksprut сайт, blacksprut работает, blacksprut официальный, blacksprut маркетплейс, blacksprut актуальные, blacksprut darknet, blacksprut даркнет, blacksprut вход, блекспрут сайт, блекспрут официальный, блекспрут официальный сайт, ссылки на блекспрут, блекспрут вход[/color][/size]
ELLAKEYMN
October 09, 2026, at 9:48 pmhttps://intercom.help/bonuscode/ar/articles/16572788-calculating-parlay-payouts-a-practical-walkthrough-for-bettors
KILEYReiny
October 09, 2026, at 9:48 pmhttps://intercom.help/bonuscode/bg/articles/17026808-1xbet-sports-promo-code-malta-joinbet55-2026
LORELEIpeR
October 09, 2026, at 9:49 pmhttps://intercom.help/bonuscode/bs/articles/17141946-melbet-promo-code-list-kenya-2026-max888-bonus-ksh38-550
SENAIDAAvoip
October 09, 2026, at 9:57 pmhttps://intercom.help/bonuscode/de-AT/articles/17153547-1xbit-bonus-code-american-samoa-2026-btc777-bonus-7-btc
Darrickwrela
October 09, 2026, at 10:28 pmbet365 no deposit bonus hotel casino resort admiral kozina slovenia
casino games free online slot machines hit casino kranjska gora poker Slovenski spletni casinoji buffalo casino game
online casino 777 casino 5 euro
Darrickwrela
October 09, 2026, at 10:40 pmbesplatne casino igre na automatima admiral casino bohemia prague
omni casino no deposit free spins hopa casino online Hell Spin Slovenija online casino slots tips and tricks
vavada promo code caesars casino free slot machine games
Lonniedum
October 09, 2026, at 11:12 pmjackpot naslednje zrebanje online casino live streaming https://zooactive.si casino fruit games
promo 20 evrov za rojstni dan casino admiral casino 5 euro
best free no deposit casino bonus
Leroyblott
October 09, 2026, at 11:25 pmЧкаловск купить Mephedrone: Кристаллы VHQ Марка лсд купить
Вяземский купить Гашиш [Soft Hash] Купить Кокаин, Мефедрон, Марихуану, МДМА Москва Орехово-Борисово Северное купить закладку Кристаллы мёда
Новоуральск купить закладку Ecstasy: UPS 280mg Магас купить MDMA Crystal [Import]
Lonniedum
October 09, 2026, at 11:33 pmjoy casino 200 free spins which slot blackjack tips and tricks https://feastdvd.com besplatne casino igre aparati
non deposit bonus casino online jackpot city login
bwin live poker
Darrickwrela
October 09, 2026, at 11:34 pmreal time gaming casinos What casinos offer the most free spins
online casino phone deposit book of ra game slot Igraj Book of Ra na spletu bet365 first deposit bonus code
william hill casino no deposit bonus code 888 casino live chat
Leroyblott
October 09, 2026, at 11:48 pmАсино купить закладку Метадон, чистота 99% Юхнов купить закладку Героин в камнях
Новокуйбышевск купить закладку Купить Марихуану, Кокаин, Бошки, Гашиш Миллерово купить Ecstasy – UPS
Как коноплю курить Закладки метамфетамин в Борзе
Lonniedum
October 09, 2026, at 11:51 pmcasino admiral kongo promo za rojstni dan wynn slots free vegas casino slot games https://casinobonusbrezdepozita.si kako igrati pokerstars v sloveniji
online casino no deposit casino bonus free spins no deposit
best casino bonus buy
Leroyblott
October 10, 2026, at 12:07 amКоряжма купить закладку HQ Гашиш Марки в Санкт-петербурге
Соли закладки пятигорск Купить Кокаин, Мефедрон, Марихуану, МДМА Амурск купить закладку Мефедрон [Кристаллы]
Ессентуки купить Мескалин Адыгейск купить закладку MDMA Crystal [Import]
kalibrovka_guKa
October 10, 2026, at 1:01 amДля обеспечения точности измерений важно своевременно провести [url=https://kalibrovka-kalibrov.ru/]калибровка калибров колец[/url].
Без своевременной калибровки калибров невозможно обеспечить высокое качество продукции.
TyroneBus
October 10, 2026, at 1:27 amНужен юрист? [url=https://www.pravovik24.ru/r/mo/dolgoprudnyy/]консультация юриста 24 часа в Долгопрудном[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Darrickwrela
October 10, 2026, at 1:36 amzodiac casino pc seriöses online casino 2026
book of ra online free gaminator casino portoroz slovenia Spletna igralnica Paysafecard download free slot games with bonus rounds
hit casino kranjska gora restaurant monster casino no deposit bonus
Darrickwrela
October 10, 2026, at 1:49 amexclusive no deposit bonus red casino online
free vegas slots online online casino slovensko Bizzo casino Slovenija bonus za nove igralce river belle juegos de casino online
free spin casino cashout mastercard casino spletne igre
Allenatoft
October 10, 2026, at 2:01 amupcoming movies
Lonniedum
October 10, 2026, at 2:03 amunibet live roulette Which online casino has the best no deposit bonus https://lili-app.com online casino game
casino s bonus casino maribor slovenia
besplatne kazino igre na aparatima
brigada_dymn
October 10, 2026, at 2:05 amДля организации церемонии вы можете обратиться к [url=https://brigada-soprovozdeniya-na-pohoronah.ru/]сопровождение на похороны[/url], которая обеспечит профессиональное сопровождение.
Служба сопровождения при похоронах обеспечивает порядок и уважение часто привлекается для обеспечения торжественной и dignified церемонии. Их задача — сделать прощание максимально гладким и трогательным . В их обязанности входит контроль за соблюдением порядка, взаимодействие с гостями и организация процедур в соответствии с традициями.
Важнейшая задача бригады — обеспечить соблюдение всех необходимых этапов похорон . Они отвечают за интерьер, оформление зала и соблюдение порядка, что помогает создать уважительную атмосферу. Эти специалисты также взаимодействуют с родственниками и другими служащими, чтобы всё прошло без сбоев, с соблюдением всех правил.
Она обеспечивает плавное проведение всех этапов прощания. Они следят за соблюдением порядка, помогают с организацией речей и помогают гостям развлечься и проявить сострадание. Их участие — важнейшее условие для достойного и трогательного прощания.
Они помогают провести все финальные обряды мирно и уважительно. В эти моменты их задача — поддержать родственников и обеспечить плавный переход к следующему этапу. Эти специалисты помогают создать атмосферу спокойствия и уважения для всех участников прощания.
Lonniedum
October 10, 2026, at 2:24 ambook of ra prenos igre brezplaДЌne casino spletne igre https://fcmontceau-bourgogne.com What apps have free spins
fone casino no deposit bonus thebigfreechiplist the best online casino aceptslovenia players
zodiac casino forum
Leroyblott
October 10, 2026, at 2:32 amстаф в Кировград Дорогобуж купить Mephedrone: Мука HQ
Москва Хорошёвский купить закладку Ecstasy: UPS 280mg Купить Кокаин, Марихуану, Бошки, Мефедрон Спасск-Рязанский купить Мефедрон [Cristalius 2.0]
Апрелевка купить закладку MDMA Pills Москва Орехово-Борисово Северное купить закладку
Lonniedum
October 10, 2026, at 2:42 amcarnival free spins zodiac casino free download https://casinoigrezadenar.si casino mond slovenia
casino admiral online book of ra online casino real money
online casino bonus bez depozita
Darrickwrela
October 10, 2026, at 2:43 amcasinos online slovenia free spins frank casino online
casino poker online game free spin casino cash out mastercard Spletni casino s Paysafecard black jack ДЌrnuДЌe
hit holidays kranjska gora casino casino admiral san roque
Leroyblott
October 10, 2026, at 2:54 amОстров купить Ecstasy – UPS купить онлайн закладку в Медынь
Ханты-Мансийск купить NBOME Купить Кокаин, Марихуану, Бошки, Мефедрон Межгорье купить кокаин
Невинномысск купить закладку Ecstasy – Homer / Bart Вилюйск купить закладку HQ Гашиш
bipudMIP
October 10, 2026, at 3:00 amИщете вскрытие дверей? Посетите spb-open24.ru – работаем в Санкт-Петербурге и Ленинградской области аккуратно и без повреждений, а мастер приезжает очень быстро. Хотите вызвать специалиста – просто позвоните по телефону, размещённому на сайте. Ознакомьтесь с типами замков, с которыми мы работаем и ценами на их вскрытие. Платить нужно только тогда, когда работа полностью выполнена.
fgtifoeno
October 10, 2026, at 3:00 am[b][url=https://teselectro.ru]лампа газоразрядная[/url][/b]
Мультиметр подбирают с учетом характера работ и требований к безопасности. При выборе учитывают технические характеристики, совместимость с оборудованием и условия эксплуатации. Грамотный подбор помогает оптимизировать бюджет проекта и соблюсти необходимые технические требования.
Может быть полезным: https://teselectro.ru/shop/elektroustanovocnye-izdeliia/udliniteli-bloki-rozetok-razvetviteli-perexodniki/udlinitel-kabelnyi-na-katuskebarabane/product/ukg02-16-r325-4-40-ip44-2842806 или [url=https://teselectro.ru]кабель[/url]
[b][url=https://teselectro.ru]удлинитель[/url][/b]
Светильник дсп используется при создании современных систем освещения на объектах различного назначения. Качественные электротехнические материалы и комплектующие помогают обеспечить стабильную работу системы. Перед покупкой параметры изделия следует сопоставить с проектной документацией и требованиями оборудования.
Leroyblott
October 10, 2026, at 3:13 amТомская область купить закладку Ecstasy Rolls Royce Серафимович купить Ecstasy: Red Monkey 250mg
Москва Бибирево купить Кокаин MQ Купить Кокаин, Марихуану, Бошки, Мефедрон купить онлайн закладку в Арамиль
Ленинградская область купить Ecstasy Rolls Royce Устюжна купить Мефедрон [мелкие камни/мука] HQ
Stevekeype
October 10, 2026, at 3:38 am[url=https://novobancoempresas.net/]NOVO BANCO LOGIN[/url]
A área NOVO BANCO EMPRESAS reúne informações úteis para as empresas e facilita a consulta das soluções disponíveis para a gestão financeira diária.
Darrickwrela
October 10, 2026, at 4:47 amcasino demo games online casinos with neon life
15 euro no deposit bonus book of ra slot gratis Casino igre na spletu za zacetnike in izkusene igralce jackpot junction casino
Why is the book of Ra so popular 50 euro bonus brez depozita casino
Lonniedum
October 10, 2026, at 4:55 ambook of ra 6 deluxe free play slot game free igt https://lili-app.com free casino games real money
gratorama casino online Is there a trick to winning online slot machines
hotel casino resort admiral
Darrickwrela
October 10, 2026, at 4:59 amslotocash casino no deposit bonus 2026 casino slots free games play free game
no deposit bonus free spin only in slovenija free casino slot machines to play Slovenske igralnice online najboljЕЎi casino bonus slovenija
casino med no deposit bonus casino game bombay
Lonniedum
October 10, 2026, at 5:16 amfree casino games no download no registration no download australian online casino https://fewo-seerose.com casino bonus brez depozita evropa
club gold casino online online casino slovenija forum
Does the €20 trick work in Vegas
Lonniedum
October 10, 2026, at 5:34 am25 euro no deposit bonus book of ra magic free play https://pulmo-panjan.si free spins casino no deposit new codes 2026
casino igri online free blackjack basic strategy
casino admiral nova gorica
Leroyblott
October 10, 2026, at 5:37 amМегион купить Мефедрон [Cristalius 2.0] Бобров купить Кокаин HQ
Москва Савёлки купить Cocaine Premium: Peru Купить Кокаин, Марихуану, Бошки, Мефедрон купить клад в Куйбышев
Себеж купить закладку Гашиш [Euro Cube] Купить Гашиш в Людиново
Darrickwrela
October 10, 2026, at 5:51 ammajestic slots no deposit bonus codes betting sites deposit paypal slovenia
bonus funds bet 365 casino slot igre WinShark igralnica free jokers wild video poker games
casino bonus brez depozita 10 euro jackpot city casino bonus codes
Leroyblott
October 10, 2026, at 5:59 amМосква Донской купить Гашиш [LV] Москва Чертаново Северное купить закладку Кокаин MQ
Оленегорск купить Альфа Купить Кокаин, Мефедрон, Марихуану, МДМА Москва Бирюлёво Восточное купить Героин РОЗНИЦА (999 VHQ) Афганистан
Наркотики на Бали Вышний Волочёк купить закладку HQ Гашиш NO NAME
Leroyblott
October 10, 2026, at 6:18 amСатка купить закладку Триптамины Ставрополь купить закладку Ecstasy: Pink Heart 200mg
Москва Тушино Южное купить шишки Купить Кокаин, Мефедрон, Марихуану, МДМА Москва Филёвский парк купить закладку Метадон, чистота 99%
Москва Проспект Вернадского купить закладку План (АФГАНКА) Купить Кокс Кедровый
Lonniedum
October 10, 2026, at 7:47 amchances to get free spins on slot machines casino table games https://inlpta.si vip programs on online casinos
book of ra two symbols casino on bet365
quick hit casino slots free slot machines games
Darrickwrela
October 10, 2026, at 7:51 amhotel casino kozina slovenia bet 365 aplikacija za iso ki deluje
bet 365 register streaming 50 euro bonus brez depozita casino Igraj ruleto online live casino online game
luckyniki casino no deposit bonus code besplatne casino igre na automatima
Haroldbot
October 10, 2026, at 7:57 amSkipped the related links section thinking I had read enough and then came back to it later when curiosity got the better of me, and a stop at nightnarrative confirmed I should have just read it first, every section of this site appears to deserve careful attention rather than skipping past lazily.
Darrickwrela
October 10, 2026, at 8:04 amWhat is the most paid out online casino casino igre pol-o-slot
play poker onine free paypal online casinos Casino sloti casino dice game
jackpot online casino free spin no deposit europa casino 2026
Lonniedum
October 10, 2026, at 8:07 amhit hotel casino kranjska gora 888 casino monopoly live https://casinoigrezadenar.si bet365 alternative app
brezplacne casino igre 3k free slots
power spins 50 free spins
Lonniedum
October 10, 2026, at 8:25 amfree casino games slots no download vulkan vegas no deposit bonus code https://fewo-seerose.com surf casino no deposit bonus
10 euro free casino book of ra greentube
Which online casino actually pays real money
Leroyblott
October 10, 2026, at 8:37 amКаменка купить закладку LSD-25 в марках 250мк Чкаловск купить Cтимуляторы
Южа купить Героин в камнях Купить Марихуану, Кокаин, Бошки, Гашиш Петровск-Забайкальский купить закладку Амфетамин Сульфат белый
Бодайбо купить закладку бошки Ипатово купить закладку Триптамины
Darrickwrela
October 10, 2026, at 8:55 ammongoose casino no deposit bonus codes cyberspins casino free spins codes
bet365 first deposit bonus terms casino bled kristina Book of Ra online hotel casino lipica slovenia
igrice book of ra slovenija online casino reviews
Leroyblott
October 10, 2026, at 8:59 amЧехия купить LSD После укола немеет нога
Миасс купить Euro HQ Hash (ЧЕРНЫЙ) Купить Кокаин, Мефедрон, Марихуану, МДМА Южа купить закладку Кристаллы мёда
Муравленко купить закладку Кокаин Какой эффект от героина
demiparamipdfTaini
October 10, 2026, at 9:03 amEncontrar motivación genuina es difícil, pero los libros de Nacarid Portal Arráez y Chriss Braund son una fuente inagotable de ella. Puedes con esto y más te reta a superar tus límites mentales. La estética del libro es tan importante como su mensaje, y se aprecia genial en cualquier formato. Al buscar de mi para mi pdf, te unes a una comunidad de lectores que han decidido tomar las riendas de su vida emocional. Es una obra indispensable para tu colección digital, llena de luz y verdad. https://demiparamipdf.site/ Que Significa Para Mi Sindrome De Asperger Pdf
Leroyblott
October 10, 2026, at 9:18 amСеверо-Курильск купить закладку Порох 999 (HQ) Афган Сибай купить закладку Cocaine Premium: Peru
Киров купить METHADONE Купить Марихуану, Кокаин, Бошки, Гашиш Купить Дурь Кстово
Струнино купить закладку Mephedrone (4mmc, мяу) Ефремов купить закладку Cocaine HQ
fopelicktax
October 10, 2026, at 9:18 amПрофиль продавца на Копейке.шоп — находка для любителей активного отдыха: здесь представлен внушительный ассортимент квадроциклов с доставкой по всей России и удобной оплатой после получения. В каталоге — модели Loncin, Zongshen, Mikilon и другие по ценам от 150 000 до 425 000 рублей. Загляните на https://kopeika.shop/users/156117, чтобы выбрать надёжную технику для бездорожья и оценить предложения продавца из Хабаровска.
SpencerAxora
October 10, 2026, at 10:19 amНужен юрист? [url=https://www.pravovik24.ru/r/mo/dubna/]консультация юриста 1 час в Дубне[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Lonniedum
October 10, 2026, at 10:38 amonline mobile casino no deposit bonus big dollar casino no deposit bonus codes https://nodepositbonuscasinoslovenia.com casino bled hotel
hit casino korona kranjska gora free poker cash no deposit needed
coyote moon slot game free
nomiumrukem
October 10, 2026, at 10:50 amблокчейн разработка
ochered-u-ekrana.site
как создать блокчейн платформу свою
Darrickwrela
October 10, 2026, at 10:55 ambook of dead free spins black lotus no deposit bonus
21 dukes 25 free spins win2fun casino no deposit bonus Spletni casino s Paysafecard spinia casino no deposit bonus
What casino has free signup bonus no deposit required novomatic book of ra deluxe
Lonniedum
October 10, 2026, at 10:59 amhouse of fun free spins blackjack vs roulette odds https://lili-app.com twist casino no deposit bonus codes
no deposit sign up bonus casino igre slot slot
juicy stakes casino no deposit bonus 100
Darrickwrela
October 10, 2026, at 11:07 amnine casino bonus code hit casino korona kranjska gora
slot game free igt the online casino Brezplacni avtomati free spins symbol
free poker programs igre casino avtomati
Lonniedum
October 10, 2026, at 11:17 amblackjack kako se igra largest online casino https://zooactive.si web slot casino online
Which casino app gives free spins online casino is it safe
vegas slots online casino
Leroyblott
October 10, 2026, at 11:36 amамфетамин капли Пудож купить наркотики
Нижневартовск купить закладку Ecstasy – UPS Купить Кокаин, Мефедрон, Марихуану, МДМА Куса купить Марихуана [Hillary Clinton Kush]
Городовиковск купить гашиш Амурск купить Героин натуральный
nomiumrukem
October 10, 2026, at 11:39 amзаказать разработку web приложения
ochered-u-ekrana.site
блокчейн разработчик
Leroyblott
October 10, 2026, at 12:17 pmКупить конопля Норильск Электрогорск купить закладку Mephedrone: Кристаллы VHQ
Дорогобуж купить NBOME Купить Кокаин, Марихуану, Бошки, Мефедрон Плавск купить закладку Гашиш [Soft Hash]
Гусев купить Героин в камнях Мускатный орех как есть
nomiumrukem
October 10, 2026, at 12:26 pmблокчейн разработка платформы
ochered-u-ekrana.site
нанять инженера блокчейн инфраструктуры
Josephamips
October 10, 2026, at 1:30 pmmobile slots no deposit bonus casino admiral san roque Darilo dobrodoslice What is the WILD250 bonus code
welcome bonus no deposit casino igre besplatne slots
nomiumrukem
October 10, 2026, at 1:37 pmвнедрение геймификации
ochered-u-ekrana.site
devops услуги
Josephamips
October 10, 2026, at 1:51 pmomni casino latest no deposit bonus voucher code for jackpot city Katera igralnica sprejema Paysafecard? casino game developer of the year casino
free spin to casheout online games kazino
DavidNef
October 10, 2026, at 1:59 pmbet365 100 bonus free slot machine play
2000 free casino games book of ra games Casino igre na spletu za zacetnike in izkusene igralce jackpot cash casino no deposit bonus
live casino evolution gaming web slot casino online
Josephamips
October 10, 2026, at 2:09 pmbetway live casino book of ra deluxe resolution Igralnica s placilom Paysafecard bet 365 alternativ link
book of ra games slot playamo casino no deposit bonus codes
DavidNef
October 10, 2026, at 2:11 pmcasino bled zetoni vrednost blackjack online real money
casino bonus app casino casino no deposit bonus code Igralni avtomati na spletu casino bled poker room
free video slots spletne casino igre
MathewCycle
October 10, 2026, at 2:35 pmСураж купить марихуану Купить закладки спайс россыпь в Кропоткине
Касимов купить закладку Купить Кокаин, Мефедрон, Марихуану, МДМА Бокситогорск купить закладку LSD-25 в марках 250мк
Закладки марки в Тихвине Бийск купить АК-47 – Бошки Шишки
MathewCycle
October 10, 2026, at 2:57 pmкупить клад Санкт-Петербург Губкинский купить Марихуана [Outstanding Kush]
Невьянск купить закладку Шишки HQ АК47 Купить Кокаин, Мефедрон, Марихуану, МДМА Комсомольск-на-Амуре купить Cтимуляторы
Услуга «Продли скорость 1 Гб» — «Билайн» Курск Искитим купить закладку Molly: MDMA HQ
nomiumkem
October 10, 2026, at 2:58 pmкак создать криптообменник с нуля
ochered-u-ekrana.site
нанять инженера блокчейн инфраструктуры
DavidNef
October 10, 2026, at 3:02 pmmobilni casino slovenija galabingo free spins code
casino igri online besplatno igre online casino Ruleta v online casinu paysafecard online casino
astral bet online casino 300 shield free slot machine
MathewCycle
October 10, 2026, at 3:16 pmкупить клад Шахунья Волосово купить Cocaine HQ
Курлово купить закладку LSD 220 мг Купить Кокаин, Марихуану, Бошки, Мефедрон Сызрань купить DMT
Добрянка купить Ecstasy: Red Stars 280 mg Как приготовить наркотик соль
punter_izka
October 10, 2026, at 4:17 pmBeen reading this board for a while, thought I would drop what I look at before signing up anywhere. After getting burned once or twice I learned to read the small print first.
I always start with licensing: find the licence number and look it up, because some sites quietly block certain regions. After that I look at banking: I want at least one fast e-wallet option, and there should be no weird fees on cashouts.
The welcome offer is where most people get caught. Read the wagering and the max bet rule, and live tables often do not count at all. A decent independent write-up with the current terms is worth a read here [url=https://tudomuaban.com/chi-tiet-rao-vat/3047954/rolletto—real-money-gaming-in-2026-a-practical-player-guide.html]bonus at Rolletto[/url] and it saved me some time.
Most of my sessions are on mobile, and if there is an app I make sure it comes from the official page. Ask support one simple question first: if they answer in a couple of minutes that is a good sign.
That is about it. Only play with money you can afford to lose.
highroll_exKi
October 10, 2026, at 4:17 pmMostly a reader, rarely post, but I figured I would share what I look at before signing up anywhere. After trying maybe a dozen sites I stopped going by ads alone.
Licence comes first for me: check who regulates the site, because some sites quietly block certain regions. After that I look at banking: I want at least one fast e-wallet option, and the withdrawal limits need to be written clearly.
Never judge a site by the bonus alone. Anything above 40x rollover is a red flag for me, and live tables often do not count at all. A good recent review that covers all of this is worth a read here [url=https://tudomuaban.com/chi-tiet-rao-vat/3049058/just4win-casino—real-money-gaming-in-2026-a-practical-player-guide.html]learn more[/url] so you know what you are signing up for.
I play almost only on my phone, so I check how the lobby works on a small screen. Ask support one simple question first: a real human reply beats a bot loop.
Hope this helps someone. Treat it as entertainment, not income.
SpencerAxora
October 10, 2026, at 4:17 pmНужен юрист? [url=https://www.pravovik24.ru/r/mo/dubna/]нужен юрист адвокат в Дубне[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Josephamips
October 10, 2026, at 4:21 pmigralnica casino bled most profitable online casino Katere igre so za denar? wellcome bonus casino online
book of ra 2 juicy stakes no deposit bonus
jackpot_onml
October 10, 2026, at 4:30 pmLong time lurker here, but I figured I would share how I pick an online casino these days. After trying maybe a dozen sites I learned to read the small print first.
I always start with licensing: check who regulates the site, and if your country is on the allowed list. After that I look at banking: card, e-wallets and bank transfer should all be there, and there should be no weird fees on cashouts.
Bonuses are the tricky part. Wagering of 35x or 40x is normal, and live tables often do not count at all. A good recent review that covers all of this is worth a read here [url=https://guidehub0ef599.omeka.net/items/show/54]lees meer[/url] and it saved me some time.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Ask support one simple question first: if they answer in a couple of minutes that is a good sign.
That is about it. Treat it as entertainment, not income.
spinner_vgmr
October 10, 2026, at 4:33 pmLong time lurker here, thought I would drop my short checklist for choosing a casino site. After a few bad experiences I stopped trusting the big banners.
Licence comes first for me: see which authority is listed in the footer, and if your country is on the allowed list. Next come deposits and withdrawals: I want at least one fast e-wallet option, and cashout times should be listed up front.
The welcome offer is where most people get caught. Read the wagering and the max bet rule, and the bonus usually expires in a week or two. A useful overview with bonus rules, app info and payment methods is worth a read here [url=https://vocal.media/authors/lilibet-casino-4f76d28db7]Lilibet Casino app[/url] and it saved me some time.
On mobile I mostly use the browser version, and a good site loads fast and does not log you out every five minutes. Test the live chat before depositing: slow or scripted answers usually mean trouble later.
Hope this helps someone. Treat it as entertainment, not income.
Josephamips
October 10, 2026, at 4:42 pmonline casino 25 free spins best online casino in world Igre na avtomatih admiral book of ra
zodiac casino mobile platinum casino online
Josephamips
October 10, 2026, at 4:59 pmcasino kingdom online casino casino 20 euro no deposit Vodnik po igrah na avtomatih igre casino aparati
play blackjack online free brezplacne casino igre piramide
lucky_lhsl
October 10, 2026, at 5:01 pmMostly a reader, rarely post, thought I would drop how I pick an online casino these days. After getting burned once or twice I learned to read the small print first.
I always start with licensing: check who regulates the site, because some sites quietly block certain regions. Then payments: I want at least one fast e-wallet option, and the withdrawal limits need to be written clearly.
The welcome offer is where most people get caught. Wagering of 35x or 40x is normal, and the bonus usually expires in a week or two. A useful overview with bonus rules, app info and payment methods is here [url=https://cpguided0646ff0.canalblog.com/slotshopper-casino-giochi-da-casino-live-nel-2026-guida-pratica.html]Slotshopper[/url] and it saved me some time.
I play almost only on my phone, so I check how the lobby works on a small screen. Support matters too: if they answer in a couple of minutes that is a good sign.
Anyway, that is my routine. Only play with money you can afford to lose.
MathewCycle
October 10, 2026, at 5:36 pmВыборг купить Марки LSD Нариманов купить закладку Метадон, чистота 99%
Бикин купить закладку гашиш Купить Кокаин, Мефедрон, Марихуану, МДМА Каменск-Шахтинский купить закладку бошки
Копейск купить Мефедрон [мелкие камни/мука] HQ Алатырь купить LSD-25 (HQ) 170мкг
MathewCycle
October 10, 2026, at 5:56 pmЗнаменск купить закладку Амфетамин Сульфат белый Чекалин купить закладку LSD-25 в марках 250мк
Хаммамет купить закладку АК-47 – Бошки Шишки Купить Кокаин, Мефедрон, Марихуану, МДМА Купи клад череповец
Алексеевка купить VHQ Cocaine 98% Bolivia Балабаново купить закладку гидропонику
DavidNef
October 10, 2026, at 6:05 pmЕЎtetje kart blackjack dragon tiger live casino
book of ra fixed casino free texas holdem poker Book of Ra igra admiral casino bohemia prague
bet 365 multiple bet online casino lucky lady charm
MathewCycle
October 10, 2026, at 6:15 pmЗакладки реагент в Ревде Болгария купить закладку гашиш
Флуоксетин трип Купить Марихуану, Кокаин, Бошки, Гашиш Городище купить METHADONE
Почта без подтверждения смс Екатеринбург купить закладку Мефедрон [Кристаллы]
Josephamips
October 10, 2026, at 7:11 pmbwin live blackjack casino igre slot besplatne Spletna igralnica, kjer lahko placate s Paysafecard energy casino free spins
casino igre slotovi casino slots free spins
AaronWah
October 10, 2026, at 7:30 pmХорошее место для доходного бизнеса.
[url=https://vgorakh.ru/]риски доверительного управления недвижимостью[/url]
Josephamips
October 10, 2026, at 7:32 pmgovernor of poker full game download free no deposit bonus casino zar Kako delujejo igralni avtomati? casino blackjack rules
blackjack vs baccarat free vegas casino slots
jackpot_dlml
October 10, 2026, at 7:33 pmLong time lurker here, so here is how I pick an online casino these days. After getting burned once or twice I learned to read the small print first.
Licence comes first for me: see which authority is listed in the footer, and if your country is on the allowed list. After that I look at banking: card, e-wallets and bank transfer should all be there, and the withdrawal limits need to be written clearly.
The welcome offer is where most people get caught. Wagering of 35x or 40x is normal, and live tables often do not count at all. A decent independent write-up with the current terms is worth a read here [url=http://weblabor.hu/tagok/122115]slott casino[/url] so you know what you are signing up for.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Support matters too: a real human reply beats a bot loop.
Hope this helps someone. Only play with money you can afford to lose.
spinner_qwmr
October 10, 2026, at 7:36 pmLong time lurker here, but I figured I would share what I look at before signing up anywhere. After getting burned once or twice I stopped going by ads alone.
Licence comes first for me: check who regulates the site, and if your country is on the allowed list. Next come deposits and withdrawals: I want at least one fast e-wallet option, and the withdrawal limits need to be written clearly.
Never judge a site by the bonus alone. Read the wagering and the max bet rule, and the bonus usually expires in a week or two. A decent independent write-up with the current terms is worth a read here [url=https://blogs.rufox.com/~maxim378eb4/91128.htm]Gamblezen[/url] so you know what you are signing up for.
I play almost only on my phone, and a good site loads fast and does not log you out every five minutes. Test the live chat before depositing: if they answer in a couple of minutes that is a good sign.
That is about it. Set a budget and stick to it.
punter_qmka
October 10, 2026, at 7:45 pmLong time lurker here, but I figured I would share what I look at before signing up anywhere. After getting burned once or twice I stopped going by ads alone.
First thing is the licence: find the licence number and look it up, and if your country is on the allowed list. Then payments: card, e-wallets and bank transfer should all be there, and there should be no weird fees on cashouts.
The welcome offer is where most people get caught. Wagering of 35x or 40x is normal, and some games count less towards it. A useful overview with bonus rules, app info and payment methods is worth a read here [url=https://www.articleted.com/article/1249729/427726/a-practical-guide-to-trino-casino-for-smart-players-in-2026]Trino Casino[/url] and it saved me some time.
On mobile I mostly use the browser version, so I check how the lobby works on a small screen. Ask support one simple question first: slow or scripted answers usually mean trouble later.
That is about it. Only play with money you can afford to lose.
highroll_geKi
October 10, 2026, at 7:48 pmMostly a reader, rarely post, but I figured I would share what I look at before signing up anywhere. After a few bad experiences I stopped trusting the big banners.
I always start with licensing: find the licence number and look it up, because some sites quietly block certain regions. After that I look at banking: card, e-wallets and bank transfer should all be there, and cashout times should be listed up front.
Bonuses are the tricky part. Read the wagering and the max bet rule, and some games count less towards it. A good recent review that covers all of this is here [url=https://www.dibiz.com/activation+dbz6747f97096]learn more[/url] and it saved me some time.
Most of my sessions are on mobile, and a good site loads fast and does not log you out every five minutes. Ask support one simple question first: slow or scripted answers usually mean trouble later.
Hope this helps someone. Treat it as entertainment, not income.
Josephamips
October 10, 2026, at 7:50 pmfree slot games no download gunsbet casino free spins promo code Hell Spin blackjack casino rewards
free spin no deposit bonus casino 2026 spin and win casino no deposit bonus codes
jackpot_ioml
October 10, 2026, at 7:57 pmBeen reading this board for a while, but I figured I would share how I pick an online casino these days. After a few bad experiences I learned to read the small print first.
First thing is the licence: see which authority is listed in the footer, and if your country is on the allowed list. After that I look at banking: card, e-wallets and bank transfer should all be there, and there should be no weird fees on cashouts.
Never judge a site by the bonus alone. Read the wagering and the max bet rule, and some games count less towards it. A useful overview with bonus rules, app info and payment methods can be found here [url=https://legendary11.com/blogs/view/66309]Superbet[/url] so you know what you are signing up for.
I play almost only on my phone, so I check how the lobby works on a small screen. Ask support one simple question first: slow or scripted answers usually mean trouble later.
That is about it. Only play with money you can afford to lose.
spinner_tzmr
October 10, 2026, at 7:59 pmLong time lurker here, but I figured I would share how I pick an online casino these days. After getting burned once or twice I stopped trusting the big banners.
I always start with licensing: find the licence number and look it up, and whether they actually accept players from your country. Next come deposits and withdrawals: I want at least one fast e-wallet option, and the withdrawal limits need to be written clearly.
Bonuses are the tricky part. Anything above 40x rollover is a red flag for me, and the bonus usually expires in a week or two. A decent independent write-up with the current terms is here [url=https://sites.google.com/view/lilibet-casino-7089/]Lilibet Casino app[/url] so you know what you are signing up for.
On mobile I mostly use the browser version, and a good site loads fast and does not log you out every five minutes. Test the live chat before depositing: if they answer in a couple of minutes that is a good sign.
That is about it. Set a budget and stick to it.
DavidNef
October 10, 2026, at 8:04 pmkako igrati pokerstars v sloveniji igrice book of ra
bwin live blackjack casino igre za zabavo Primerjava casino bonusov v Sloveniji casino admiral svaty kriz
deposit 1 euro get bonus aristocrat free slots
highroll_cwKi
October 10, 2026, at 8:11 pmMostly a reader, rarely post, but I figured I would share what I look at before signing up anywhere. After getting burned once or twice I stopped going by ads alone.
Licence comes first for me: check who regulates the site, and if your country is on the allowed list. After that I look at banking: card, e-wallets and bank transfer should all be there, and the withdrawal limits need to be written clearly.
Bonuses are the tricky part. Read the wagering and the max bet rule, and some games count less towards it. A useful overview with bonus rules, app info and payment methods can be found here [url=http://weblabor.hu/tagok/122111]Just Casino app[/url] and it saved me some time.
On mobile I mostly use the browser version, and a good site loads fast and does not log you out every five minutes. Test the live chat before depositing: if they answer in a couple of minutes that is a good sign.
That is about it. Treat it as entertainment, not income.
punter_uoka
October 10, 2026, at 8:12 pmLong time lurker here, but I figured I would share what I look at before signing up anywhere. After trying maybe a dozen sites I learned to read the small print first.
Licence comes first for me: see which authority is listed in the footer, because some sites quietly block certain regions. Next come deposits and withdrawals: card, e-wallets and bank transfer should all be there, and the withdrawal limits need to be written clearly.
Bonuses are the tricky part. Wagering of 35x or 40x is normal, and live tables often do not count at all. A decent independent write-up with the current terms can be found here [url=http://forum.casino.digitalleisure.com/member.php?action=profile&uid=4210]revery play casino[/url] before you deposit anything.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Ask support one simple question first: if they answer in a couple of minutes that is a good sign.
That is about it. Set a budget and stick to it.
jackpot_xdml
October 10, 2026, at 8:13 pmMostly a reader, rarely post, so here is how I pick an online casino these days. After getting burned once or twice I learned to read the small print first.
First thing is the licence: see which authority is listed in the footer, because some sites quietly block certain regions. Then payments: crypto is a plus but not a must, and there should be no weird fees on cashouts.
Never judge a site by the bonus alone. Anything above 40x rollover is a red flag for me, and the bonus usually expires in a week or two. A useful overview with bonus rules, app info and payment methods is here [url=https://vocal.media/authors/slott-casino]Slott app[/url] and it saved me some time.
Most of my sessions are on mobile, and a good site loads fast and does not log you out every five minutes. Support matters too: slow or scripted answers usually mean trouble later.
That is about it. Only play with money you can afford to lose.
spinner_ymmr
October 10, 2026, at 8:15 pmBeen reading this board for a while, but I figured I would share how I pick an online casino these days. After getting burned once or twice I stopped trusting the big banners.
I always start with licensing: find the licence number and look it up, because some sites quietly block certain regions. Next come deposits and withdrawals: crypto is a plus but not a must, and cashout times should be listed up front.
The welcome offer is where most people get caught. Anything above 40x rollover is a red flag for me, and live tables often do not count at all. A good recent review that covers all of this is worth a read here [url=https://www.intensedebate.com/people/idurgv51fs]Gamblezen[/url] and it saved me some time.
Most of my sessions are on mobile, and a good site loads fast and does not log you out every five minutes. Ask support one simple question first: if they answer in a couple of minutes that is a good sign.
That is about it. Set a budget and stick to it.
DavidNef
October 10, 2026, at 8:17 pmblackjack not gambling free strip draw poker
casino korona slovenia deposit free spins Igraj Book of Ra v spletnem casinu za pravi denar free slot casino games with bonus
house of fun free spins 32 online casino
lucky_zksl
October 10, 2026, at 8:24 pmLong time lurker here, thought I would drop my short checklist for choosing a casino site. After getting burned once or twice I stopped trusting the big banners.
First thing is the licence: check who regulates the site, and if your country is on the allowed list. After that I look at banking: I want at least one fast e-wallet option, and cashout times should be listed up front.
The welcome offer is where most people get caught. Wagering of 35x or 40x is normal, and some games count less towards it. A useful overview with bonus rules, app info and payment methods can be found here [url=https://uberant.com/article/2183330-lottoland-finland-real-money-gaming-in-2026-a-practical-player-guide]Lottoland[/url] before you deposit anything.
Most of my sessions are on mobile, and a good site loads fast and does not log you out every five minutes. Support matters too: a real human reply beats a bot loop.
That is about it. Treat it as entertainment, not income.
highroll_smKi
October 10, 2026, at 8:27 pmLong time lurker here, but I figured I would share my short checklist for choosing a casino site. After getting burned once or twice I learned to read the small print first.
Licence comes first for me: see which authority is listed in the footer, because some sites quietly block certain regions. Then payments: crypto is a plus but not a must, and there should be no weird fees on cashouts.
Never judge a site by the bonus alone. Anything above 40x rollover is a red flag for me, and the bonus usually expires in a week or two. A decent independent write-up with the current terms is worth a read here [url=https://www.intensedebate.com/people/id2sxzekp6]Smash Casino[/url] so you know what you are signing up for.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Support matters too: a real human reply beats a bot loop.
Anyway, that is my routine. Set a budget and stick to it.
punter_xpka
October 10, 2026, at 8:29 pmBeen reading this board for a while, but I figured I would share my short checklist for choosing a casino site. After trying maybe a dozen sites I stopped trusting the big banners.
Licence comes first for me: see which authority is listed in the footer, and if your country is on the allowed list. After that I look at banking: crypto is a plus but not a must, and cashout times should be listed up front.
Never judge a site by the bonus alone. Anything above 40x rollover is a red flag for me, and some games count less towards it. A good recent review that covers all of this is worth a read here [url=https://www.tumblr.com/soldkryptohub/829748255475859456]Trino Casino[/url] so you know what you are signing up for.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Test the live chat before depositing: if they answer in a couple of minutes that is a good sign.
Hope this helps someone. Only play with money you can afford to lose.
MathewCycle
October 10, 2026, at 8:36 pmМарки новосибирск закладки Кировград купить закладку эйфоретик Мефедрон
Москва Дмитровский купить Мефедрон в мелких камнях/муке Купить Кокаин, Мефедрон, Марихуану, МДМА Светлогорск купить закладку Ecstasy
Дальнереченск купить Скорость a-pvp Спасск-Дальний купить закладку Cocaine Premium HQ – печать Dolphin
nomiumkem
October 10, 2026, at 8:37 pmразработка приложений для android цены
verifikaciyakoda.space
разработка блокчейна
lucky_wesl
October 10, 2026, at 8:47 pmBeen reading this board for a while, thought I would drop what I look at before signing up anywhere. After a few bad experiences I stopped trusting the big banners.
First thing is the licence: find the licence number and look it up, and whether they actually accept players from your country. After that I look at banking: crypto is a plus but not a must, and there should be no weird fees on cashouts.
Never judge a site by the bonus alone. Read the wagering and the max bet rule, and the bonus usually expires in a week or two. A useful overview with bonus rules, app info and payment methods is here [url=https://forum.hcpforum.com/read-blog/28884]Lottoland[/url] so you know what you are signing up for.
I play almost only on my phone, and a good site loads fast and does not log you out every five minutes. Ask support one simple question first: a real human reply beats a bot loop.
Anyway, that is my routine. Treat it as entertainment, not income.
MathewCycle
October 10, 2026, at 8:58 pmкупить наркотики Инта Новопавловск купить Психоделики
Москва Щукино купить закладку Марихуана [Hillary Clinton Kush] Купить Кокаин, Мефедрон, Марихуану, МДМА Закладки марки в Полярном
Купить Кокаин в Юхнов-1 Грайворон купить закладку Чистейший Метадон
lucky_vvsl
October 10, 2026, at 9:01 pmBeen reading this board for a while, so here is how I pick an online casino these days. After getting burned once or twice I learned to read the small print first.
I always start with licensing: find the licence number and look it up, and whether they actually accept players from your country. Then payments: I want at least one fast e-wallet option, and cashout times should be listed up front.
The welcome offer is where most people get caught. Read the wagering and the max bet rule, and some games count less towards it. A good recent review that covers all of this is here [url=https://tudomuaban.com/chi-tiet-rao-vat/3047951/lottoland-finland—real-money-gaming-in-2026-a-practical-player-guide.html]Lottoland[/url] so you know what you are signing up for.
I play almost only on my phone, and if there is an app I make sure it comes from the official page. Test the live chat before depositing: if they answer in a couple of minutes that is a good sign.
Hope this helps someone. Treat it as entertainment, not income.
DavidNef
October 10, 2026, at 9:09 pmbet at home 843 hopa casino free spins
karamba free spins free casino slots Igraj Book of Ra na spletu poker online live
book of ra 1xbet no deposit bonus casino malta
MathewCycle
October 10, 2026, at 9:17 pmМамоново купить закладку MDMA Pills – ORANGE Владикавказ купить Марихуана [Hillary Clinton Kush]
Билибино купить закладку Порох 999 (HQ) Афган Купить Кокаин, Мефедрон, Марихуану, МДМА Куртамыш купить Метамфетамин
Лебедянь купить Ecstasy: Red Monkey 250mg Артёмовск купить Марки LSD
nomiumkem
October 10, 2026, at 9:26 pmкак создать кошелек для криптовалюты
verifikaciyakoda.space
devops услуги стоимость
YOULANDAdal
October 10, 2026, at 9:46 pmhttps://intercom.help/bonuscode/en-us/articles/17151154-1xbit-casino-promo-code-gambia-2026-btc777-bonus-7-btc
GlennUPset
October 10, 2026, at 10:02 pmНужен юрист? [url=https://www.pravovik24.ru/r/mo/dzerzhinskiy/]юристы круглосуточно в Дзержинском[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
Josephamips
October 10, 2026, at 10:03 pmbest casino to play online hit casino kranjska gora Najboljsa spletna igralnica v Sloveniji, ki jo priporocamo golden star casino
casino luck no deposit bonus code best casino pages online
nomiumrukem
October 10, 2026, at 10:14 pmux ui заказать
verifikaciyakoda.space
разработка api цена
MADGEpeR
October 10, 2026, at 10:15 pmhttps://intercom.help/bonuscode/en-hk/articles/17133452-melbet-welcome-bonus-code-casino-bangladesh-2026-mel200big-bonus-12-000-bdt
Keithbar
October 10, 2026, at 10:16 pmhttps://intercom.help/bonuscode/en-za/articles/17028295-1xbet-aktivace-bonusu-v-cesku-2027-joinbet55
MAUDmeert
October 10, 2026, at 10:16 pmhttps://intercom.help/bonuscode/en-in/articles/17182955-1xbit-liberia-promo-code-activation-2026-btc777-7-btc-bonus
KENDAReiny
October 10, 2026, at 10:16 pmhttps://intercom.help/bonuscode/en-ca/articles/17186545-1xslots-india-promo-code-2026-btc777-450-30-free-spins
Josephamips
October 10, 2026, at 10:24 pmblack chip poker no deposit bonus kako igrati blackjack Avtomati v casinu vegas casino online
poker online live casino hit online
SHANEAvoip
October 10, 2026, at 10:28 pmhttps://intercom.help/bonuscode/en-nz/articles/17025946-бЂ™бЂјбЂ”-бЂ™бЂ¬бЂ”бЂбЂЇбЂ„-бЂ„бЂ¶бЂЎбЂђбЂЅбЂЂ-1xbet-бЂЎбЂЂбЂ±бЂ¬бЂ„-бЂћбЂ…-бЂЂбЂЇбЂ’-2026-joinbet55
Josephamips
October 10, 2026, at 10:41 pmcasino live ljubljana blackjack tips and tricks Ruleta v spletnem casinu What online casino has free bonus without deposit
casino simulation game sunny scoops free spins
DavidNef
October 10, 2026, at 11:08 pmbook of ra two symbols free play igre casino knjige
zeus casino game jackpot capital no deposit bonus codes Casino bonusi za Slovence mobilni casino slovenija
book of dead free spins saucify casinos no deposit bonus
DavidNef
October 10, 2026, at 11:20 pmcasino online free spins book of ra deluxe ratio
book of ra deluxe riverbelle online casino login Casino na spletu energy casino free spins no deposit
bwin casino live chat besplatne casino igre merkur germany
nomiumrukem
October 10, 2026, at 11:25 pmразработка web приложений заказать приложение
verifikaciyakoda.space
создать блокчейн проект
MathewCycle
October 10, 2026, at 11:37 pmМценск купить Ecstasy – Homer / Bart Воронежская область купить закладку АК-47 – Бошки Шишки
Лебедянь купить закладку MDMA Pills – BLUE Купить Кокаин, Мефедрон, Марихуану, МДМА Кореновск купить MDMA Pills
Челябинская область купить Марихуана [Hillary Clinton Kush] Бентота купить закладку План (АФГАНКА)
DavidNef
October 11, 2026, at 12:11 amcasino admiral princess bevkov trg nova gorica admiral palatium casino split
book of ra 6 deluxe demo bet365 it app Slovenski spletni casinoji brezplaДЌne slovenia igre na avtomatih
kako funkcionira online casino admiral casino group
MathewCycle
October 11, 2026, at 12:17 amКяхта купить закладку Чистейший кокаин 98% Нариманов купить бошки
Анталия купить закладку бошки Купить Кокаин, Мефедрон, Марихуану, МДМА Закладки марки в Дальнегорске
Белгородская область купить закладку Ecstasy: Red Bull 200 mg Тарко-Сале купить Шишки White Widow
Adrianroove
October 11, 2026, at 12:32 amPicked up a couple of new ideas here that I can actually try out, and after my visit to warehousewave I have even more notes saved, this is the kind of resource that pays you back for the time you spend on it which is rare to come across in this corner of the web.
nomiumkem
October 11, 2026, at 12:46 amинтерактивный стенд
verifikaciyakoda.space
разработка блокчейна
Josephamips
October 11, 2026, at 12:54 amlive casino blackjack cosmo casino no deposit bonus Spletna igralnica s placilom prek Paysafecard casino igre gratis
casino portoroЕѕ bizi casino bonus hunt
Josephamips
October 11, 2026, at 1:15 amЕЎtetje kart blackjack fortuna casino online Igralnica na spletu 5 euro no deposit
happy hour free spins online casino dovoljeni v sloveniji
Josephamips
October 11, 2026, at 1:32 amcasino joker maribor platinum reels no deposit bonus Igranje Za Pravi Denar book of ra fixed
royalace casino free spins codes aussie online casino
DavidNef
October 11, 2026, at 2:11 amcasino rewards vip ruleta gratis online casino
hit casino perla online casino game bombay Zacetni bonus v igralnici online casino real money
bgo free spins casino igre slot free
DavidNef
October 11, 2026, at 2:23 am21 blackjack online bet 365 alternativ link
casino bonus free spins online casino marketing strategy Spletni casino Paysafecard hit hotel casino kranjska gora
live casino ljubkjana poker avtomati free
MathewCycle
October 11, 2026, at 2:36 amМосква Марьина роща купить Марки LSD 170мкг купить клад в Жердевка
Болгария купить Euro HQ Hash (ЧЕРНЫЙ) Купить Кокаин, Марихуану, Бошки, Мефедрон Сусуман купить VHQ GanBang Cocaine 98% Peru
Алания купить бошки Рославль купить закладку Гашиш [Euro Cube]
MathewCycle
October 11, 2026, at 2:58 amКондопога купить закладку План (АФГАНКА) Курганинск купить закладку MDPV
Богородицк купить Мефедрон [Кристаллы] Купить Кокаин, Марихуану, Бошки, Мефедрон Словакия купить закладку Метадон (HQ) Германия
Колпашево купить Cocaine MQ Ненецкий АО купить Кристаллы соль
GlennUPset
October 11, 2026, at 3:07 amНужен юрист? [url=https://www.pravovik24.ru/r/mo/dzerzhinskiy/]бесплатная консультация адвоката по телефону круглосуточно в Дзержинском[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
DavidNef
October 11, 2026, at 3:14 amcasino igre kako igrati na pametan nacin no deposit bonus 2026 februar
casino admiral lev Has anyone won big on online gambling Spletni igralni avtomati bar bar casino online
book of ra real money counting cards blackjack
MathewCycle
October 11, 2026, at 3:16 amНовоаннинский купить закладку Ecstasy: Red Bull 200 mg Ціна перекриття теріва
Москва Печатники купить закладку HQ Гашиш Купить Кокаин, Мефедрон, Марихуану, МДМА Снежногорск купить закладку Ecstasy: Red Bull 200 mg
Москва Люблино купить Cocaine MQ Купить Метод Можга
Josephamips
October 11, 2026, at 3:46 amonline casino to make money hit casino kranjska gora korona Igrajte avtomate brezplacno nagradne igre casino
What is the 5 spin rule slot strategy vbet live casino
Josephamips
October 11, 2026, at 4:06 amfanduel live casino 7 euro gratis casino Najboljsi Bonusi V Sloveniji codice bonus bet365
casino koper slovenia pragmatic play live casino
Josephamips
October 11, 2026, at 4:24 ambet365 app android pkr poker free no deposit Ocena igralnice Hell Spin no deposit bonus casino 20 €
list of all online casinos bwin poker no deposit bonus
spieler_nsPr
October 11, 2026, at 5:05 amLese hier schon eine Weile mit, also teile ich mal, wie ich ein Online Casino auswaehle. Nach gut einem Dutzend getesteter Seiten verlasse ich mich nicht mehr auf Werbung.
Als Erstes pruefe ich die Lizenz: wer reguliert die Seite, und ob Spieler aus dem eigenen Land ueberhaupt zugelassen sind. Als Naechstes das Banking: Karte, E-Wallets und Ueberweisung sollten dabei sein, und die Bearbeitungszeiten sollten offen genannt sein.
Beim Willkommensbonus fallen die meisten rein. Umsatzbedingungen und Maximaleinsatz genau lesen, und der Bonus verfaellt meist nach ein bis zwei Wochen. Einen brauchbaren Testbericht mit allen aktuellen Infos gibt es hier [url=https://climaxconnection.com/forum/26/general-topics/9446/what-to-check-before-joining-fortuna-casino-in-2026]fortuna casino[/url] bevor man etwas einzahlt.
Ich spiele fast nur noch am Handy, deshalb schaue ich, wie die Lobby auf dem kleinen Bildschirm funktioniert. Den Live Chat teste ich vor der Einzahlung: langsame Standardantworten bedeuten spaeter oft Aerger.
Das war es im Grunde. Spielen ist Unterhaltung, kein Einkommen.
DavidNef
October 11, 2026, at 5:14 amnovomatic online casino most popular online casino
casino kranjska gora kleiderordnung casino igre 777 Paysafecard casino What is the best online casino app
bet365 registration bonus 50 euro no deposit bonus casino
DavidNef
October 11, 2026, at 5:27 amfree slot games for android phones casino igre besplatne
grosvenor casino online energy casino free spins no deposit Kako dobiti bonus dobrodoslice v spletnem casinu casino igre aparati besplatne
ruby slots casino no deposit bonus codes online casino 5€
MathewCycle
October 11, 2026, at 5:35 amзакладки наркотиков в Кимры Дмитровск купить марихуану
Эйфория казань Купить Кокаин, Марихуану, Бошки, Мефедрон Льгов купить LSD-25 (HQ) 250мкг
Купить закладки шишки ак47 в Сычевке Сунжа купить закладку Cocaine Premium: Peru
MathewCycle
October 11, 2026, at 5:57 amТында купить шишки Купить Скорость a-PVP в
Свободный купить закладку Кристаллы мёда Купить Кокаин, Марихуану, Бошки, Мефедрон Светлоград купить METHADONE
Жиросжигатель ЭКА: состав, противопоказания, побочные эффекты ЗАВИСИМОСТЬ ОТ КЛОНАЗЕПАМА ИЛИ БОЛЕЗНЬ
MathewCycle
October 11, 2026, at 6:16 amtelegram купить амфетамин Агрыз купить Ecstasy: Red Stars 280 mg
Никольское купить Марихуана [Outstanding Kush] Купить Марихуану, Кокаин, Бошки, Гашиш Купить наркотики в нижнем новгороде
Купить закладки спайс россыпь в Шацке Фролово купить LSD-25 (HQ) 170мкг
DavidNef
October 11, 2026, at 6:19 amcasino admiral ruggell kazino igre demo
online casino free play 2000 free casino games imtinanebadia.com book of ra jackpot
casino igre besplatno avtomati 888 live casino login
nomiumkem
October 11, 2026, at 6:21 amux дизайн сайта цена
dvenadcatslov.website
заказать блокчейн разработку
Josephamips
October 11, 2026, at 6:37 am10 euro free casino spletna igralnica brez depozita Igralnica na spletu free spin to cash out
free online slots no download What is the best online casino app
Josephamips
October 11, 2026, at 6:57 amsuper casino no deposit bonus code poker no deposit bonus Spletne igralniske igre za vsak okus spinsvilla casino no deposit bonus
no deposit bonus casino slovenia ruleta gratis online casino
nomiumrukem
October 11, 2026, at 7:08 amсоздание криптовалюты под ключ
dvenadcatslov.website
услуги фронтенд разработчика
JeffreyGex
October 11, 2026, at 7:15 amcasino brez depozita slovenija live casino black jack slot games free casino igt casino slot igre besplatne
What is the €20 method at a casino free spins no deposit 2026
nomiumkem
October 11, 2026, at 7:58 amразработка api для бизнеса
dvenadcatslov.website
как создать криптообменник с нуля
RobertGop
October 11, 2026, at 8:19 am888 live casino login house of fun 100 free spins
zodiac casino forum slovenija 6black casino no deposit bonus codes Igralni avtomati eur pokerstars eu
riging bull casino no deposit bonus code slovenia all free slot games
RobertGop
October 11, 2026, at 8:31 ambet 365 alternativ link sign up casino free spins
casino s bonus free spins no deposit king casino bonus Casino z Paysafecard pologom free spins casino bonus
getminted free slots games game of thrones slots free download
AndrewRibra
October 11, 2026, at 8:35 amТрогир купить Марихуана [KILLER KUSH] Калининск купить гидропонику
Темрюк купить Амфетамин (фен) Купить Марихуану, Кокаин, Бошки, Гашиш Узловая купить закладку Ecstasy: Yellow Homer 200mg
Москва Силино купить Лирика 300мг (Прегабалин) Микунь купить Метадон VHQ
AndrewRibra
October 11, 2026, at 8:57 amБузулук купить закладку LSD-25 (HQ) 250мкг Лесосибирск купить Ecstasy Rolls Royce
Кипр купить VHQ GanBang Cocaine 98% Peru Купить Кокаин, Мефедрон, Марихуану, МДМА Звенигород купить Ecstasy: Red Monkey 250mg
Каргополь купить VHQ Cocaine 98,8% Ecuador Калязин купить закладку VHQ Cocaine 98% Colombia
highroll_tuKi
October 11, 2026, at 9:08 amLong time lurker here, thought I would drop how I pick an online casino these days. After getting burned once or twice I stopped going by ads alone.
Licence comes first for me: check who regulates the site, because some sites quietly block certain regions. Then payments: I want at least one fast e-wallet option, and cashout times should be listed up front.
Bonuses are the tricky part. Anything above 40x rollover is a red flag for me, and live tables often do not count at all. A useful overview with bonus rules, app info and payment methods is worth a read here [url=https://gitea.com/devongt2366cf8]just casino app[/url] so you know what you are signing up for.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Test the live chat before depositing: a real human reply beats a bot loop.
That is about it. Treat it as entertainment, not income.
spinner_djmr
October 11, 2026, at 9:08 amMostly a reader, rarely post, but I figured I would share my short checklist for choosing a casino site. After trying maybe a dozen sites I stopped going by ads alone.
Licence comes first for me: see which authority is listed in the footer, and if your country is on the allowed list. Then payments: crypto is a plus but not a must, and the withdrawal limits need to be written clearly.
Never judge a site by the bonus alone. Read the wagering and the max bet rule, and the bonus usually expires in a week or two. A useful overview with bonus rules, app info and payment methods is here [url=https://cryptoplaypicks.activeboard.com/t73296093/gambajack-casino-real-money-gaming-in-2026-a-practical-playe/]learn more[/url] before you deposit anything.
Most of my sessions are on mobile, so I check how the lobby works on a small screen. Support matters too: slow or scripted answers usually mean trouble later.
That is about it. Set a budget and stick to it.
nomiumrukem
October 11, 2026, at 9:08 amразработка блокчейна
dvenadcatslov.website
разработка telegram mini app на заказ
punter_upka
October 11, 2026, at 9:09 amLong time lurker here, so here is how I pick an online casino these days. After a few bad experiences I stopped trusting the big banners.
Licence comes first for me: check who regulates the site, and if your country is on the allowed list. Next come deposits and withdrawals: card, e-wallets and bank transfer should all be there, and cashout times should be listed up front.
Bonuses are the tricky part. Anything above 40x rollover is a red flag for me, and some games count less towards it. A good recent review that covers all of this can be found here [url=https://www.efunda.com/members/people/show_people.cfm?Usr=martinez222253]learn more[/url] before you deposit anything.
I play almost only on my phone, so I check how the lobby works on a small screen. Support matters too: slow or scripted answers usually mean trouble later.
Hope this helps someone. Set a budget and stick to it.
AndrewRibra
October 11, 2026, at 9:15 amЗаринск купить закладку Альфа купить клад в Сертолово
Кировград купить закладку MDMA Pills – ORANGE Купить Марихуану, Кокаин, Бошки, Гашиш Инсар купить закладку Кристаллы соль
Александров купить закладку Гидропоника Afgan Kush Бобров купить закладку Амфетамин (фен)
RobertGop
October 11, 2026, at 9:22 amcasino igre za pravi denar brez depozita online casino slovenija forum
casino igre za pravi denar brez depozita online casino free play Spletni casino za Slovenijo casino brez depozita brez pogojev
casino spletne igre bonus vegas slots online casino
JeffreyGex
October 11, 2026, at 9:29 amtrusted online casino zodiac casino slovenija futuriti casino no deposit bonus codes 2026 slot game free igt
kazino igre rulet casino 1 euro deposit
lucky_bxsl
October 11, 2026, at 9:49 amBeen reading this board for a while, but I figured I would share how I pick an online casino these days. After a few bad experiences I learned to read the small print first.
I always start with licensing: check who regulates the site, and if your country is on the allowed list. Then payments: card, e-wallets and bank transfer should all be there, and there should be no weird fees on cashouts.
Bonuses are the tricky part. Read the wagering and the max bet rule, and some games count less towards it. A decent independent write-up with the current terms is here [url=https://tdmromania.ro/member.php?action=profile&uid=21942]vai al sito[/url] so you know what you are signing up for.
On mobile I mostly use the browser version, and if there is an app I make sure it comes from the official page. Test the live chat before depositing: a real human reply beats a bot loop.
Hope this helps someone. Set a budget and stick to it.
JeffreyGex
October 11, 2026, at 9:50 amcasino free games online casino admiral kozina kako dobiti na book of ra online casino no deposit bonus
igre casino poker bwin live casino app
JasperHig
October 11, 2026, at 9:52 amHello!
If You Are Losing Focus: The Environmental Changes To Make Now
Why Being Honest About Weaknesses Makes You Stronger
Insider Secrets: How Retailers Arrange Stores To Make You Buy More
You can study here – https://promomi.ru/
Good luck!
JeffreyGex
October 11, 2026, at 10:07 ambasic strategy blackjack casino not on gamstop no deposit bonus hotel casino resort admiral best online casino 2026
What is the 5 spin rule slot strategy besplatne casino igre gaminator
jackpot_deml
October 11, 2026, at 10:27 amMostly a reader, rarely post, thought I would drop my short checklist for choosing a casino site. After trying maybe a dozen sites I stopped going by ads alone.
First thing is the licence: see which authority is listed in the footer, and if your country is on the allowed list. After that I look at banking: card, e-wallets and bank transfer should all be there, and cashout times should be listed up front.
Never judge a site by the bonus alone. Read the wagering and the max bet rule, and the bonus usually expires in a week or two. A decent independent write-up with the current terms can be found here [url=https://uberant.com/article/2183363-superbet-casino-online-spelen-in-2026-een-praktische-spelersgids]Superbet[/url] and it saved me some time.
I play almost only on my phone, and if there is an app I make sure it comes from the official page. Test the live chat before depositing: a real human reply beats a bot loop.
That is about it. Treat it as entertainment, not income.
nomiumkem
October 11, 2026, at 10:32 amdevops услуги стоимость
dvenadcatslov.website
разработка web 3 приложений
EdwardAlots
October 11, 2026, at 11:00 amНужен юрист? [url=https://www.pravovik24.ru/r/mo/egorevsk/]бесплатная юридическая консультация юриста по телефону в Егорьевске[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
spieler_cqPr
October 11, 2026, at 11:14 amPoste selten, lese aber viel, also teile ich mal, wie ich ein Online Casino auswaehle. Nachdem ich ein paar Mal Pech hatte lese ich zuerst das Kleingedruckte.
Bei mir kommt die Lizenz an erster Stelle: wer reguliert die Seite, weil manche Seiten bestimmte Laender still sperren. Dann die Zahlungen: Karte, E-Wallets und Ueberweisung sollten dabei sein, und die Auszahlungslimits muessen klar drinstehen.
Beim Willkommensbonus fallen die meisten rein. 35x oder 40x Umsatz ist normal, und manche Spiele zaehlen weniger. Eine ehrliche Zusammenfassung zu Bonus, App und Auszahlung findet man hier [url=https://cryptoplaypicks894151.xobor.de/t44f1736275306-Fortuna-Casino-Online-Spiele-ein-praktischer-Ratgeber.html#msg6387094]Fortuna Casino[/url] bevor man etwas einzahlt.
Ich spiele fast nur noch am Handy, und eine gute Seite laedt schnell und loggt einen nicht staendig aus. Der Support zaehlt auch: langsame Standardantworten bedeuten spaeter oft Aerger.
So mache ich das jedenfalls. Budget festlegen und dabei bleiben.
RobertGop
October 11, 2026, at 11:23 amcasino not on gamstop no deposit bonus casino grand bay no deposit bonus
kdaj je Еѕrebanje lota free spins symbol Paysafecard how to party casino bonus code no deposit
blackjack game online konung casino no deposit bonus code
AndrewRibra
October 11, 2026, at 11:34 amГдов купить MQ Cocaine Mexico Туринск купить эйфоретик MDMA
Купить марихуана Поворино Купить Марихуану, Кокаин, Бошки, Гашиш Минусинск купить закладку Гашиш [Soft Hash]
Шумерля купить План (АФГАНКА) Кирс купить эйфоретик MDMA
RobertGop
October 11, 2026, at 11:36 ambesplatne casino igre bonus tri piramide book of ra online game
silver oak casino Do gaming apps really pay money Ruleta jackpot lucky block
best online casino in world casdep no deposit bonus
spieler_enPr
October 11, 2026, at 11:49 amBin schon laenger stiller Mitleser, daher hier meine Erfahrungen, worauf ich vor der Anmeldung achte. Nach gut einem Dutzend getesteter Seiten lese ich zuerst das Kleingedruckte.
Als Erstes pruefe ich die Lizenz: Lizenznummer suchen und nachpruefen, weil manche Seiten bestimmte Laender still sperren. Als Naechstes das Banking: Krypto ist nett, aber kein Muss, und die Bearbeitungszeiten sollten offen genannt sein.
Beim Willkommensbonus fallen die meisten rein. 35x oder 40x Umsatz ist normal, und manche Spiele zaehlen weniger. Eine ehrliche Zusammenfassung zu Bonus, App und Auszahlung kann man hier lesen [url=https://vocal.media/authors/bingoal-switzerland]bonus at Bingoal[/url] das hat mir einiges an Zeit gespart.
Die meisten Runden spiele ich mobil, und eine gute Seite laedt schnell und loggt einen nicht staendig aus. Der Support zaehlt auch: langsame Standardantworten bedeuten spaeter oft Aerger.
Vielleicht hilft es ja jemandem. Spielen ist Unterhaltung, kein Einkommen.
AndrewRibra
October 11, 2026, at 11:56 amГудермес купить Гашиш [Euro Cube] Каргополь купить закладку Mephedrone (4mmc, мяу)
Фролово купить закладку шишки Купить Кокаин, Мефедрон, Марихуану, МДМА купить наркотики Рыбное
Балашиха купить закладку План (АФГАНКА) Ханты-Мансийский АО — Югра купить MDMA Pills – ORANGE
spieler_lwPr
October 11, 2026, at 12:06 pmLese hier schon eine Weile mit, also teile ich mal, was mir bei der Wahl eines Casinos wichtig ist. Nach ein paar schlechten Erfahrungen lese ich zuerst das Kleingedruckte.
Als Erstes pruefe ich die Lizenz: Lizenznummer suchen und nachpruefen, und ob Deutschland, Oesterreich oder die Schweiz erlaubt sind. Danach Ein- und Auszahlungen: mindestens ein schnelles E-Wallet will ich haben, und die Bearbeitungszeiten sollten offen genannt sein.
Niemals eine Seite nur nach dem Bonus bewerten. 35x oder 40x Umsatz ist normal, und manche Spiele zaehlen weniger. Einen guten aktuellen Ueberblick mit Bonusbedingungen, App und Zahlungsmethoden findet man hier [url=https://www.efunda.com/members/people/show_people.cfm?Usr=martinez68e424]learn more[/url] das hat mir einiges an Zeit gespart.
Ich spiele fast nur noch am Handy, und eine gute Seite laedt schnell und loggt einen nicht staendig aus. Einfach mal eine kurze Frage an den Support stellen: kommt die Antwort in ein paar Minuten, ist das ein gutes Zeichen.
Vielleicht hilft es ja jemandem. Nur mit Geld spielen, das man verlieren kann.
AndrewRibra
October 11, 2026, at 12:14 pmПущино купить Мефедрон [мелкие камни/мука] HQ Суворов купить Чистейший Метадон
белье цвета кокаина Купить Кокаин, Мефедрон, Марихуану, МДМА Нижний Новгород купить закладку LSD-25 (HQ) 250мкг
Ялуторовск купить закладку MDMA Crystal [Import] Арск купить METHADONE
JeffreyGex
October 11, 2026, at 12:23 pmthe online casino how to free spin on gods What games can I win real money with no-deposit bwin live poker
live casino online real money kazino igre za denar
RobertGop
October 11, 2026, at 12:27 pmlevel up casino no deposit bonus betting
eu casino bonus casino daily bet get free spin party casino Brezplacni igralni avtomati blackjack online casino
bet365 deposit bonus 1win bonus casino
JeffreyGex
October 11, 2026, at 12:44 pmkako igrati igre v casino online casino 5€ club sa casino no deposit bonus codes bitstarz register free spins
kako odigrat bonuse v casino online anubis free spins
JeffreyGex
October 11, 2026, at 1:02 pmspletna igralnica casino si jackpot city casino bonus live casino uk real money bitcoin casino slovenija
bet 365 portoroЕѕ plama pur free game book of ra
RobertGop
October 11, 2026, at 2:28 pmWhat is a good online casino casino crypto bonus no deposit
roulette live online casino bet365 how to get bonus Casino slot igre the best online casino acept paysafe card
kazino igre kleopatra bonus koda bet365
AndrewRibra
October 11, 2026, at 2:34 pmКолпашево купить закладку MDPV марихуана канабис
Москва Внуково купить Метадон, чистота 99% Купить Кокаин, Марихуану, Бошки, Мефедрон Братск купить Ecstasy: Yellow Stars 350 mg
Омск купить LSD 220 мг Купить Трамадол Магас
RobertGop
October 11, 2026, at 2:40 pmmiami casino online What online casino has free bonus without deposit
book games casino fortuin casino no deposit bonus codes Slovenska spletna igralnica ruby slots casino no deposit bonus codes
casino igre lucky lady 6 malina casino bonus
AndrewRibra
October 11, 2026, at 2:55 pmСеверодвинск купить Гашиш [Euro Cube] Светлоград купить Cocaine Premium HQ – печать Dolphin
Бодайбо купить Amphetamine Купить Марихуану, Кокаин, Бошки, Гашиш Пестово купить Cocaine Premium: Peru
Куйбышев купить Ecstasy: Red Stars 280 mg Новодвинск купить Амфетамин (фен)
AndrewRibra
October 11, 2026, at 3:14 pmСельцо купить Ecstasy Rolls Royce КрасноперекопскОспаривается купить закладку LSD 220 мг
Одинцово купить Шишки White Widow Купить Марихуану, Кокаин, Бошки, Гашиш Москва Митино купить закладку Психоделики
Закладки лирика в Белёве Лесосибирск купить MDMA Pills – ORANGE
JeffreyGex
October 11, 2026, at 3:16 pmblackjack strategy card raging bull bonus codes free spins online casino game casino igre slot machine
zamfir casino slovenia bet365 app android
RobertGop
October 11, 2026, at 3:32 pmcasino 365 online mr green free spins
online casino slots 10 euro bonus brez depozita casino Hell Spin casino za Slovence casino bled kristina
casino in slovenia the best online casino
JeffreyGex
October 11, 2026, at 3:36 pmbitcoin live casino Which gambling sites give free money casino bonus brez depozita estonija 5 euro bonus brez depozita casino
jambo casino online captain jack casino free 300
JeffreyGex
October 11, 2026, at 3:54 pmcasino casino no deposit bonus code perla casino slovenia email casino slots free spins no deposit bonus casino switzerland real money
joo casino bonus codes new casino no deposit bonus 2026
nomiumrukem
October 11, 2026, at 4:05 pmразработка telegram mini app под ключ
god-spustya.space
разработка криптокошелька
KyleCok
October 11, 2026, at 4:52 pmA piece that was confident enough to leave some questions open rather than forcing closure, and a look at oceanoutfitters continued that intellectual honesty, content that admits the limits of its scope is more trustworthy than content that pretends to total understanding and this site has the right calibration on certainty consistently.
nomiumrukem
October 11, 2026, at 4:55 pmweb3 разработчики
god-spustya.space
разработка криптобиржи
EdwardAlots
October 11, 2026, at 5:07 pmНужен юрист? [url=https://www.pravovik24.ru/r/mo/egorevsk/]спросить адвоката онлайн в Егорьевске[/url] – отличная возможность получить помощь опытных правозащитников в любой области права: семейные споры, долги и кредиты, недвижимость, трудовые конфликты, защита прав потребителей и многое другое. Задайте вопрос юристу онлайн или обратитесь по телефону горячей линии из любого региона России. Консультация доступна круглосуточно и без регистрации.
SteveSoump
October 11, 2026, at 5:15 pmhttps://intercom.help/bonuscode/en-us/articles/17152161-code-bonus-de-pari-crypto-1xbit-en-2026-gabon-btc777-7-btc
NGUYETTus
October 11, 2026, at 5:15 pmhttps://intercom.help/bonuscode/en-us/articles/17150435-codigo-promocional-1xbit-2026-em-cabo-verde-btc777-7-btc
ELIZBETHFag
October 11, 2026, at 5:16 pmhttps://blender.community/codefreebet271/
ELMIRAKEYMN
October 11, 2026, at 5:17 pmhttps://slides.com/usebestcode27
RobertGop
October 11, 2026, at 5:31 pmmost trusted online casino in slovenia online casino 5€
bet365 casino alternative link book of ra deluxe 10 demo Najbolj priljubljeni igralni avtomati na spletu v Sloveniji bet365 poker app not working slovenia
hit casinos kranjska gora bounuse casino games online
nomiumkem
October 11, 2026, at 5:43 pmобменник криптовалют под ключ
god-spustya.space
услуги devops
AndrewRibra
October 11, 2026, at 5:55 pmКамбарка купить Гашиш [LV] Приморск купить закладку гидропонику
Шенкурск купить Amphetamine Купить Кокаин, Марихуану, Бошки, Мефедрон мефедрон героин
Пензенская область купить Ecstasy: Yellow Homer 200mg Чкаловск купить закладку VHQ Cocaine 98,8% Ecuador
JeffreyGex
October 11, 2026, at 6:07 pmwilliamhill casino live ЕЎportne stave online casino flamantis casino no deposit free spins 2026 casino bonus codes 2026 no deposit
book of oz slot free slot game free casino
AndrewRibra
October 11, 2026, at 6:13 pmНовомосковск купить закладку MDMA Pills Купить Скорость a-PVP в Зея
Пролечка в воде Купить Кокаин, Марихуану, Бошки, Мефедрон Москва ЮЗАО купить закладку MDMA Pills – BLUE
Закладки скорость a-PVP в Уфе Штрбске Плесо купить закладку Мефедрон купить закладку Лучший эйфоретик
JeffreyGex
October 11, 2026, at 6:28 pmbest games to play at casino hit spletna igralnica spletne casino igre za pravi denar casino blackjack rules
casino table games casino igre free prašići
RobertGop
October 11, 2026, at 6:35 pmcasino classic 50 free spins casino games free slots download
slot games free play best casino to play online Casino igre na spletu live casino slovenia
casino bonus today free casino games on net
JeffreyGex
October 11, 2026, at 6:45 pmWhat online casino gives free spins blackjack kako se igra free spins bunos codes december william hill live casino
coin beach free spins korona casino hotel kranjska gora slovenia
nomiumkem
October 11, 2026, at 6:58 pmинтерактивный стенд
god-spustya.space
автоматический майнинг
nomiumkem
October 11, 2026, at 8:22 pmпроектирование веб приложений заказать приложение
god-spustya.space
разработка api заказать
AndrewRibra
October 11, 2026, at 8:31 pmАсино купить закладку Гашиш [LV] Белебей купить Afgan Kush
Наволоки купить Триптамины Купить Марихуану, Кокаин, Бошки, Гашиш Нягань купить Метадон, чистота 99%
Ираклион купить Лирика 300мг (Прегабалин) Москва Кунцево купить Ecstasy: Red Bull 200 mg
RobertGop
October 11, 2026, at 8:34 pmbwin live poker free slot games with bonus rounds
sign up casino bonus the best casino online for slovenia players Kje igrati casino slot igre za pravi denar bet win 365
best sign up casi casino igre eldorado
JasperHig
October 11, 2026, at 8:39 pmGood morning!
Build A Bulletproof Morning Routine That Guarantees Daily Success
Busted: The Biggest Myths About Productivity That Waste Your Time
The Science Of Emotion: How To Regulate Your Feelings And Avoid Burnout
Link to the website – https://promomi.ru/skript-prodazh-dlya-strahovaniya-gotovye-dialogi-shablony-vozrazhenij-i-chek-listy-kotorye-realno-rabotayut/
Success in life!
RobertGop
October 11, 2026, at 8:47 pmnew online casino blackjack casino rewards
blackjack demo first person besplatne casino igre na aparatima Ponudba casino bonusov Slovenija besplatne casino igre za igranje
river belle juegos de casino online joker poker free online
AndrewRibra
October 11, 2026, at 8:53 pmДуховщина купить закладку Триптамины Знаменск купить закладку Героин РОЗНИЦА (999 VHQ) Афганистан
Чайковский купить закладку Cтимуляторы Купить Марихуану, Кокаин, Бошки, Гашиш Шарм эль Шейх купить Лирика 300мг (Прегабалин)
Балашиха купить АК-47 – Бошки Шишки Благовещенск купить Психоделики
JeffreyGex
October 11, 2026, at 8:58 pmslotty vegas casino bet-at-home slovenija download bet365 poker bonus explanation casino slovenia online no deposit codes
sir jackpot casino no deposit bonus code casino free online video games
AndrewRibra
October 11, 2026, at 9:12 pmДереализация марихуана Закладки метадон в Юхнов-2
Ессентуки купить Мефедрон [Кристаллы] Купить Кокаин, Марихуану, Бошки, Мефедрон Олонец купить Триптамины
Вилюйск купить закладку LSD 220 mkg Невинномысск купить закладку Cocaine Premium HQ – печать Dolphin
JeffreyGex
October 11, 2026, at 9:20 pmblackjack do you show cards igre casino free book perla casino slovenia kontakt migliori casino ci sono in slovenia
bet365 bingo bonus code book of dead no deposit bonus 2026
JeffreyGex
October 11, 2026, at 9:37 pmbet 365 singup bonus hotel casino lipica slovenia free spins real money casino bonus buy
poker bet 365 slovenija springbok casino no deposit bonus codes
RobertGop
October 11, 2026, at 9:38 pmlucky red casino no deposit bonus codes 2026 best casino in slovenia
best sign up casi best online casinos 2026 Varen spletni casino v Sloveniji s slovenskim jezikom casino bled zetoni vrednost
minimum deposit 1 euro Which casino app gives free spins
AndrewRibra
October 11, 2026, at 11:30 pmСлюдянка купить закладку Чистейший Метадон Экстази заказать в самаре
Купить Винт Орлов Купить Кокаин, Мефедрон, Марихуану, МДМА Тайга купить Мефедрон (миф)
Камчатский край купить закладку DMT Межгорье купить закладку VHQ GanBang Cocaine 98% Peru
RobertGop
October 11, 2026, at 11:37 pmslot igre casino 40 euro no deposit bonus
mr green free spins online casino usa no deposit bonus Casino online v Sloveniji pompeii casino games for free
free spin casino cash out mastercard bingohall online casino
RobertGop
October 11, 2026, at 11:50 pmbrezplaДЌne casino free igre casino igre besplatno avtomati
magic red casino free spins casino live blackjack Casino bonusi bovegas no deposit bonus codes 2026
247 free poker casinoluck free spins no deposit
JeffreyGex
October 11, 2026, at 11:50 pmdownload free casino slot games for mobile phone sunny scoops free spins free spin to cash out 100 game of thrones free slots
free slovenia slot machine games online online casino sign up free spins
AndrewRibra
October 11, 2026, at 11:52 pmБийск купить закладку Ecstasy: Red Bull 200 mg Семилуки купить Кокаин HQ
Купить закладки шишки ак47 в Донецке Купить Кокаин, Мефедрон, Марихуану, МДМА Красный канареечник
Купить Героин Донецк Москва Перово купить закладку гашиш
AndrewRibra
October 12, 2026, at 12:11 amМука наркотики Сурск купить закладку VHQ Cocaine 98% Bolivia
Кстово купить Чистейший кокаин 98% Купить Марихуану, Кокаин, Бошки, Гашиш Петропавловск-Камчатский купить закладку Метадон (HQ) Германия
Купить без рецепта цикломед Вбив в покер румы
JeffreyGex
October 12, 2026, at 12:11 amcasino daily bet get free spin party casino paypal casino slovenia what casino games you can beat kazino igre brezplacno
casino bonus brez depozita latvija apollo slots casino no deposit bonus codes
JeffreyGex
October 12, 2026, at 12:29 amcasino slot free online casino 777 casino 1 euro deposit casino fruit games
how to play book of ra vulkan casino online
RobertGop
October 12, 2026, at 12:41 ampremier live casino no deposit bonus codes nj online casino
casino poker games game slot free spin Casino WinShark za Slovenijo bet 365 povezava ki deluje
22bet casino bonus triomphe casino no deposit bonus
nomiumrukem
October 12, 2026, at 1:50 amразработка криптобиржи
zapas-v-kasse.online
услуги по блокчейн технологиям
AndrewRibra
October 12, 2026, at 2:29 amВерхняя Пышма купить Гашиш [Soft Hash] Лебедянь купить закладку Ecstasy: Red Stars 280 mg
Невельск купить Марихуана [Hillary Clinton Kush] Купить Кокаин, Марихуану, Бошки, Мефедрон Каспийск купить закладку Cocaine Premium: Peru
Трамадол в Братске Ставрополь купить Альфа
nomiumrukem
October 12, 2026, at 2:38 amобменник криптовалют под ключ
zapas-v-kasse.online
создать криптообменник
RobertGop
October 12, 2026, at 2:40 amblackjack not 21 raging bull casino no deposit bonus codes
What sites give free spins no deposit casino v sloveniji Book of Ra online igre paysafecard izplacilo takoj casino
free welcome bonus no deposit 2026 Is Book of Ra a good slot
JeffreyGex
October 12, 2026, at 2:43 amgrand fortune casino no deposit bonus codes wild vegas casino no deposit bonus codes royal vegas online casino mobile casino midas no deposit bonus codes
grand kazino online 50 free spins no deposit casino
AndrewRibra
October 12, 2026, at 2:51 amСколько мускатных орехов надо съесть Междуреченск купить закладку Гидропоника Afgan Kush
Сельцо купить закладку Мефедрон [мелкие камни/мука] HQ Купить Кокаин, Марихуану, Бошки, Мефедрон Майрхофен купить закладку Euro HQ Hash (ЧЕРНЫЙ)
Москва Алексеевский купить марихуану фенилэтиламины которые я знал и любил mdma
RobertGop
October 12, 2026, at 2:53 am25 free spins no deposit bonus casino bled apartmaji ДЌateЕѕ
poker replay free 50 euro bonus brez depozita casino Casino avtomati na spletu igt online casino
paysafe za igre casino kako igrati rizk casino
JeffreyGex
October 12, 2026, at 3:04 ambet365 bonus joining code kako odpreti spletno kazino casino slovenia online no deposit codes free spins casino no deposit new codes 2026
bet365 bonus how does it work matched betting slovenia
AndrewRibra
October 12, 2026, at 3:09 amПервоуральск купить закладку LSD-25 (HQ) 250мкг Шали купить закладку Метадон (HQ) Германия
Чугунный ИЖИК Купить Кокаин, Марихуану, Бошки, Мефедрон Москва Очаково-Матвеевское купить закладку Кокаин HQ
Москва Рязанский купить закладку Euro HQ Hash (ЧЕРНЫЙ) Калтан купить закладку Гашиш [LV]
rosgvardiy_vlsn
October 12, 2026, at 3:19 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана объектов.
Эффективность охраны повышается за счет использования передовых технологий и квалифицированных сотрудников.
JeffreyGex
October 12, 2026, at 3:21 amjoo casino bonus codes igre online casino casino bonus app juicy stakes casino no deposit bonus
bet365 loyalty bonus rules spletne igre za denar
nomiumkem
October 12, 2026, at 3:28 amсколько стоит интеграция api
zapas-v-kasse.online
разработка мобильного приложения под android цена
RobertGop
October 12, 2026, at 3:44 amjackpot casino rewards blackjack basic strategy
casino admiral colosseum casino luck no deposit bonus code Igraj Book of Ra na spletu sunny scoops free spins
bet365 bonus terms all slots online casino
nomiumkem
October 12, 2026, at 4:42 amtelegram mini apps под ключ
zapas-v-kasse.online
разработка блокчейн решений
AndrewRibra
October 12, 2026, at 5:28 amИнсбрук купить закладку Гашиш [LV] Подпорожье купить закладку Кокаин MQ
Анталия купить закладку Ecstasy: Red Monkey 250mg Купить Кокаин, Марихуану, Бошки, Мефедрон Дубаи купить Afgan Kush
Ишим купить закладку Метадон (HQ) Германия Петровск-Забайкальский купить закладку VHQ Cocaine 98% Bolivia
JeffreyGex
October 12, 2026, at 5:34 amblackjack online casino game online real money bonus no deposit get no deposit bonus casino brezplaДЌne casino igre free games
50 € no deposit bonus casino funclub casino no deposit bonus codes
RobertGop
October 12, 2026, at 5:44 ambet online casino slovenia book of ra ЕЎorc
happy hour casino admiral besplatne casino igre joker slot Bizzo casino za slovenske igralce online casinos slovenia
slotastic casino no deposit bonus codes bet365 deposit bonus codes
AndrewRibra
October 12, 2026, at 5:50 amэкстази википедия Петухово купить закладку Гидропоника Afgan Kush
Медвежьегорск купить Ecstasy: Red Stars 280 mg Купить Кокаин, Марихуану, Бошки, Мефедрон Вихоревка купить Марки LSD
Анива купить Амфетамин Пермский край купить закладку VHQ GanBang Cocaine 98% Peru
JeffreyGex
October 12, 2026, at 5:55 amfree bonus no deposit casino live casino roulette casino bonus brez depozita slovenija playing casino online free
captain jack casino free 200 no deposit bonus casino 2026 germany
RobertGop
October 12, 2026, at 5:57 amslot game free igt vega live chat 888 casino
book of ra igra free slot games for my phone Bizzo casino za slovenske igralce jackpot na ptuju
free slots for fun play free slots new
nomiumrukem
October 12, 2026, at 6:07 amразработка чат ботов на заказ
zapas-v-kasse.online
devops услуги
AndrewRibra
October 12, 2026, at 6:09 amСокол купить LSD-25 в марках 250мк Тольятти купить закладку Героин ОПТ
Кашин купить Героин ОПТ Купить Кокаин, Марихуану, Бошки, Мефедрон Абдулино купить закладку Метадон (HQ) Германия
Севастополь купить закладку Ecstasy: UPS 280mg Якутия купить закладку Кокаин MQ
JeffreyGex
October 12, 2026, at 6:12 amraging bull casino no deposit bonus codes 2026 poker online live What is the most trusted online casino casino bled bizi
book of ra real money zar casinos no deposit bonus codes
RobertGop
October 12, 2026, at 6:48 amlive casino demo miami dice casino no deposit bonus codes
casino admiral kozina bizi free spins bunos codes december Casino na spletu Slovenija white lotus casino no deposit bonus
najboljЕЎe spletne casino igre za pravi denar club world casino no deposit bonus
JeffreyGex
October 12, 2026, at 8:25 ambest free gambling sites vegas play casino no deposit bonus code yukon gold casino free spins no deposit frank casino no deposit bonus
paysafe za igre casino multilotto casino no deposit bonus
AndrewRibra
October 12, 2026, at 8:28 amКрасный Сулин купить закладку Кристаллы мёда Москва Медведково Южное купить закладку Mephedrone (4mmc, мяу)
Шишки в Городище Купить Кокаин, Мефедрон, Марихуану, МДМА Демидов купить Гашиш [Euro Cube]
Марий Эл купить закладку MDMA Pills – RED Москва Лосиноостровский купить Ecstasy: Red Bull 200 mg
JeffreyGex
October 12, 2026, at 8:46 amno deposit bonus betting real money blackjack app vegascrestcasino free spins no deposit free chips online casinos
live 888 casino login prenocisce casino bled
RobertGop
October 12, 2026, at 8:49 amonline casino no deposit welcome bonus free royal poker
play ojo free spins no deposit blackjack free online Spletni casino za Slovenijo online casino ratings
how much do online casinos make casino video igre
AndrewRibra
October 12, 2026, at 8:50 amКак приготовить первентин Верещагино купить Метамфетамин
Москва Митино купить Купить опиаты: героин, метадон, лирика, хмурый, мёд Купить Кокаин, Мефедрон, Марихуану, МДМА Фокино купить закладку Мефедрон купить закладку Лучший эйфоретик
Щигры купить Гашиш [LV] Теберда купить Альфа
RobertGop
October 12, 2026, at 9:02 amcasino besplatne igre avtomati casino slovenia online casino
bet365 bonus 25 casino free games bombay Casino online za denar besplatne casino igre na aparatima
governor of poker 1 download full version free casinos in slovenia online
JeffreyGex
October 12, 2026, at 9:04 ambet 365 aplikacija za iso ki deluje slots free game casino free slot machine games without downloading or registration jetbull online casino
kazino igre besplatno where’s the gold aristocrat casino game
AndrewRibra
October 12, 2026, at 9:09 amХадыженск купить гашиш Петухово купить закладку MDMA Pills – BLUE
Купить Хмурый Куйбышев Купить Кокаин, Мефедрон, Марихуану, МДМА Чехия купить закладку Гашиш [Euro Cube]
Электроугли купить закладку Марихуана [Hillary Clinton Kush] Синдром отмены от курения: как пережить и не начать курить заново
rosgvardiy_ausn
October 12, 2026, at 9:17 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, росгвардия охрана объектов цена.
Для эффективной защиты используются современные технические средства и профессиональные кадры.
lvjpsaless
October 12, 2026, at 9:48 am[url=https://lovewallet001.officialblog.jp]louis vuitton 財布 スーパー コピー[/url] [url=https://louisvuittoncopycheap.xxxblog.jp]ルイ ヴィトン コピー 激安[/url] [url=https://buywalletlvsale.livedoor.blog]vuitton 財布 スーパー コピー[/url] ヴィトン 長 財布 スーパー コピー ルイ ヴィトン リュック スーパー コピー 全品大掃除代金引換 送料無料
VictorTug
October 12, 2026, at 9:55 amomni casino no deposit free spins 2026 e stave stavna lista danes
all star slots no deposit bonus codes 2026 top 10 online casinos europe slovenia Casino bonus za nove clane 888poker live vienna montesino casino
europa casino no deposit bonus codes legal online casino slovenia
JasperHig
October 12, 2026, at 10:30 amGood morning!
Top 5 Ways To Build Trust With Your Audience And Increase Your Sales
How To Build A Personal Brand? Step By Step Guide To Standing Out Online
Statistical Insights: The True Cost Of Employee Turnover For Modern Business
Link to the website – https://promomi.ru/holding-stejtment-pervyj-eshelon-zashhity-reputaczii-i-chto-eto-takoe-v-pr/
All the best!
Albertowit
October 12, 2026, at 11:16 amcrazy time live casino spletni casino brez depozita no deposit free bet slovenia igrice book of ra free
casino rewards instant win What is the €20 rule at the casino
JamesTus
October 12, 2026, at 11:32 amКупить Беленький Дюртюли Купить Кокаин, Мефедрон, Марихуану, МДМА Макарьев купить Метамфетамин Харабали купить Ecstasy
Albertowit
October 12, 2026, at 11:37 amfree poker money casino admiral ptuj wild vegas casino no deposit bonus codes real blackjack online
casino bonus no wager bingohall online casino
nstonekem
October 12, 2026, at 11:38 amоникс слэб
raskladkaplit.site
ступени из мрамора
JamesTus
October 12, 2026, at 11:55 amКупить ЛЁД Саяногорск Купить Кокаин, Мефедрон, Марихуану, МДМА Челябинск купить MDMA Pills – RED Прайс наркотиков
Albertowit
October 12, 2026, at 11:55 amfree vegas casino games 888 casino monopoly live bet365 poker bonus code no deposit bet at home casino app
casdep casino no deposit bonus codes casino bonus 2026
VictorTug
October 12, 2026, at 11:59 amblackjack online free euroking online casino free download
spletna igralnica hit vulkanvegas free spin no deposit Primerjava casino bonusov v Sloveniji 9 casino no deposit bonus
casino admiral princess bevkov trg nova gorica casino bonus 600
VictorTug
October 12, 2026, at 12:13 pmonline casino uk kingcasinobonus admiral casino opatija
igralni avtomat v kazinu lucky slots free games Seznam slovenskih spletnih casinojev z licenco gold club casino no deposit bonus 2026
lucky casino no deposit bonus casino belvedere izola slovenia
JamesTus
October 12, 2026, at 12:14 pmМосальск купить закладку VHQ Cocaine 98% Colombia Купить Марихуану, Кокаин, Бошки, Гашиш Козловка купить закладку MQ Cocaine Mexico Купить Герик Олёкминск
kamenkem
October 12, 2026, at 12:28 pmкерамогранит купить недорого
raskladkaplit.site
травертин москва
nstonekem
October 12, 2026, at 1:17 pmкупить гранитные плиты мощения
raskladkaplit.site
природный камень цена
VictorTug
October 12, 2026, at 3:08 pmslots of vegas no deposit bonus codes casino kranjska gora restaurant
live casino uk real money guess the game for 25 free spins Casino WinShark za Slovenijo blackjack 8 deck
bonus brez depozita book of ra volatility
VictorTug
October 12, 2026, at 3:21 pmigt online casino blackjack 6 deck
no deposit bonus 5 euro multilotto casino no deposit bonus codes 2026 Paysafecard online casino online live casino blackjack
kako isplatiti casino bonus 100 free spins no deposit bonus
Scottjex
October 12, 2026, at 3:31 pmстаф в Торопец Купить Кокаин, Мефедрон, Марихуану, МДМА Соликамск купить закладку VHQ Cocaine 98,8% Ecuador Великий Новгород купить закладку Гашиш [AB]
Albertowit
October 12, 2026, at 3:31 pmrich casino free spins casino slovenia bled casino lipica slovenija book of ra 6
argo casino no deposit bonus book of ra game slot
rosgvardiy_vxsn
October 12, 2026, at 3:50 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана цена.
Это позволяет минимизировать риск проникновения и предотвратить возможные угрозы.
Albertowit
October 12, 2026, at 3:51 pmruleta gratis online casino online casino igre besplatno blackjack slovenj gradec casino admiral lev bizi
casino portoroЕѕ bizi casino free games online
Scottjex
October 12, 2026, at 3:53 pmЗакладки лирика в Облучье Купить Кокаин, Мефедрон, Марихуану, МДМА Белоярский купить MDMA Pills – BLUE Карасук купить MDPV
nstonexkem
October 12, 2026, at 3:59 pmгранитные плиты
raskladkaplit.site
керамогранит цена за м2
Albertowit
October 12, 2026, at 4:09 pmjokaroom casino free spins bwin live casino spletni casino brez depozita ruby slots casino no deposit bonus codes
online casino x ojo online casino
Scottjex
October 12, 2026, at 4:12 pmЦимлянск купить закладку Гашиш [AB] Купить Марихуану, Кокаин, Бошки, Гашиш Закладки трамадол вБалашове Сердобск купить закладку эйфоретик MDMA
VictorTug
October 12, 2026, at 4:14 pmfree poker tournaments jackpot king demo
casino kranjska gora bingo live chat 888 casino Casino za pravi denar noble casino online
slotty vegas casino casino slots free spins
cambiarelacquaaifiTaini
October 12, 2026, at 6:10 pmViolette Toussaint è una donna che ha saputo trasformare il dolore in forza. La sua storia è un esempio di resilienza. Valérie Perrin scrive con una grazia che incanta. Questo romanzo è un viaggio nelle emozioni umane. Se preferite la lettura digitale, cercare “Cambiare l’acqua ai fiori pdf” è il modo migliore per accedere a questa storia meravigliosa. Un libro che vi rimarrà nel cuore per sempre, come un fiore che non appassisce mai. https://cambiarelacquaaifioripdf.site/ Cambiare L’acqua Ai Fiori Libro
VictorTug
October 12, 2026, at 6:17 pmfirst deposit bonus slovenia betting free lucky casino games
book ra online ruby slots casino no deposit bonus codes Spletni casino z izplacili v denarju iw casino online
casino bonus 10 euro sweet bonanza slot
SARAAvoip
October 12, 2026, at 6:20 pmhttps://intercom.help/bonuscode/fr-BE/articles/17129973-1xbet-ma-thưởng-chao-mừng-cược-miễn-phi-việt-nam-joinbet55-tiền-thưởng-3-000-000
VictorTug
October 12, 2026, at 6:30 pmbest poker no deposit bonus slot igre free
ruleta v zivo casino free spin no account Paysafecard casino grand theft auto online casino rocket
What casino games can win real money free spin no deposit casino cashout mastercard
Scottjex
October 12, 2026, at 6:34 pmБентота купить Ecstasy Купить Марихуану, Кокаин, Бошки, Гашиш Брянская область купить закладку Метадон, чистота 99% Оса купить Героин ОПТ
Albertowit
October 12, 2026, at 6:42 pmblack lotus casino no deposit bonus no deposit bonus casino not uk ruleta free game casino welcome bonus no deposit
ruleta namizna igra bookmaker no deposit bonus
Scottjex
October 12, 2026, at 6:56 pmЗлынка купить закладку MDMA Pills Купить Марихуану, Кокаин, Бошки, Гашиш Чадан купить закладку Марихуана [Outstanding Kush] Сельцо купить закладку VHQ Cocaine 98,8% Ecuador
Albertowit
October 12, 2026, at 6:59 pmcasino online dobrodoslica 10 paysafecard Do casinos give you free play free slots no download no registration bet365 bonus offer
best crypto online casinos casino igre bonus
Scottjex
October 12, 2026, at 7:15 pmОАЭ купить Мефедрон [Кристаллы] Купить Кокаин, Марихуану, Бошки, Мефедрон Москва Люблино купить закладку Психоделики Щёкино купить MDMA Crystal [Import]
VictorTug
October 12, 2026, at 7:23 pmWhich online casino actually pays real money casino online scams
bet365 deposit bonus codes bet365 casino jackpot Spletni casino s Paysafecard 10 euro no deposit bonus casino
f1 casino bonus book of ra free spins
Charleswealm
October 12, 2026, at 9:12 pmgonzo’s quest free spins slot madness no deposit bonus codes casinolistings games free slots best online casinos that payout
casino igre free download casino brez depozita brez pogojev
HerbertTweld
October 12, 2026, at 9:27 pm10 free spins no deposit book of ra magic free play
live casino reviews konung casino no deposit bonus code Spletna ruleta v igralnici live player casino game
casino igre slot besplatne mansion online casino
Charleswealm
October 12, 2026, at 9:33 pmonline casino for slovenia mobile casino no deposit bonus besplatne igre casino slot casino igre slot
bonuse casino games online casino portoroz slovenia
nstonexkem
October 12, 2026, at 9:38 pmмраморные плиты
slebizbloka.website
мрамор стоимость
Scottjex
October 12, 2026, at 9:39 pmРыльск купить закладку LSD-25 в марках 250мк Купить Кокаин, Мефедрон, Марихуану, МДМА Рыбное купить MDPV Бошки в Зеленокумске
HerbertTweld
October 12, 2026, at 9:40 pmvip programs on online casinos luxury casino rewards
How to play gambling games without money casino demo games Slovenski casino na spletu grand kazino online
betroadhousereels casino no deposit free spin free casino bonus no deposit
Charleswealm
October 12, 2026, at 9:50 pm5 min deposit online casinos igre casino free book free poker slot mashine quick hit casino slots free slot machines games
no deposit bonus casino 2026 real money What casino gives the best welcome bonus
Scottjex
October 12, 2026, at 10:01 pmСорск купить закладку MDMA таблетки Купить Марихуану, Кокаин, Бошки, Гашиш Коркино купить закладку Метадон HQ платинум тв онлайн
rosgvardiy_acsn
October 12, 2026, at 10:14 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана сигнализация.
Правильная организация охраны способствует предотвращению преступных действий и нарушений.
Scottjex
October 12, 2026, at 10:20 pmБрянская область купить Шишки White Widow Купить Кокаин, Мефедрон, Марихуану, МДМА Гвардейск купить закладку HQ Гашиш Удмуртия купить закладку Мефедрон (миф)
Stevekeype
October 12, 2026, at 10:22 pm[url=https://novobancptonline.com/]NOVO BANCO[/url]
O NOVO BANCO apresenta as informações de forma clara e organizada, tornando mais simples conhecer os serviços disponíveis e encontrar os canais adequados de atendimento.
LeonardLency
October 12, 2026, at 10:26 pmGates of Olympus, Sweet Bonanza i Sugar Rush dzialaja w Vavada z pelnym zakupem rundy bonusowej. Demo jest przy niemal kazdym automacie, wiec runde bonusowa poznasz bez ryzyka dla salda. Link do platformy: https://poagmahone.com/ Te dbalosc o tempo sesji widac od pierwszej wizyty i buduje ona dluzsza relacje z graczami.
nstonekem
October 12, 2026, at 10:28 pmгранитная плитка купить
slebizbloka.website
известняк купить
HerbertTweld
October 12, 2026, at 10:33 pmbet365 bonus slovenia What is the 1 3 2 6 strategy
casino portoroЕѕ online bet 365 paypal deposit Slovenska spletna igralnica ЕЎportne stave online casino
casino lev online grand kazino bonus
kamenkem
October 12, 2026, at 11:20 pmбелый камень известняк купить
slebizbloka.website
производство изделий из натурального камня
kefigFus
October 12, 2026, at 11:43 pmАгентство «Хватит» строит продвижение вокруг целей бизнеса, а не ради нарядных отчётов. Проект ведут под ключ: разбор нише, сайт, рекламные кампании, аналитика обращений. Ищете как снизить стоимость лида? Все услуги и кейсы собраны на сайте xvatit-marketing.ru — заявку оставляют онлайн. Смета прозрачная, а первые измеримые результаты появляются в течение месяца.
Charleswealm
October 13, 2026, at 12:03 amcasino igre free slot kako otvoriti online kazino bet365 mobile app sir jackpot casino no deposit bonus code
intertops red casino no deposit bonus best free to play poker site
Charleswealm
October 13, 2026, at 12:24 amfone casino no deposit bonus big free bonus no deposit poker avtomati free the best online casinos for slovenia players
casino igre lucky lady gametwist slots free slot machines casino games
nstonekem
October 13, 2026, at 12:36 amгранитная плитка 600х600
slebizbloka.website
укладка гранитной брусчатки цена за м2
HerbertTweld
October 13, 2026, at 12:37 amintertops red casino no deposit bonus bet win 365
joy casino 200 free spins which slot desertnightscasino no deposit bonus codes Casino na spletu blackjack online gratis
best blackjack strategy top online casino slovenija
Charleswealm
October 13, 2026, at 12:42 ambook of ra garminator all slots games free online book of ra game dealer casino slovenia
starburst casino free spins kako igrati igre v kazinu
Scottjex
October 13, 2026, at 12:44 amЕлизово купить Амфетамин Сульфат белый Купить Кокаин, Марихуану, Бошки, Мефедрон Прохладный купить закладку Гидропоника Afgan Kush Ровинь купить закладку LSD-25 (HQ) 170мкг
HerbertTweld
October 13, 2026, at 12:49 ampoker casino slovenija blackjack first person
online live casino blackjack book of ra game download Online igralnica za pravi denar casino bet365 promotions opening bonus
cabaret club online casino kazino igre besplatno
LeonardLency
October 13, 2026, at 1:05 amNowosci Vavada odswiezaja sie co tydzien: data premiery, mechanika i teoretyczne RTP. Reconnect protection w live zwraca zaklad na saldo, gdy stol nie doczeka gracza po zerwaniu lacza. Pelny regulamin znajdziesz tutaj: https://poagmahone.com/ Taka przejrzystosc zdejmuje glowne pytania nowicjuszy przed pierwsza wplata i buduje zaufanie do operatora.
Scottjex
October 13, 2026, at 1:06 amАпшеронск купить закладку гашиш Купить Кокаин, Марихуану, Бошки, Мефедрон Курская область купить закладку Ecstasy Rolls Royce Башкортостан купить закладку Амфетамин (фен)
Scottjex
October 13, 2026, at 1:25 amАрхангельск закладки Купить Кокаин, Мефедрон, Марихуану, МДМА Лукоянов купить закладку Порох 999 (HQ) Афган Москва ВАО купить закладку MDMA Pills – ORANGE
WebGuide77
October 13, 2026, at 1:42 amЙоу, народ! Если вы тоже задолбались ломать мозг над промтами для ChatGPT — я принес вам священный грааль годноты!
Какой-то гений собрал просто ультимативный гид, где чисто на пальцах и с юморком показывает, как одной кнопкой решать геморрой в Excel и Word. Там даже про Roblox Studio и эксель есть, прикиньте?!
Вся база знаний и секретные фишки лежат тут:
[url=https://www.chatgptbezvpn.com/prompty-i-instruktsii/kak-nastroit-chatgpt-pod-sebya-yazyk-stil-otvetov-i-pamyat/]кликни меня[/url].
Если после этого ваша жизнь не изменится — я не знаю, че вам еще надо! Всех обнял!
HerbertTweld
October 13, 2026, at 1:42 ambook of ra fixed high noon casino no deposit bonus
casino admiral san roque whitebet casino no deposit bonus Katera spletna igralnica je najboljsa v Sloveniji casino free spin no account
brezplaДЌni vrtljaji brez depozita deposit 1 euro
Charleswealm
October 13, 2026, at 2:54 amroulette online casino gamingclub 30 free spins What casino has free signup bonus no deposit required blackjack live dealer
ruleta seЕЎtevek ЕЎtevil 50 free spins no deposit casino
Charleswealm
October 13, 2026, at 3:15 amhow much do online casinos make governor of poker download free full game kiosk casino bled spin palace casino no deposit free spins
blackjack online simulator diamond world casino no deposit bonus codes
Charleswealm
October 13, 2026, at 3:33 ambet365 bonus terms spletni casino paysafecard company casino no deposit bonus kazino igre knjige
casino casino free spins video avtomati online
HerbertTweld
October 13, 2026, at 3:46 amslovenia casino aurora black jack ДЌrnuДЌe
slot igrice book of ra slot games free casino igt Casino slot igre live casino uk real money
vegas online casino casino igre aparati besplatne
Scottjex
October 13, 2026, at 3:48 amБалаково купить закладку Cocaine MQ Купить Кокаин, Марихуану, Бошки, Мефедрон купить наркотики Долинск Минотавр магазин
HerbertTweld
October 13, 2026, at 3:58 amspletna igralnica brez depozita free spins casino no deposit november 2026
online casino jobs online poker real money free bonus Igralni avtomati na spletu ra gold slot
free video slot games best online casino in world
Scottjex
October 13, 2026, at 4:10 amТавда купить закладку Ecstasy: Red Bull 200 mg Купить Кокаин, Мефедрон, Марихуану, МДМА ЕвпаторияОспаривается купить Cтимуляторы Тверская область купить HQ Гашиш NO NAME
Scottjex
October 13, 2026, at 4:29 amЧусовой купить Метадон, чистота 99% Купить Кокаин, Мефедрон, Марихуану, МДМА Иваново купить LSD 220 мг Инта купить закладку Чистейший кокаин 98%
HerbertTweld
October 13, 2026, at 4:52 ambrezplaДЌni vrtljaji brez depozita casino admiral kozina bingo
grand wild casino no deposit bonus codes bit games casino Bonus ob registraciji v casinu carnevale casino slovenia
brezplaДЌne igre casino konji bet 365 croatia link
Charleswealm
October 13, 2026, at 5:45 amminimum deposit 1 euro jackpot city online casino villa fortuna casino no deposit bonus codes 2026 online casino slots
casino bonus slovenija superlenny casino no deposit free spin
Charleswealm
October 13, 2026, at 6:06 amcasino belvedere izola slovenia book of ra pokerstars kazino fraj igre kranjska gora casino
gratis casino online spiele partypoker live casino
Charleswealm
October 13, 2026, at 6:24 ambesplatne casino igre book of ra casino 1€ deposit bonus new online casino how to party casino bonus code no deposit
spacelilly casino no deposit bonus casino bonus 100
Scottjex
October 13, 2026, at 6:52 amКурьер курительных смесей Купить Марихуану, Кокаин, Бошки, Гашиш Новокузнецк купить Ecstasy: Pink Heart 200mg Москва Тушино Северное купить закладку Лирика 300мг (Прегабалин)
HerbertTweld
October 13, 2026, at 6:56 amsign up casino bonus no deposit live casino games
party casino online free casino bonus Igralni avtomati casino on bet365
free spin no deposit casino cashout mastercard What does a 35 to 1 payout mean
HerbertTweld
October 13, 2026, at 7:09 ambet365 bonus joining code online casino advice
juicy stakes casino no deposit bonus bet365 mobile app download Najboljse ponudbe casino bonusov v Sloveniji spletni avtomati z visokim rtp
onlain kazino bg 2026 casino bonus
Scottjex
October 13, 2026, at 7:15 amСолигалич купить закладку Ecstasy – UPS Купить Марихуану, Кокаин, Бошки, Гашиш стаф в Усть-Лабинск Москва Очаково-Матвеевское купить DMT
Scottjex
October 13, 2026, at 7:33 amкупить наркотики Лиски Купить Марихуану, Кокаин, Бошки, Гашиш Купить Гашиш в Апшеронск Егорьевск купить эйфоретик MDMA
nstonexkem
October 13, 2026, at 7:39 amмрамор крема марфил
faktura-vybor.space
сколько стоит уложить гранитную плитку
HerbertTweld
October 13, 2026, at 8:02 amAre no deposit bonuses really free zodiac casino no deposit
free spin no deposit europa ЕЎportne stave danes Bizzo casino blackjack vs 21
juicy stakes no deposit bonus casino igre za pravi denar brez depozita
phggjili
October 13, 2026, at 8:26 amHonestly the best experience I have had with slots recently. The payouts are fair and the interface is super smooth. Check out phggjili for a great time.
nstonexkem
October 13, 2026, at 8:30 amкерамогранит интернет магазин
faktura-vybor.space
купить натуральный камень мрамор
Charleswealm
October 13, 2026, at 8:36 amgratis casino online spiele live casino eu igre casino book of ra igre za denar preko interneta
yebo casino no deposit bonus codes 2026 bet365 app ios
Charleswealm
October 13, 2026, at 8:57 amlive casino black jack superlenny casino no deposit free spin no deposit bonus casino free spins real time gaming casinos
slotty vegas casino zodiac casino review
Charleswealm
October 13, 2026, at 9:15 amaussie online casino online casino free spins blackjack perfect strategy igre casino 123
casino bonus brez depozita 5 euro slot game free igt
kamenkem
October 13, 2026, at 9:23 amкерамогранит 60х60 купить
faktura-vybor.space
гранит цена
Michaelpex
October 13, 2026, at 9:57 amАсбест купить Кокаин Супер Качества [Ecuador] Купить Кокаин, Мефедрон, Марихуану, МДМА Майрхофен купить LSD Кировская область купить наркотики
Morrislaw
October 13, 2026, at 10:06 amlive dealer casinos book of ra simulator
no deposit bonus casino europe real money vulkanvegas free spin no deposit Hell Spin casino Slovenija online casino check in
hotel & casino resort admiral ice casino bonus no deposit
Morrislaw
October 13, 2026, at 10:19 amwelcome bonus 100 spins free spletna igralnica brez depozita
hit casino perla online casino admiral zagreb Casino igre na spletu grand kazino bonus
slotsmoon casino no deposit bonus codes casino stream online
Michaelpex
October 13, 2026, at 10:19 amКоммунар купить Героин в камнях Купить Кокаин, Марихуану, Бошки, Мефедрон Гашиш в Муре купить стаф в Батайск
Michaelpex
October 13, 2026, at 10:38 amТамбов купить MDMA Pills – ORANGE Купить Кокаин, Мефедрон, Марихуану, МДМА Усмань купить Гашиш [AB] Починок купить закладку Ecstasy: Yellow Homer 200mg
nstonexkem
October 13, 2026, at 10:41 amкерамогранит купить в москве
faktura-vybor.space
гранит габбро
Morrislaw
October 13, 2026, at 11:12 amf1 casino bonus free online casino
blackjack not gambling bronze casino bonus code no deposit Casino slot igre best free gambling sites
deposit 1 get free spins kazino igre sizzling hot
nstonexkem
October 13, 2026, at 12:09 pmгранитная плитка для улицы
faktura-vybor.space
мрамор слэбы
RiverTravelGuide
October 13, 2026, at 12:13 pmA small set of English phrases can help with everyday travel situations, from asking about boarding to checking the time of a departure. Keep the wording simple, save important addresses on your phone and make sure you understand the answer before moving on. This Russian-language passenger note focuses on practical communication during a river journey. It can be useful preparation for travellers who want a short reminder rather than a long language course. Read more: Useful English for a river journey. https://rechnye-puteshestviya-guide.blogspot.com/2026/10/blog-post_867.html
rosgvardiy_jusn
October 13, 2026, at 12:39 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана цена.
Объекты, охраняемые Росгвардией, включают как государственные учреждения, так и коммерческие предприятия.
Michaelpex
October 13, 2026, at 12:58 pmМосква Сокольники купить закладку Cтимуляторы Купить Марихуану, Кокаин, Бошки, Гашиш Холмск купить закладку Чистейший кокаин 98% Вельск купить закладку Героин ОПТ
Morrislaw
October 13, 2026, at 1:13 pmqueen vegas casino no deposit bonus code casino korona kranjska gora program
casino bonus 5 euro baccarat free spins Casino bonus zodiac casino flash
intertops casino no deposit bonus codes magic red casino free spins
Michaelpex
October 13, 2026, at 1:19 pmЛюбань купить закладку Мефедрон в мелких камнях/муке Купить Марихуану, Кокаин, Бошки, Гашиш Лыткарино купить Мефедрон [Кристаллы] Москва Гольяново купить MDMA Pills – GREEN
Morrislaw
October 13, 2026, at 1:25 pmwixstars casino online kazino igre book of ra
spletni avtomati za pravi denar live casino europe Igre v online casinu energy casino no deposit bonus
real money casino games casino online cash out paysafecard
RodgerTroke
October 13, 2026, at 1:38 pmУфа купить MDMA Pills – GREEN https://arttex-sochi-loft.ru Каргополь купить закладку Ecstasy: Yellow Stars 350 mg Оренбургская область купить закладку Гашиш [Euro Cube]
Morrislaw
October 13, 2026, at 2:16 pmpending bonus dollars bet365 5 euro no deposit bonus casino czk
pop slots free chips verde casino bonus code no deposit Slot igre v igralnici casino vip bonus
bwin live poker casino bonus paysafe
AnthonyCloup
October 13, 2026, at 3:57 pmМосква Проспект Вернадского купить закладку Гашиш [LV] https://bis86.ru
Morrislaw
October 13, 2026, at 4:17 pm888 poker how to get 88 free big free bonus no deposit
kateri spletni casino so ok online casino 2026 Online ruleta 7 reels casino no deposit bonus
zodiac casino mobile igralni avtomat v kazinu
AnthonyCloup
October 13, 2026, at 4:19 pmИнсар купить закладку Психоделики https://psk18.ru
Morrislaw
October 13, 2026, at 4:29 pm10e no deposit bonus casino fanduel live casino
best casino games juicy stakes casino no deposit bonus 100 WinShark hotel casino safir sezana slovenia
old havana casino no deposit bonus 2026 thebigchip brezplaДЌne casino free igre
AnthonyCloup
October 13, 2026, at 4:38 pmкупить закладку в Альметьевск https://bis86.ru
Morrislaw
October 13, 2026, at 5:21 pmhit kranjska gora casino kontakt spletni casino brez depozita
euro king online casino download casino igre za pravi denar brez depozita Online igralnica neteller online casinos
no deposit bonus casino estonia free spins jackpot city
nstonexkem
October 13, 2026, at 5:52 pmприродный камень для дорожек купить
naprosvet.site
мрамор крема марфил
kamenkem
October 13, 2026, at 6:45 pmкерамогранит оптом
naprosvet.site
столешница из искусственного камня для кухни цена
VincentNudge
October 13, 2026, at 6:56 pmЛесосибирск купить закладку Мефедрон [мелкие камни/мука] HQ https://shopgas.ru
VincentNudge
October 13, 2026, at 7:18 pmБуйнакск купить эйфоретик MDMA https://rlinfo.ru
Morrislaw
October 13, 2026, at 7:20 pmdoubledown casino free slots quick hit casino slots free slot machines games
live 888 casino login casino ДЌopova ljubljana Katera spletna igralnica je najboljsa v Sloveniji besplatne casino igre online
verde casino bonus code crypto poker register free money
Morrislaw
October 13, 2026, at 7:33 pmcasino bonus brez depozita 5 euro 25 free spins no deposit bonus
kako se broje karte u blackjacku rich casino no deposit bonus codes Spletna ruleta v igralnici online casino izplaДЌila v sloveniji
casino bonus free spins no deposit jackpot casino rewards
VincentNudge
October 13, 2026, at 7:36 pmАзнакаево купить Кокаин HQ https://turpesni.ru
nstonekem
October 13, 2026, at 7:41 pmукладка гранитной плитки цена
naprosvet.site
травертин слэб
Morrislaw
October 13, 2026, at 8:23 pmlive casino online free party poker free
bet365 loyalty bonus casino casino free spins Igralnica na spletu Slovenija crypto poker register free money
betway live casino book of ra online free
nstonexkem
October 13, 2026, at 8:59 pmмрамор крема марфил
naprosvet.site
производство изделий из натурального камня
JosephLet
October 13, 2026, at 10:14 pm[url=https://wheelouttogame.online]купить кухню в екатеринбурге
[/url]
Aaronexifs
October 13, 2026, at 10:22 pmfree spins rio casino book of ra tricks
pontoon vs blackjack bet365 free spins Slovenski online casino jet casino bonus code
river belle juegos de casino online blackjack video poker
SHAUNAAvoip
October 13, 2026, at 10:24 pmhttps://intercom.help/bonuscode/lt/articles/17135410-jinsi-msimbo-wa-ofa-wa-melbet-unavyofanya-kazi-tanzania-max888-350-000-tzs
nstonekem
October 13, 2026, at 10:29 pmтравертин купить в москве
naprosvet.site
керамогранит цена за м2
Aaronexifs
October 13, 2026, at 10:35 pmtwist casino online no deposit bonus casino slovenia
chances to get free spins on slot machines 888 live casino login Preberi vec tukaj migliore casino slovenia
bet365 poker bonus explanation brezplaДЌne casino igre online
Aaronexifs
October 13, 2026, at 11:25 pmslovenski casino slot online novomatic free slots
platinum casino online ice casino promo code Spletni casino za pravi denar najboljЕЎi online casino slovenija
free online casino slots mega sic bo
Randywaync
October 13, 2026, at 11:59 pmvery good
_________________
[url=https://topbonus.work/banda-casino/]Banda[/url]
Keithbar
October 14, 2026, at 1:17 amhttps://intercom.help/bonuscode/ms/articles/17023845-codigo-de-giros-gratis-1xbet-bono-y-registro-peru-2026-joinbet55
MITSUEmeert
October 14, 2026, at 1:17 amhttps://intercom.help/bonuscode/ja/articles/17130963-1xbet-welcome-bonus-code-today-china-joinbet55-bonus-130
DEONNAFag
October 14, 2026, at 1:18 amhttps://intercom.help/bonuscode/id/articles/17131090-1xbet-registration-code-registration-new-zealand-joinbet55-bonus-130
KARIKEYMN
October 14, 2026, at 1:24 amhttps://intercom.help/bonuscode/es/articles/17035231-промокод-melbet-кыргызстан-2026-wap200
Aaronexifs
October 14, 2026, at 1:25 ambwin live blackjack yukon gold casino free spins no deposit
betchan casino no deposit bonus codes live casino blackjack Casino bonusi Slovenija blackjack card counting
Do casinos give you free play evolution live casino
Aaronexifs
October 14, 2026, at 1:37 amfree spins on sign up casino no deposit bonus casino estonia
free slots no deposit bet at home bonus casino Katera je najboljsa spletna igralnica za igralce iz Slovenije casino deposit 1 €
poker bet 365 slovenija bonus no wagering casino
rosgvardiy_ndsn
October 14, 2026, at 2:04 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, пультовая охрана мвд.
Охрана объектов невозможна без регулярного контроля и профилактических мероприятий Росгвардии.
Aaronexifs
October 14, 2026, at 2:28 amcasino as igre starburst free spins
stargames online casino bet365 it app Online casino v Sloveniji casino faraon celje
casino online game online casino free bonus no deposit required 2026
nstonekem
October 14, 2026, at 4:06 amоникс слэб
spc-osnova.online
гранитная плитка 600х600
Aaronexifs
October 14, 2026, at 4:27 amcasino bled kristina doviДЌevska Are slots all luck or is there skill
no deposit bonus casino codes casino bled skupЕЎДЌina Brezplacne igre na avtomatih 7sultans no deposit bonus
book of ra za pravi dennar book of ra two symbols
Aaronexifs
October 14, 2026, at 4:40 amslovenski spletni casino bet365 join up bonus code
win free spins pop up best online casino for quick withdrawals Slovenski spletni casinoji brezplaДЌne igre na avtomatih
platinum reels no deposit bonus casino europe online
kamenkem
October 14, 2026, at 4:58 amкупить гранитные плиты мощения
spc-osnova.online
слэб натурального камня
RickPaf
October 14, 2026, at 5:14 amSolid stuff, the kind of post that I will probably refer back to later this month when the topic comes up again, and a look at walnutcovevault only confirmed I should bookmark the site as a whole rather than just this single page for future reference and use across coming weeks.
Aaronexifs
October 14, 2026, at 5:31 am777 online casino najboljЕЎi bonus za registracijo brez vplaДЌila
bet 365 croatia link welcome free spins Slovenski casino free slots new games
energy casino no deposit bonus casino bonus 10 euro
kamenkem
October 14, 2026, at 5:49 amукладка гранитной брусчатки цена за м2
spc-osnova.online
керамогранит купить в москве
nstonekem
October 14, 2026, at 7:07 amсколько стоит столешница из искусственного камня
spc-osnova.online
гранит купить
ekran_bbPt
October 14, 2026, at 7:08 amВыбирая экран для проектора, вы можете выбрать оптимальный вариант, учитывающий качество и стоимость.
Выбор экрана для проектора играет ключевую роль в создании качественного изображения . Он обеспечивает яркое, четкое и насыщенное изображение, что особенно важно для деловых встреч и образовательных мероприятий.
При выборе экрана для проектора следует учитывать его тип и материал . Например, тканевые модели обладают хорошей универсальностью, а экранные поверхности из специально обработанных материалов обеспечивают высокую яркость и контрастность.
Поэтому правильный выбор экрана обеспечивает яркое и четкое отображение изображений. Кроме того, важно учитывать размеры помещения и расстояние до экрана, чтобы он был максимально удобен для зрителей.
Выбор зависит от задач и условий использования. Портативные модели легко переносить и устанавливать, а стационарные обеспечивают более стабильное качество изображения и долговечность.
Матовые поверхности уменьшают блики и обеспечивают равномерное отображение . При выборе необходимо учитывать условия освещения в помещении и желаемое качество изображения.
Качественный монтаж обеспечивает длительный срок службы и стабильную работу. Правильный подбор и установка экрана помогают добиться максимально высокого качества презентации или просмотра.
NathanSaf
October 14, 2026, at 7:30 amwild jack casino no deposit bonus codes 2026 bet365 100 bonus
blackjack do you hit on 14 free spins no deposit bonus Slovenski casino bonusi book of ra two symbols demo
spletna igralnica za pravi denar lucy casino igre
NathanSaf
October 14, 2026, at 7:43 ambet365 poker bonus code no deposit hotel casino resort admiral
slo online casino live casino black jack Slot avtomati What is the most paid out online casino
blackjack 8 deck roulette live online casino
rosgvardiy_ebsn
October 14, 2026, at 8:10 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, росгвардия охрана объектов.
Правильная организация охраны способствует предотвращению преступных действий и нарушений.
dumuglila
October 14, 2026, at 8:17 amЛюбителям сериалов больше не придется подолгу искать желанные новинки в сети. Актуальные новинки и золотая классика представлены в едином каталоге по честным ценам. Ищете купить коломбо сериал? Интернет-магазин serialexpress.ru предлагает огромный каталог отечественных и зарубежных сериалов с доставкой по всей России. Сделать заказ можно за две минуты, а получить его — в самое ближайшее время. Высокое качество записи и бережная упаковка — стандарт для каждого заказа.
NathanSaf
October 14, 2026, at 8:34 amno deposit ecopayz casino bonuses novomatic online casino
hit kranjska gora casino brezplaДЌne casino igre avtomati Igralni avtomati free offline casino pc games
21 jack casino casino nova gorica
nstonexkem
October 14, 2026, at 8:38 amстолешница травертин
spc-osnova.online
оникс с подсветкой купить
Malcolmlon
October 14, 2026, at 9:04 amЕсли интересует [url=https://kwork.ru/e-commerce-social-network/55107526/dizayn-kartochki-tovara-infografika-dlya-marketpleysa-ozon]стоимость инфографики для маркетплейса Ozon Кворк[/url] – это отличная возможность выделить товар среди конкурентов, показать его преимущества и повысить интерес покупателей. Разрабатываю современную инфографику, подбираю композицию, шрифты и визуальные акценты с учетом особенностей товара. Карточка получается понятной, привлекательной и ориентированной на продажи.
PINGTus
October 14, 2026, at 10:33 amhttps://intercom.help/bonuscode/ko/articles/17035764-melbet-promosyon-kodu-turkiye-wap200
NathanSaf
October 14, 2026, at 10:34 amjoker poker free online ruleta free game
seriöse online casinos mit startguthaben iw casino online Tukaj bet365 how to get bonus
queen vegas casino no deposit bonus code admiral casino tГЎbor
DOVIEFag
October 14, 2026, at 10:46 amhttps://intercom.help/bonuscode/id/articles/17128176-mostbet-bonusablauf-most888-bis-zu-400
NathanSaf
October 14, 2026, at 10:47 ammiami casino online spletno kazino slovenija
free online poker best sites casino 1€ deposit bonus Igralnica online coral live casino
casino bonus brez pologa miami dice casino no deposit bonus
ELNORAKEYMN
October 14, 2026, at 11:07 amhttps://intercom.help/bonuscode/es/articles/17130367-1xbet-registration-code-casino-chad-joinbet55-bonus-130
NathanSaf
October 14, 2026, at 11:37 amno deposit casino bonus 2026 free casino games real money
free casino games lucky lady charm welcome bonus 100 spin free Book of Ra igra kazino fraj igre
free spins weekly cashback bonus no wagering casino
MALKApeR
October 14, 2026, at 12:54 pmhttps://intercom.help/bonuscode/it/articles/17017277-актуальный-промокод-1xbet-для-казахстана-joinbet55
SteveSoump
October 14, 2026, at 12:54 pmhttps://intercom.help/bonuscode/lv/articles/17017283-промокод-1xbet-при-регистрации-для-армении-2026-joinbet55
KEVINReiny
October 14, 2026, at 12:55 pmhttps://intercom.help/bonuscode/hu/articles/17025196-1xbet-sportbonus-promocode-luxemburg-2026-joinbet55
RACHEALTus
October 14, 2026, at 1:01 pmhttps://intercom.help/bonuscode/ko/articles/17024855-1xbet-promo-code-sa-pilipinas-2026-joinbet55-bag-ong-account-bonus
Williamnuava
October 14, 2026, at 1:06 pmмаша раздольская
DELLFag
October 14, 2026, at 1:19 pmhttps://intercom.help/bonuscode/id/articles/17151151-1xbit-promo-code-cameroon-btc777-bonus-7-btc
NathanSaf
October 14, 2026, at 1:37 pmcasino ljubljana slovenia book of ra deluxe 6 slot
betway live casino blackjack 8 deck strategy Online casino s Paysafecard placilom free poker programs
tangiers casino free spins bet at home poker slovenija
HERTAKEYMN
October 14, 2026, at 1:41 pmhttps://intercom.help/bonuscode/es/articles/17035191-промокод-melbet-україна-2026-wap200-правила-відіграшу
NathanSaf
October 14, 2026, at 1:48 pmtwist casino free games Can you win real money with free play
casino fontana slovenia free bet no deposit bonus Bizzo casino Slovenija bonus za nove igralce book of ra gratis
best slots on bet 365 virtual casino no deposit bonus 2026
Williamnuava
October 14, 2026, at 1:58 pmrose rouge revolution
RichardWaype
October 14, 2026, at 2:29 pmПодбор проката под конкретный объект не сводится к поиску самого дешёвого предложения. Поэтому [url=https://kkuicop.com/view.php?url=https://metprokat.com/]портал о металле и строительстве[/url] выстраивает свои статьи вокруг практических задач: от проекта и назначения элемента до приёмки партии. Любая статья подготовлена так, с тем чтобы снабженец мог сразу получить ответ на рабочий вопрос, и разделы [url=https://www.prairieoutdoors.com/lt.php?lt=https://metprokat.com/]справочника METPROKAT[/url] покрывают все ключевые темы отрасли.
Наглядный пример — вопрос, какую трубу взять — нержавеющую или углеродистую. Нержавеющую стальную трубу берут ради нужной коррозионной стойкости в конкретной среде, а не потому, что она якобы не ржавеет вовсе. Марка металла, температура а также химический состав среды важнее, нежели расхожие мифы, — наглядно о нюансах выбора рассказывает [url=https://services.nfpa.org/Authentication/GetSSOSession.aspx?return=https://metprokat.com/]база знаний о металле[/url]. Похожая логика нужна и для гнутого и горячекатаного профиля: гнутый профиль может быть выгоднее в определённых условиях, но так бывает далеко не всегда. Сравнивать нужно конструкцию целиком с учётом расчёта, узлов и монтажа — именно так вопрос рассматривает [url=https://linklock.titanhq.com/analyse?url=https://metprokat.com/]портал METPROKAT[/url].
[url=https://fedorshmidt.com/?URL=https://metprokat.com/]Портал о металлопрокате и строительстве[/url] уделяет отдельное внимание стандартам и документам. При заказе металлопроката в Украине важно сверить нужный стандарт, актуальную редакцию документа а также условия проекта: отметка ДСТУ, EN или ГОСТ без сопроводительных документов не гарантирует качества. Не менее полезен блок о том, как производят металлопрокат: разливка заготовок, горячая прокатка, финишная обработка и, конечно, контроль описаны так доступно, что неспециалист быстро поймёт, как всё устроено. Такие статьи собраны на страницах [url=https://droid.yamaster.org/bitrix/rk.php?goto=https://metprokat.com/]ресурса METPROKAT[/url].
Прикладная ценность [url=https://www.protassiumplus.com/?URL=https://metprokat.com/]ресурса о металлопрокате[/url] особенно заметна в материалах о хранении металлопроката. Чтобы сохранить прокат, нужно ограничить увлажнение, организовать правильное опирание а также регулярно проверять складские партии — навес без вентиляции не всегда решает проблему. Столь же полезны рекомендации по оптовой закупке метизов: начинать её следует с подробной спецификации, а не с поиска самой низкой цены. Именно такие практические подсказки делают [url=https://www.oxfordpublish.org/?URL=https://metprokat.com/]ресурс о металлопрокате[/url] настольным справочником для инженеров и закупщиков.
Отдельного упоминания заслуживает блок «База знаний» [url=https://www.avenue-x.com/cgi-bin/gforum.cgi?url=https://metprokat.com/]сайта о металлопрокате[/url]: плотность металлов, стандарты, выбор крепежа и выбор металлопроката собраны в единую систему, и примеры расчёта веса полосы 40 ? 4 и 50 ? 5 мм и описание швеллера помогают сразу выбрать подходящий прокат. Таким образом [url=https://www.cricbattle.com/Register.aspx?Returnurl=https://metprokat.com/]портал METPROKAT[/url] является тем местом, куда хочется возвращаться всякий раз, когда нужно подобрать металл для конкретной задачи — по делу.
NathanSaf
October 14, 2026, at 2:39 pmfree blackjack trainer free slot machine games without downloading or registration
book of ra delux 6 online free casino igre bonus Spletne igre v casinu najboljЕЎe spletne igralnice
online casino games real money 1€ casino bonus
Williamnuava
October 14, 2026, at 2:55 pmvivienne westwood
Malcolmlon
October 14, 2026, at 3:16 pmЕсли интересует [url=https://kwork.ru/e-commerce-social-network/55107526/dizayn-kartochki-tovara-infografika-dlya-marketpleysa-ozon]где заказать дизайн карточки товара для Ozon Кворк[/url] – это отличная возможность выделить товар среди конкурентов, показать его преимущества и повысить интерес покупателей. Разрабатываю современную инфографику, подбираю композицию, шрифты и визуальные акценты с учетом особенностей товара. Карточка получается понятной, привлекательной и ориентированной на продажи.
rosgvardiy_eqsn
October 14, 2026, at 3:29 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана.
Такая организация обеспечивает высокий уровень защиты и минимальные риски для охраняемых объектов.
Williamnuava
October 14, 2026, at 4:24 pmhttps://www.instagram.com/rrr9_clothes
NathanSaf
October 14, 2026, at 4:50 pmslovenia casino ljubljana best of online game casino cashout
online casino no deposit 2026 captain jack casino free 200 Slovenski spletni casinoji casino 20 euro no deposit
captain cooks casino play no deposit bonus casino not uk
NormanDaw
October 14, 2026, at 5:20 pmГаврилов Посад купить закладку Лирика 300мг (Прегабалин) купить закладку в Новоалександровск
Киржач купить АК-47 – Бошки Шишки Купить Кокаин, Марихуану, Бошки, Мефедрон Индия купить эйфоретик Мефедрон
Буй купить закладку Шишки White Widow Игарка купить АК-47 – Бошки Шишки
NathanSaf
October 14, 2026, at 5:41 pmregister jackpot city casino slot games free gipsy moon
What is the best online casino app kako igrati pokerstars v sloveniji Igraj ruleto online casino bled bizi
b-bets casino no deposit bonus swiss casino online
NormanDaw
October 14, 2026, at 5:41 pmКалач-на-Дону купить закладку Метадон VHQ Омутнинск купить закладку Гашиш [LV]
Банско купить закладку Марихуана [Hillary Clinton Kush] Купить Кокаин, Марихуану, Бошки, Мефедрон Нягань купить Гашиш [LV]
Егорьевск купить Cocaine HQ Алтайский край купить Метадон, чистота 99%
NormanDaw
October 14, 2026, at 6:00 pmЮжноуральск купить Марихуана [Amnesia Haze] Байкальск купить закладку Марки LSD 170мкг
Красавино купить закладку VHQ Cocaine 98% Bolivia Купить Кокаин, Марихуану, Бошки, Мефедрон Миксы новосибирск
Сатка купить Метадон HQ Зеленоградск купить закладку VHQ GanBang Cocaine 98% Peru
CecilFig
October 14, 2026, at 6:38 pmThanks for putting this online without locking it behind email signups or paywalls, and a quick visit to skybrookmarketfoundry kept that open feel going, content that trusts the reader to come back rather than gating access is the kind of approach I will reward with regular return visits over time happily.
Davidsmite
October 14, 2026, at 6:46 pmNow feeling mildly impressed in a way I do not quite remember feeling about a blog in a while, and a stop at berrystoneoutpost extended that mild impression, content that produces specific positive emotional responses rather than just neutral information transfer is content with extra dimensions and this site has those extra dimensions clearly.
megamarketRag
October 14, 2026, at 7:12 pm[center][b]Мегамаркет5 — актуальные зеркала 2025[/b][/center]
[center][i]Обновлённые адреса напрямую[/i][/center]
[center][url=https://mgmarket4.store/shop/dbea3708a0fb82548b1d8e44e7d94026][img]https://mega-market.shop/cdn/95474d78fc5e2eb4eea6315485879b1a4744a438b98d701400ff435b6bc8aad0.jpg[/img][/url][/center]
Расскажу личный опыт — как я вышел на мегамаркет5 и отчего до сих пор работаю на площадку.
Года полтора назад пытался найти адекватный закрытый ресурс. Протестировал немало всяких сайтов — большинство являлись либо скамом. Потратил впустую немного средств на сомнительных сайтах пока не вышел на MG Market.
Первый раз зашёл по совету — анон на борде скинул адресом. Сначала недоверял — уж очень много скама было прежде. Но решил проверить.
Как оказалось — всё нормально. Площадка нормальный, продавцы с отзывами, механизм безопасности работает. С тех пор пользуюсь регулярно.
Основная проблема — держать живой переходник. Маркетплейс периодически обновляет зеркала — для безопасности. Поэтому делюсь тут проверенными ссылками — чтобы народу не нужно было так долго искать.
[list=1]
[*] [url=https://mgmarket7.name]Приложение HideMEGA — безопасный вход через приложение[/url]
[*] [url=https://mgmarket3.store]Зеркало MGMarket5 — без VPN[/url]
[*] [url=https://mgmarket4.store]Маркетплейс MGMarket5 — перейти[/url]
[/list]
В случае если один из переходник недоступен — без паники: просто пробуйте запасной. Все они направят на единую Мегу.
Удачи — и не теряйте актуальные ссылки. Спрашивайте — отвечу если что.
[size=1][color=#333333]mgmarket5 at, https mgmarket5 at, http mgmarket5 at, 37 mgmarket5 at, https 37 mgmarket5 at, 64 mgmarket5 at, https mgmarket5 at login html, https mgmarket5 at main, m mgmarket5 at, mgmarket5 ru, 5 mgmarket5 at, 55 mgmarket5 at, https 6 mgmarket5 at, https m mgmarket5 at, 13 mgmarket5 at, https 55 mgmarket5 at wallet форум, mgmarket5 cc, https mgmarket5 at catalog, https 37 mgmarket5 at login html, https 6 mgmarket5 at login html, mgmarket5 at referralcode, mgmarket5 ay, mgmarket5 at зеркало, 37 mgmarket5 ru, http 37 mgmarket5 at, https 64 mgmarket5 at login html[/color][/size]
BertBiz
October 14, 2026, at 7:21 pmFelt the post had been quietly polished rather than aggressively styled, and a look at silvercovevault confirmed the same understated polish, sites whose quality reveals itself slowly rather than announcing itself loudly are the kind I trust more deeply because the trust is not based on first impressions of marketing but actual substance.
NathanSaf
October 14, 2026, at 7:40 pmcasino online besplatno company casino no deposit bonus codes
igre poker avtomati Which casino app gives free spins Hell Spin casino pregled 888poker live vienna montesino casino
kako izbrati varno spletno igralnico casino free bonus
Duanedom
October 14, 2026, at 7:52 pmbest of online game casino cashout slovenia play free slots
limoplay casino no deposit bonus codes spletne casino igre za pravi denar Igraj slote v casinu getminted free slot games
igre za denar best online casino slovenija forum
NormanDaw
October 14, 2026, at 8:18 pmМосква Войковский купить Психоделики Шахунья купить закладку Cocaine HQ
Черноголовка купить Гашиш [AB] Купить Кокаин, Марихуану, Бошки, Мефедрон Городище купить АК-47 – Бошки Шишки
Горно-Алтайск купить LSD Усть-Джегута купить марихуану
NormanDaw
October 14, 2026, at 8:40 pmШали купить закладку Mephedrone (4mmc, мяу) Суровикино купить Cocaine Premium: Peru
Тольятти купить Мефедрон (миф) Купить Кокаин, Марихуану, Бошки, Мефедрон Новокубанск купить закладку HQ Гашиш NO NAME
Навашино купить закладку LSD-25 (HQ) 250мкг Боровск купить закладку Cocaine HQ
MelvinJem
October 14, 2026, at 8:44 pmfree casino games no download book of ra deluxe resolution
no deposit ecopayz casino bonuses slot game free igt vega Igraj ruleto online casino igre za slovenijo
company casino no deposit free spins casino games free slots download
NormanDaw
October 14, 2026, at 8:58 pmШарья купить закладку Гидропоника Afgan Kush Татранска Ломница купить Ecstasy: Yellow Homer 200mg
Полысаево купить закладку Героин РОЗНИЦА (999 VHQ) Афганистан Купить Кокаин, Марихуану, Бошки, Мефедрон Топки купить Марихуана [Outstanding Kush]
Дубна купить закладку Метадон (HQ) Германия Москва Братеево купить закладку Мефедрон в мелких камнях/муке
rosgvardiy_tisn
October 14, 2026, at 9:56 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана в москве.
Объекты, охраняемые Росгвардией, включают как государственные учреждения, так и коммерческие предприятия.
BoydDup
October 14, 2026, at 10:37 pmTook longer than expected to finish because I kept stopping to think, and a stop at echobrookvault did the same to me, content that provokes thought rather than just delivering information is in a different category and the team here is clearly working at that higher level rather than just cranking out posts.
MelvinJem
October 14, 2026, at 10:42 pmcasino lev nagradne igre crypto poker register free money
lucky lady besplatne igre jackpot naslednje zrebanje Igralni avtomati v spletnem casinu free casino slot machines
free spins casino no deposit new codes 2026 casino bonus brez depozita 20 €
MelvinJem
October 14, 2026, at 10:55 pmbet365 casino bonus book of ra prenos igre
play free casino slot games for fun jackpot kako igrati Igralni avtomati brezplacno multilotto casino no deposit bonus
club sa casino no deposit bonus codes admiral casino kozina
NormanDaw
October 14, 2026, at 11:14 pmЭнгельс купить План (АФГАНКА) Фокино купить закладку Мефедрон [мелкие камни/мука] HQ
Курганинск купить закладку гидропонику Купить Кокаин, Марихуану, Бошки, Мефедрон Котельники купить закладку
Электросталь купить закладку MDMA Pills – ORANGE Губкин купить закладку Ecstasy: Yellow Stars 350 mg
limunsMiple
October 14, 2026, at 11:26 pmАнтикоррозийной защитой и кузовным ремонтом машин в Кирове с 2015 года занимается сервис на улице Воровского. Обработке подлежат днище, колесные арки и скрытые полости легковых машин, внедорожников, минивэнов и микроавтобусов. Ищете антикор арок автомобиля Киров? Перечень услуг и цены опубликованы на сайте kuzov-kirov.ru вместе с галереей работ. Материалы для обработки негорючие и не имеют запаха. На все работы дается письменная гарантия, каждый этап фиксируют на фото и видео, цены ниже среднерыночных.
NormanDaw
October 14, 2026, at 11:35 pmЧёрмоз купить Амфетамин Тосно купить Марихуана [Amnesia Haze]
Сосновка купить закладку MDMA Pills – BLUE Купить Кокаин, Марихуану, Бошки, Мефедрон Купить Амфетамин в Вилючинск
Дегтярск купить Afgan Kush Закладки MDMA в Полярном Зоре
MelvinJem
October 14, 2026, at 11:46 pmcasino bonus za registracijo Is there a trick to winning online slot machines
premier live casino casino bonus app real money Online igralnica 1win live casino
najboljЕЎe spletne igralnice casino igre za pravi denar brez vplaДЌila
NormanDaw
October 14, 2026, at 11:54 pmГубкинский купить закладку Марихуана [Girl Scout Cookies] Ираклион купить MDMA Pills
Бородино купить LSD Купить Кокаин, Марихуану, Бошки, Мефедрон Москва Измайлово Восточное купить закладку Кокаин
Белек купить Cocaine Premium HQ – печать Dolphin Москва ЗАО купить Кокаин Супер Качества [Ecuador]
MelvinJem
October 15, 2026, at 1:45 am365 online casino Does the €20 trick work in Vegas
888 casino no deposit free spins igre casino free WinShark Slovenija blackjack bet 365
zeus casino game book of ra symbol select buy bonus demo
MelvinJem
October 15, 2026, at 1:58 ameuroking online casino free download europa casino no deposit bonus codes
vegas strip casino no deposit bonus gametwist casino online Igralnica, ki sprejema Paysafecard gday casino no deposit bonus codes 2026
Еѕrebanje eurojackpot ura online casino no deposit bonus not on gamstop
KYMBERLYReiny
October 15, 2026, at 2:03 amhttps://intercom.help/bonuscode/nl/articles/16576205-best-lite-apk-betting-apps-for-low-end-phones-ranked
Keithbar
October 15, 2026, at 2:04 amhttps://intercom.help/bonuscode/sr/articles/17134981-melbet-current-promo-code-uganda-2026-max888-ush480-000
EXIEKEYMN
October 15, 2026, at 2:06 amhttps://intercom.help/bonuscode/nb/articles/17132151-1xbet-registration-code-today-south-africa-joinbet55-bonus-zar-5-000
NormanDaw
October 15, 2026, at 2:12 amХимки купить DMT Мертвое море купить Купить опиаты: героин, метадон, лирика, хмурый, мёд
Ленинск купить Мефедрон (миф) Купить Кокаин, Марихуану, Бошки, Мефедрон Ингушетия купить закладку Мескалин
Семёнов купить закладку Ecstasy: Yellow Homer 200mg АлуштаОспаривается купить Лирика 300мг (Прегабалин)
NormanDaw
October 15, 2026, at 2:34 amЗакладки лирика в Туране Майкоп купить бошки
Уссурийск купить закладку Ecstasy – Homer / Bart Купить Кокаин, Марихуану, Бошки, Мефедрон Коггала купить закладку Mephedrone: Мука HQ
Кемерово купить закладку Ecstasy: Yellow Homer 200mg Купить Гарисон Форд Ужур
MelvinJem
October 15, 2026, at 2:49 amlive casino app top online casinos europe
50 free spins no deposit 2026 book of ra game download for pc Bizzo casino Slovenija tropezia palace casino no deposit bonus
joy casino 250 free spins bonus codice bonus bet365
NormanDaw
October 15, 2026, at 2:52 amТутаев купить закладку Марихуана [Outstanding Kush] Закладки MDMA в Лакинске
Чифирь как заварить Купить Кокаин, Марихуану, Бошки, Мефедрон АрмянскОспаривается купить VHQ Cocaine 98,8% Ecuador
Чернушка купить закладку LSD-25 в марках 250мк КерчьОспаривается купить закладку Cтимуляторы
lixuderoxy
October 15, 2026, at 3:38 amИзбыточный вес, хроническая утомляемость и гормональные нарушения часто вызваны рационом, а не отсутствием воли. Ищете нутрициолог для похудения? Специалист по коррекции рациона и пищевых привычек Лидия Картавцева публикует на сайте il-li.ru понятные разборы без запугиваний и модных чисток кишечника. Статьи объясняют влияние еды на энергию, кожу, пищеварение, сон и вес простым языком и дают конкретные рекомендации для повседневного рациона каждой женщины.
rosgvardiy_ofsn
October 15, 2026, at 3:49 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана росгвардии цена.
Росгвардия занимается постоянной охраной важных государственных и частных объектов.
Bestchange
October 15, 2026, at 3:59 am[url=https://bestchange.com.co/]Find the best rate fast[/url]
MelvinJem
October 15, 2026, at 4:48 am21 dukes 25 free spins online casino to make money
burancasino free spins raging bull casino no deposit bonus codes Spletna igralnica s pravim denarjem 1 euro deposit casino
novo online casino casino bonus hunt
MelvinJem
October 15, 2026, at 5:00 amwhich online casino is best free poker cash no deposit needed
casino igre avtomati free 4 kings slots no deposit bonus codes Igraj avtomate brez placila iw casino online
best online casino bonus no deposit kazino igre book of ra
zepusamlog
October 15, 2026, at 5:00 amПокупка или продажа жилья в Подмосковье требует безупречной юридической точности, и агентство «Гарант Плюс», успешно работающее с 1998 года в Балашихе и Железнодорожном, выступает надежным проводником на этом рынке. Изучив актуальную базу проверенных объектов на https://garant-plus.ru/ – клиенты получают полное экспертное сопровождение любых сложных сделок с гарантией безопасности.
NormanDaw
October 15, 2026, at 5:10 amРославль купить Купить опиаты: героин, метадон, лирика, хмурый, мёд Карелия купить закладку Ecstasy: Red Stars 280 mg
Болгария купить закладку MDMA Pills Купить Кокаин, Марихуану, Бошки, Мефедрон Купить Амфетамин в Курильск
Яхрома купить Ecstasy Rolls Royce Москва Марьина роща купить закладку бошки
NormanDaw
October 15, 2026, at 5:32 amБелая Калитва купить закладку MDMA Pills Топки купить DMT
Амурская область купить закладку Ecstasy: Pink Heart 200mg Купить Кокаин, Марихуану, Бошки, Мефедрон Спайс порошок
Диамант перевод Малая Вишера купить Мефедрон [Cristalius 2.0]
NormanDaw
October 15, 2026, at 5:50 amКурчатов купить LSD-25 (HQ) 250мкг Луховицы купить закладку VHQ GanBang Cocaine 98% Peru
Борисоглебск купить Мефедрон [мелкие камни/мука] HQ Купить Кокаин, Марихуану, Бошки, Мефедрон Котельники купить закладку HQ Гашиш NO NAME
Нариманов купить Ecstasy: Yellow Homer 200mg купить онлайн закладку в Грайворон
MelvinJem
October 15, 2026, at 5:52 ambook of ra two symbols demo casino online free
besplatne casino igre za mobitel admiral casino tГЎbor Igralnica online za Slovenijo best casino game to win money
silver oak casino the bes online casino acept slovenia
MelvinJem
October 15, 2026, at 7:51 amstarburst casino free spins online live casino blackjack
bet365 login bonus code planet 7 casino no deposit bonus not expired reddit Spletni casino za Slovenijo euro dЕѕek pot slovenija
blackjack multihand vip casino korona kranjska gora program
MelvinJem
October 15, 2026, at 8:03 amnajboljЕЎe casino igre za pravi denar bet365 first deposit bonus
igre365 igre karte kazino casino admiral online Spletni casino v Sloveniji galabingo free spins code
book of ra deluxe free demo betvictor poker free 10
NormanDaw
October 15, 2026, at 8:09 amРеакция амфетамина Устюжна купить закладку Порох 999 (HQ) Афган
Морозовск купить Марихуана [Outstanding Kush] Купить Кокаин, Марихуану, Бошки, Мефедрон Марокканский гашиш цена
Звенигово купить Скорость a-pvp Рязань купить закладку MDMA Pills – BLUE
NormanDaw
October 15, 2026, at 8:31 amСенгилей купить закладку MDMA Pills – GREEN Шарыпово купить Ecstasy: Red Monkey 250mg
Ахтубинск купить закладку купить закладку опиаты: героин, метадон, лирика, хмурый, мёд Купить Кокаин, Марихуану, Бошки, Мефедрон Сухой Лог купить Cocaine Premium HQ – печать Dolphin
Приморско-Ахтарск купить LSD 220 mkg Закладки в Ростове-на-дону
Michaelseirm
October 15, 2026, at 8:49 amАлуштаОспаривается купить Molly: MDMA HQ Ишимбай купить закладку Ecstasy: Red Monkey 250mg
Сортавала купить MDMA Pills – RED Купить Кокаин, Марихуану, Бошки, Мефедрон Полярный купить закладку Амфетамин
Нижегородская область купить Триптамины Нескалин
CurtisExcic
October 15, 2026, at 8:54 amcasino bonus no deposit real money bet365 mobile casino
nj online casino largest online casino apollo slots casino free 1000 casino online demo
joint mobility support
October 15, 2026, at 9:47 amThis post explains well why warm-ups matters: it can help prepare the body for activity.
rosgvardiy_wasn
October 15, 2026, at 9:55 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, росгвардия пультовая охрана.
Росгвардия обеспечивает безопасность на объектах различных категорий, от промышленных предприятий до жилых районов.
CurtisExcic
October 15, 2026, at 10:54 amonline casino affiliate earnings casino slovenia online casino
casino rewards member casino gaming club casino no deposit bonus codes grand wild casino no deposit bonus codes casino slovenia lubiana
CurtisExcic
October 15, 2026, at 11:06 amblackjack game online casino in slovenia
euroking online casino download korona casino hotel kranjska gora slovenia online casinos slovenia funclub casino no deposit bonus codes
Michaelseirm
October 15, 2026, at 11:07 amАзалептин и алкоголь последствия Закладки марки в Калач-на-доне
Жуковка купить Ecstasy Купить Кокаин, Марихуану, Бошки, Мефедрон Калужская область купить закладку VHQ GanBang Cocaine 98% Peru
Щигры купить закладку NBOME Москва СЗАО купить Метадон, чистота 99%
SINAAvoip
October 15, 2026, at 11:13 amhttps://intercom.help/bonuscode/ro/articles/17142801-melbet-promo-code-ghana-max888-130
Edwardwhemn
October 15, 2026, at 11:14 amhttps://intercom.help/bonuscode/ru/articles/17132156-registration-code-registration-1xbet-tajikistan-2026-joinbet55-bonus-130
YASMINEdal
October 15, 2026, at 11:14 amhttps://intercom.help/bonuscode/sl/articles/17122809-mostbet-promocode-aktuelles-angebot-prufen-2026-most888-bonus-300-usd
MILAmeert
October 15, 2026, at 11:15 amhttps://intercom.help/bonuscode/pt/articles/17131314-1xbet-promo-code-casino-iran-joinbet55-bonus-130
NATIVIDADTus
October 15, 2026, at 11:17 amhttps://intercom.help/bonuscode/pt-BR/articles/17129963-1xbet-msimbo-wa-promo-dau-la-bure-uganda-joinbet55-bonasi-ugx-1-000-000
LASHONDAReiny
October 15, 2026, at 11:17 amhttps://intercom.help/bonuscode/nl/articles/17025920-नेपालमा-1xbet-डिपोजिट-अफर-2026-joinbet55
LIZpeR
October 15, 2026, at 11:19 amhttps://intercom.help/bonuscode/pl/articles/17187409-1xslots-cyprus-ОµО»О»О·ОЅО№ОєО¬-first-deposit-offer-2026-btc777-450-30-free-spins
Ethanter
October 15, 2026, at 11:21 amA genuinely unexpected highlight of my reading week, and a look at lemoncovecommerceatelier extended that pattern, the surprise of finding excellent content rather than the predictable mediocre is one of the few real pleasures of casual web browsing and this site delivered that surprise cleanly today which I really do appreciate.
Michaelseirm
October 15, 2026, at 11:29 amстаф в Электрогорск Губкин купить Ecstasy: UPS 280mg
Миксы с амфетамином Купить Кокаин, Марихуану, Бошки, Мефедрон Циклодол трип
Онега купить Кокаин HQ Жуков купить закладку Героин ОПТ
Nathanagerb
October 15, 2026, at 11:29 amQuietly enjoying that I have found a new site to follow for the topic, and a look at dunestonegalleria reinforced the small pleasure of the find, the discovery of new high quality sources is one of the more durable pleasures of careful internet reading and this site has been generating that discovery pleasure at multiple points already today.
FREDRICKAKEYMN
October 15, 2026, at 11:32 amhttps://intercom.help/bonuscode/nb/articles/17150678-1xbit-promo-code-today-finland-2026-btc777-bonus-7-btc
Michaelseirm
October 15, 2026, at 11:47 amРязань купить MDMA таблетки Дятьково купить АК-47 – Бошки Шишки
Геленджик купить закладку MDMA Pills – ORANGE Купить Кокаин, Марихуану, Бошки, Мефедрон Покачи купить Кристаллы соль
Великий Новгород купить Амфетамин Сульфат белый Алдан купить Порох 999 (HQ) Афган
RichardWaype
October 15, 2026, at 11:55 amChoosing the right lawyer is seldom easy — particularly at a moment when you’re facing a lawsuit, a DUI arrest or a family dispute. That is exactly why [url=”http://www.connectingonline.com.ar/Site/Click.aspx?t=c&e=5489&sm=0&c=12441&cs=4j2e2a4a&url=https://law-firms-in.com/location/irvine/real-estate-law/”]the lawyer directory Law Firms In[/url] is organized around a single idea: begin with your legal problem, and then pick your state and your city. Every practice area page shows the lawyers who work in that field, while the practice pages of [url=”http://vcard.vqr.mx/ios_download_info.php?origin=vqr.mx&v_card_name=Imre_Gabnai.vcf&name=Imre&last_name=Gabnai&email=gabnai.imre@gmail.com&tel=&company=Riglersystem&title=SoftwareEngineer&url=https://law-firms-in.com/location/louisville/workers-compensation/34zxVq8″]Law Firms In[/url] span personal injury, family law, criminal defense and estate planning.
The reach of [url=”https://www.google.co.uz/url?sa=t&rct=j&q=&esrc=s&source=web&cd=15&url=https://law-firms-in.com/location/lakeland/business-law/”]Law-Firms-In.com[/url] speaks for itself: 14,000+ attorney profiles in 22 states, over 2,000 cities with their own local pages and nearly 2,400 city-and-practice pages. From California and New York to Texas and Florida, [url=”http://www.sale-notebook.com/change_language.asp?language_id=th&MemberSite_session=site_125224_&link=https://law-firms-in.com/location/mesa/divorce/”]Law Firms In[/url] lets you find legal help nearby in a few clicks.
What truly sets [url=”https://imptrack.intoday.in/click_tracker.php?domain=AT&clientCode=501561&k=https://law-firms-in.com/location/oakland/workers-compensation/”]Law Firms In[/url] apart remains transparency. Profiles are compiled from open law firm and bar data, not from sponsored listings — nobody buys a better ranking. Each listing is tied to a real city and an area of law, so a search brings up lawyers who actually work in that field of law nearby. Equally important, a city-and-practice page on [url=https://ramset.com.au/Document/Url/?url=https://law-firms-in.com/location/fort-worth/domestic-violence/]the Law Firms In attorney finder[/url] goes live only when at least five attorneys match it, while the directory index is regenerated each night — meaning counts, local pages and practice listings consistently reflect current data instead of a yearly snapshot.
For clients in need of a lawyer, [url=http://lastapasdelola.com/?URL=https://law-firms-in.com/location/white-plains/medical-malpractice/]the Law Firms In legal directory[/url] operates in three simple steps: find by legal issue and city, look through local profiles in that city, then call or write to the firm directly. The platform takes no commission and requires no sign-up. For attorneys, the approach is equally transparent: add your listing with city and practice areas, show up on the local pages you actually work in, and receive inquiries directly from your own profile on [url=https://www.thebarefootrunners.org/proxy.php?link=https://law-firms-in.com/location/los-angeles/real-estate-law/]Law Firms In[/url] — without any lead resale in between.
In addition to listings, [url=http://www.ausalbisteak.com/m/news/sh/detalle.aspx?url=https://law-firms-in.com/location/birmingham/civil-rights/]Law Firms In[/url] also offers daily legal news together with a Legal FAQ: Supreme Court decisions, new regulations and other state-by-state updates help visitors stay ahead even before they need a lawyer. All in all, [url=http://mr-wheels.ru/bitrix/redirect.php?goto=https://law-firms-in.com/location/ithaca/estate-planning/]Law Firms In[/url] remains the kind of resource visitors come back to every time a legal issue appears — at no cost, independent and always focused on your local community.
CurtisExcic
October 15, 2026, at 11:58 amcasino on bet365 slot igre free
casino carnevale slovenia prenocisce casino bled slotty vegas casino 5 min deposit online casinos
Levisip
October 15, 2026, at 12:15 pmReading this between meetings turned out to be the most useful thing I did all afternoon, and a stop at cottonmeadowoutpost kept that productivity feeling going, content can sometimes outperform actual work in terms of what gets accomplished mentally and this site managed that today which is genuinely a high bar to clear consistently.
SHANELAvoip
October 15, 2026, at 1:47 pmhttps://intercom.help/bonuscode/ro/articles/17130634-1xbet-code-promo-conditions-de-mise-depot-belgium-joinbet55-bonus-130
MIRTAmeert
October 15, 2026, at 1:50 pmhttps://intercom.help/bonuscode/pt/articles/17135452-melbet-promo-code-list-today-max888-3-500-zmw
YAHAIRAdal
October 15, 2026, at 1:50 pmhttps://intercom.help/bonuscode/sl/articles/17199083-888starz-casino-bonus-koda-slovenija-2026-cash888-130-eur
LAIReiny
October 15, 2026, at 1:51 pmhttps://intercom.help/bonuscode/nl/articles/17025830-дёе›Ѕ1xbetй¦–ж¬Ўе款奖金2026-joinbet55
MARDELLpeR
October 15, 2026, at 1:56 pmhttps://intercom.help/bonuscode/pl/articles/17034703-melbet-а¦Є-রোমো-কোড-а¦а¦ѕа¦°а¦¤-2026-wap200-а¦Є-রোমো-কোডের-সারাংশ
ElbertCRUTH
October 15, 2026, at 1:58 pmdiamond world casino no deposit bonus codes jackpot kako igrati
4 kings slots no deposit bonus codes free online casino bwin live poker casino bonus codes no deposit
Michaelseirm
October 15, 2026, at 2:06 pmКарачев купить наркотики экстази вы действительно хотите повеселиться
Владимирская область купить METHADONE Купить Кокаин, Марихуану, Бошки, Мефедрон Москва Чертаново Северное купить закладку MDMA Pills – GREEN
Отрадный купить Гашиш [Euro Cube] Череповец купить закладку VHQ Cocaine 98,8% Ecuador
INGEKEYMN
October 15, 2026, at 2:09 pmhttps://intercom.help/bonuscode/nb/articles/17151673-1xbit-promo-code-guyana-btc777-bonus-7-btc
ElbertCRUTH
October 15, 2026, at 2:10 pmnagradne igre za denar casino fortuna slovenia
blackjack not gambling 25 euro no deposit bonus book of ra symbols surf casino no deposit bonus
Michaelseirm
October 15, 2026, at 2:46 pmБогданович купить закладку Мефедрон купить закладку Лучший эйфоретик Баймак купить Мефедрон [Cristalius 2.0]
Купить Кристалы в Славске Купить Кокаин, Марихуану, Бошки, Мефедрон Астрахань купить закладку Психоделики
Азнакаево купить План (АФГАНКА) Мытищи купить NBOME
GregoryEmish
October 15, 2026, at 3:02 pm[url=https://debt-market.ru/]IT аутстаффинг[/url]
ElbertCRUTH
October 15, 2026, at 3:03 pmfree casino games slovenija win free spins pop up
energy casino no deposit bonus live dealer casinos live games casino slovenija Which gambling sites give free bonuses
JadonPaumb
October 15, 2026, at 3:28 pmWalked away in a slightly better mood than when I started reading, that says something about the writing, and a stop at junipercovevault kept that going, content that leaves you feeling more capable rather than overwhelmed is the kind I keep coming back to again and again over the years and across many topics.
vnxa88
October 15, 2026, at 3:34 pmThe variety of options here is impressive. I love how easy it is to navigate the site on my phone. Definitely giving five stars to vnxa88 for the great service.
ElbertCRUTH
October 15, 2026, at 5:01 pmcasino 1e deposit 2026 casino bonus
betroadhousereels casino no deposit free spin napoli casino no deposit bonus codes blackjack kako se igra casino register bonus slovenija
Michaelseirm
October 15, 2026, at 5:03 pmТайга купить закладку АК-47 – Бошки Шишки Кувшиново купить закладку Ecstasy
Сурск купить MDPV Купить Кокаин, Марихуану, Бошки, Мефедрон Урай купить закладку MDMA Crystal [Import]
Иланский купить шишки Верхний Тагил купить закладку VHQ GanBang Cocaine 98% Peru
ElbertCRUTH
October 15, 2026, at 5:14 pmspletna igralnica hit casino live william hill
unibet live casino slovenska spletna igralnica spinia casino no deposit bonus besplatne casino igre gaminator
Michaelseirm
October 15, 2026, at 5:25 pmэкстази 1999 торрент Прозак в беларуси
Москва Марфино купить Мескалин Купить Кокаин, Марихуану, Бошки, Мефедрон Купить легальные наркотики
Плавск купить АК-47 – Бошки Шишки Андреаполь купить Шишки White Widow
Michaelseirm
October 15, 2026, at 5:43 pmПоронайск купить закладку Гашиш [Euro Cube] Стаф в Петушке
Лабытнанги купить Марки LSD 170мкг Купить Кокаин, Марихуану, Бошки, Мефедрон Алтайский край купить закладку Гидропоника Afgan Kush
Лангепас купить Героин в камнях Нижнеудинск купить Cocaine HQ
ElbertCRUTH
October 15, 2026, at 6:06 pmbrezplacne guru igre casino grand kazino bonus
royal vegas online casino barbados casino online bet365 app android no bonus deposit casinos
JosephFoP
October 15, 2026, at 7:07 pmقتل عبر gooobet
Michaelseirm
October 15, 2026, at 8:01 pmКуса купить закладку MDMA Pills – BLUE Ярцево купить Мефедрон [мелкие камни/мука] HQ
Чухлома купить закладку Метадон HQ Купить Кокаин, Марихуану, Бошки, Мефедрон Кизел купить HQ Гашиш NO NAME
Терек купить Cocaine HQ Балашиха купить Марихуана [White Widow]
ElbertCRUTH
October 15, 2026, at 8:04 pmlord of ocean online casino casino games free slots online
igre casino roulette tropezia palace casino no deposit bonus miami casino online casino besplatne igre 24
Williamnuava
October 15, 2026, at 8:13 pmVeloraCasino рабочее зеркало
?
Когда меняется дизайн сайта Velora Casino, многие думают, что попали на подделку; но если вы заходите через официальный тг?канал, вы всегда уверены, что домен и интерфейс подтверждены самим брендом и не связаны с мошенниками.
ElbertCRUTH
October 15, 2026, at 8:17 pmcasino games slots free no download casino bled vrednost zetona 100 lir
hit kranjska gora casino kontakt grand kazino bonus bet-at-home slovenija download hit casino korona kranjska gora
Michaelseirm
October 15, 2026, at 8:22 pmНижнеудинск купить закладку HQ Гашиш закладки наркотиков в Березники
Закладки спайс в Волгореченске Купить Кокаин, Марихуану, Бошки, Мефедрон Лечим воспаление бартолиновой железы дома
Лабинск купить закладку Марихуана [Amnesia Haze] Владивосток купить закладку Чистейший кокаин 98%
Michaelseirm
October 15, 2026, at 8:41 pmкупить онлайн закладку в Долинск Сальск купить закладку Cocaine Premium: Peru
Куса купить закладку MDMA Pills – ORANGE Купить Кокаин, Марихуану, Бошки, Мефедрон Луза купить закладку HQ Гашиш NO NAME
Ухта купить закладку Мефедрон (миф) Омск купить закладку VHQ Cocaine 98,8% Ecuador
Williamnuava
October 15, 2026, at 9:05 pmVeloraCasino зеркало на сегодня
?
Многие ищут apk?клиент Velora Casino через сторонние файлопомойки, но безопаснее использовать только ссылку из телеграм?канала; там же есть инструкция по проверке контрольной суммы файла, чтобы убедиться, что apk не был подменён.
DavidRurry
October 15, 2026, at 9:07 pminteresting post
_________________
[url=https://sportbonustop.today/auf-casino/]АУФ Казино[/url]
Kevinher
October 15, 2026, at 9:08 pmkaramba free spins wildblaster casino no deposit bonus code
iw casino online online casino free bonus no deposit book of ra magic slot demo twist casino no deposit bonus codes 2026
tazusamwer
October 15, 2026, at 9:34 pmБесперебойность промышленных линий требует надежных компонентов и точных инженерных расчетов. С 2003 года компания «ИРИМЭКС» обеспечивает заводы передовой трубопроводной арматурой, насосами и компенсаторами. На портале https://www.irimex.ru/ представлен колоссальный каталог решений для нефтегазового сектора и энергетики. Профессиональный аудит и прямые поставки гарантируют вашему проекту безаварийную эксплуатацию.
Gregorystaic
October 15, 2026, at 9:39 pmignition casino no deposit bonus book of ra two symbols demo
free casino bonus no deposit online casino bonuses live casino top 10 casino admiral rtp
Gregorystaic
October 15, 2026, at 9:47 pmslovenske casino online casino stream online
best online casino no deposit bonus flamantis casino no deposit free spins 2026 casino slovenia lubiana joo casino bonus codes
Williamnuava
October 15, 2026, at 9:58 pmвелора играть
?
С тех пор как я закрепил канал Velora Casino вверху списка чатов, забытые пароли и битые ссылки перестали быть проблемой – всё нужное всегда под одним тапом.
Williamnuava
October 15, 2026, at 10:50 pmVeloraCasino актуальное зеркало
?
Иногда в канале появляются мини?обзоры слотов, которые лучше отыгрывают бонусы; для тех, кто гоняется за фриспинами, это полезнее, чем общие статьи на сайтах.
Denniscig
October 15, 2026, at 10:51 pmСвердловская область купить закладку Героин в камнях Гуково купить закладку Героин натуральный
Нея купить LSD 220 mkg Купить Кокаин, Марихуану, Бошки, Мефедрон Волжский купить Cтимуляторы
Отрадный купить закладку Метадон HQ Сусуман купить Mephedrone (4mmc, мяу)
Denniscig
October 15, 2026, at 11:43 pmИзобильный купить Мефедрон [Cristalius 2.0] Попперс | поиск объявлений во всех категориях
Мелеуз купить Ecstasy: UPS 280mg Купить Кокаин, Марихуану, Бошки, Мефедрон Купить Амфетамин в Карасук
Холмск купить закладку Mephedrone (4mmc, мяу) Усть-Лабинск купить закладку Ecstasy: Pink Heart 200mg
Williamnuava
October 15, 2026, at 11:46 pmВелора казино рабочее зеркало
?
Из плюсов канала – видно, когда люди реально жалуются на задержки выплат, а не когда отзывы пишут сами маркетологи; можно оценить, стоит ли сейчас рисковать крупным депозитом.
Gregorystaic
October 15, 2026, at 11:52 pmpoker free software limoplay casino no deposit bonus codes
casino admiral colosseum besplatne casino igre book of ra rop casino kranjska gora book of ra deluxe online
Denniscig
October 15, 2026, at 11:54 pmСорочинск купить закладку Amphetamine Мамоново купить закладку Шишки HQ АК47
Дивногорск купить закладку VHQ Cocaine 98,8% Ecuador Купить Кокаин, Марихуану, Бошки, Мефедрон купить закладку в Любань
Томари купить эйфоретик Мефедрон Москва Нагорный купить закладку METHADONE
Gregorystaic
October 16, 2026, at 12:52 amfake casino online the truth about online casinos
no deposit bonus casino free spins book of ra garminator best online casino for europ player house of fun free spins
Gregorystaic
October 16, 2026, at 1:00 ammarko baruca casino admiral besplatne casino igre za igranje
free welcome bonus casino no deposit ruleta v zivo casino online bonus online casino europe
Williamnuava
October 16, 2026, at 1:13 amВелора казино ссылка
?
Зеркала Велора казино часто разносятся по форумам случайными пользователями, но официальная версия всегда одна — в телеграм?канале; там же можно пожаловаться, если вы увидели фишинговый домен, и модераторы предупредят остальных.
rosgvardiy_lmsn
October 16, 2026, at 1:22 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, вневедомственная охрана цена.
Деятельность Росгвардии обеспечивает защиту имущества и сохранность важных объектов по всей стране.
Denniscig
October 16, 2026, at 1:58 amКупить россыпь в Нижнем Серги-3 Ишимбай купить закладку Ecstasy: Yellow Stars 350 mg
Дубаи купить закладку VHQ GanBang Cocaine 98% Peru Купить Кокаин, Марихуану, Бошки, Мефедрон Находка купить Ecstasy – UPS
Сураж купить закладку эйфоретик MDMA Таба купить закладку MDMA Pills – RED
Denniscig
October 16, 2026, at 2:50 amКрасноперекопскОспаривается купить закладку Amphetamine Волгореченск купить Amphetamine
Курчатов купить Cтимуляторы Купить Кокаин, Марихуану, Бошки, Мефедрон Тулун купить NBOME
Хилок купить закладку METHADONE Марихуану в Самаре
Denniscig
October 16, 2026, at 3:01 amГудермес купить закладку Amphetamine Сурск купить закладку Гашиш [LV]
Телеграмм ск закладки Купить Кокаин, Марихуану, Бошки, Мефедрон Галич купить Mephedrone: Мука HQ
Петровск купить закладку NBOME Люберцы купить Марихуана [Outstanding Kush]
Gregorystaic
October 16, 2026, at 3:04 amlive casino slot machines live casino dealer
ruleta namizna igra casino rewards vip 888 poker how to get 88 free casino brezplaДЌne igre
Cartermouro
October 16, 2026, at 3:57 amBookmark earned, calendar reminder set, share queued, all from one good post, and a look at baycovecommerceatelier did the same, when a single reading session triggers multiple downstream actions you know the content has actually moved me beyond the page and this site is moving me at that higher level reliably.
Gregorystaic
October 16, 2026, at 4:05 ampontoon vs blackjack Can I win real money from an online casino
free online slot machines black diamon 25 free spins casino drive in kulinarika bonus 5 €
LITApeR
October 16, 2026, at 4:05 amhttps://intercom.help/bonuscode/tl/articles/17139457-к°Ђмћ…-мЅ”л“њ-melbet-мЉ¤нЏ¬мё -лЊЂн•њлЇјкµ-mel200big-ліґл„€мЉ¤-130
Edwardwhemn
October 16, 2026, at 4:07 amhttps://intercom.help/bonuscode/vi/articles/17137209-today-melbet-promo-code-2026-max888-225-000-mwk
Kalekeddy
October 16, 2026, at 4:07 amHonest take is that I will probably forget most of what I read online today but this post is one I will remember, and a stop at mintorchardtrading kept that same memorable quality going, certain writing leaves a residue in the mind in a way most content simply does not manage.
Gregorystaic
October 16, 2026, at 4:12 amcasino korona kranjska gora Г¶ffnungszeiten casino igre avtomati
most trusted online casino in slovenia unibet live roulette free vegas casino slots book of ra download
TrentMuh
October 16, 2026, at 4:59 amA piece that respected the reader by not over explaining the obvious, and a look at orchardharbortrading continued that calibrated approach, finding the right level of explanation is one of the harder editorial calls and this site has clearly thought carefully about what readers will already know versus what they need help with consistently.
Denniscig
October 16, 2026, at 5:05 amСевероуральск купить Амфетамин (фен) Карпинск купить Героин ОПТ
Урень купить закладку Гашиш [AB] Купить Кокаин, Марихуану, Бошки, Мефедрон Московская область купить закладку Гашиш [LV]
Москва Лианозово купить закладку купить закладку опиаты: героин, метадон, лирика, хмурый, мёд Аганин виктор лукоянов
Denniscig
October 16, 2026, at 5:56 amСкотобаза открыть в обход блокировки Мончегорск купить Героин в камнях
Николаевск купить MQ Cocaine Mexico Купить Кокаин, Марихуану, Бошки, Мефедрон Воркута купить закладку VHQ Cocaine 98% Bolivia
Нововоронеж купить закладку Амфетамин Чита купить эйфоретик MDMA
Gregorystaic
October 16, 2026, at 6:17 amWhich casinos offer the best spin free poker igre online free
live casino reviews big 5 casino no deposit bonus bet 365 kopija vozniЕЎkega dovoljenja casino 10 euro no deposit bonus
Gregorystaic
October 16, 2026, at 7:17 am20 free spins starburst no deposit casino bonus game
black diamon 25 free spins blackjack hands chart best online casino bonus free offline casino pc games
Charlesdaugh
October 16, 2026, at 7:23 amhttps://www.bmw.ru/
Gregorystaic
October 16, 2026, at 7:25 ame stave stavna lista 21 blackjack online
poker side free bonus no deposit bet365 bonus slovenija casino kozina slovenia 120 free spins weekly cashback
rosgvardiy_ygsn
October 16, 2026, at 7:44 amРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, охрана росгвардии.
В целом, деятельность Росгвардии в области охраны объектов обладает высокой важностью для стабильности страны.
Denniscig
October 16, 2026, at 8:11 amКупить Хмурь Теберда Сорск купить Героин ОПТ
Приморский край купить закладку Cocaine HQ Купить Кокаин, Марихуану, Бошки, Мефедрон купить клад Бентота
Гусиноозёрск купить Купить опиаты: героин, метадон, лирика, хмурый, мёд сколько стоит 1 гр гашиша
eye health supplements
October 16, 2026, at 8:35 amYour explanation of blinking while using screens is easy to follow.
Henrypeevy
October 16, 2026, at 8:42 amЕсли интересует [url=https://kwork.ru/e-commerce-social-network/55108762/dizayn-kartochki-tovara-infografika-dlya-marketpleysa-wildberries]инфографика карточки для ВБ Кворк[/url] – это отличная возможность выделить товар среди конкурентов, показать его преимущества и повысить интерес покупателей. Разрабатываю современную инфографику, подбираю композицию, шрифты и визуальные акценты с учетом особенностей товара. Карточка получается понятной, привлекательной и ориентированной на продажи.
Denniscig
October 16, 2026, at 9:04 amВерхний Уфалей купить закладку Amphetamine Орехово-Зуево купить MDMA Pills – GREEN
Тогучин купить Мефедрон в мелких камнях/муке Купить Кокаин, Марихуану, Бошки, Мефедрон Закладки бошки в Людинове
Доминикана кокаин Талица купить Cocaine Premium: Peru
Denniscig
October 16, 2026, at 9:15 amЗаволжье купить Марихуана [White Widow] Астраханская область купить закладку эйфоретик MDMA
Бор купить MQ Cocaine Mexico Купить Кокаин, Марихуану, Бошки, Мефедрон Шарыпово купить LSD-25 (HQ) 170мкг
Куровское купить MDMA Crystal [Import] купить онлайн закладку в Окуловка
Gregorystaic
October 16, 2026, at 9:31 amWhat happens if you win €100,000 at a casino book of ra magic
online casino slovensko blackjack vs baccarat slovenian online casino superlenny casino no deposit free spin
Bobbymop
October 16, 2026, at 9:49 amКизилюрт купить Метадон HQ Козьмодемьянск купить Мефедрон [Кристаллы]
Венеция купить марихуану Купить Кокаин, Марихуану, Бошки, Мефедрон Навашино купить закладку Метадон VHQ
Москва Останкинский купить Амфетамин Стародуб купить закладку Амфетамин (фен)
Jamesbup
October 16, 2026, at 9:57 amВсем здравствуйте! Пара слов про отзывы о драгонмани. Мифов на этот счёт много. Если коротко: жалобы на вывод чаще всего про незакрытый вейджер, а не про обман. Подробно разобрано здесь: [url=https://dragonmoney-review.org]отзывы РёРіСЂРѕРєРѕРІ dragon money[/url]. Вопрос ко всем: писали когда-нибудь отзыв сами? На этом всё!
JosephFoP
October 16, 2026, at 10:12 amشراء أسلحة
MichaelFonge
October 16, 2026, at 10:26 ammiss casino bled kristina What is the golden rule of gambling
huge casino free chips making money of online casinos bet365 deposit bonus captain cooks casino
JosephFoP
October 16, 2026, at 10:47 amاحتيال
Bobbymop
October 16, 2026, at 11:13 amКумертау купить закладку Амфетамин Сульфат белый Касли купить закладку Метадон, чистота 99%
Липецкая область купить закладку Ecstasy Rolls Royce Купить Кокаин, Марихуану, Бошки, Мефедрон как действует амфетамин на организм
Геленджик купить закладку MQ Cocaine Mexico Хлорангидрид уксусной кислоты
MichaelFonge
October 16, 2026, at 11:21 ampoker igre za denar rtg casinos online free spins
book ra online brezplacne guru igre casino online casino real money cool cat casino no deposit bonus codes
gazobneham
October 16, 2026, at 11:31 amЗаконные услуги кибербезопасности помогают защитить аккаунты, проверить системы с согласия владельца и восстановить доступ к собственным данным. Ищете услуги профессионального хакера? Подробная информация о консультациях и разрешённом аудите размещена на xakerplus.com/threads/predlozhenie-uslug-xakera-vzlom-pochty-socialnyx-setej-i-drugie-xakerskie-uslugi-perechen-uslug-gorazdo-bolshe-pishite.13025/ Все работы выполняются конфиденциально, после согласования задачи и исключительно в правовом поле.
JosephFoP
October 16, 2026, at 12:09 pmشراء مواد غير مشروعة عبر gooobet
Bobbymop
October 16, 2026, at 12:28 pmСамара купить Cтимуляторы Чебаркуль купить закладку Амфетамин
Аткарск купить закладку гашиш Купить Кокаин, Марихуану, Бошки, Мефедрон Моршанск купить MDMA Pills
Троицк купить закладку Мефедрон (миф) Севастополь купить закладку эйфоретик MDMA
MichaelFonge
October 16, 2026, at 12:30 pmbook of ra games online free captain jack casino free 500
kazino book of ra best games to play at casino najboljЕЎe igre za denar book of ra deluxe demo
Bobbymop
October 16, 2026, at 12:40 pmМежгорье купить закладку Мефедрон купить закладку Лучший эйфоретик Североморск купить Мефедрон (миф)
Гудермес купить Гашиш [LV] Купить Кокаин, Марихуану, Бошки, Мефедрон амфетамин гей
Кировград купить закладку Ecstasy: Yellow Homer 200mg Венёв купить закладку купить закладку опиаты: героин, метадон, лирика, хмурый, мёд
MichaelFonge
October 16, 2026, at 12:52 pmbest online casino no deposit bonus casino igre book of ra
blackjack pragmatic play springbok online casino deposit bonus codes How to play gambling games without money live casino uk real money
Bobbymop
October 16, 2026, at 1:03 pmКупить закладки лирика в Джанкойоспаривается Ефремов купить Cocaine Premium: Peru
закладки наркотиков в Янаул Купить Кокаин, Марихуану, Бошки, Мефедрон Купино купить закладку АК-47 – Бошки Шишки
Венеция купить закладку Марихуана [White Widow] Тара купить закладку Мефедрон в мелких камнях/муке
RONNAAvoip
October 16, 2026, at 1:31 pmhttps://intercom.help/bonuscode/uz/articles/17026618-1xbet-промокод-2026-пакет-казино-1-950-часті-запитання
NUTus
October 16, 2026, at 1:31 pmhttps://intercom.help/bonuscode/uk/articles/17128543-oficjalny-kod-promocyjny-mostbet-poland-most888-bonus-550-pln
JosephFoP
October 16, 2026, at 1:39 pmعملية احتيال gooobet
NANNIEmeert
October 16, 2026, at 1:40 pmhttps://intercom.help/bonuscode/tl/articles/17017899-ЩѓЩ€ШЇ-ШЄШіШ¬ЩЉЩ„-1xbet-ЩЃЩЉ-Ш§Щ„ШµЩ€Щ…Ш§Щ„-2027-joinbet55-ШЁЩ€Щ†Шµ-Ш§Щ„ШШіШ§ШЁ-Ш§Щ„Ш¬ШЇЩЉШЇ
LANORAReiny
October 16, 2026, at 1:44 pmhttps://intercom.help/bonuscode/nl/articles/17155323-codigo-promocional-betandyou-australia-2026-big777-bonus-de-100-ate-150
MichaelFonge
October 16, 2026, at 1:44 pmhit casino kranjska gora restaurant casino igre gratis
hopa casino online deposit free spins zodiac casino pc blackjack hit table
LINETTEpeR
October 16, 2026, at 1:56 pmhttps://intercom.help/bonuscode/tl/articles/17035940-melbet-bonus-dobrodoslice-srbija-wap200
JosephFoP
October 16, 2026, at 2:08 pmاحتيال gooobet
Bobbymop
October 16, 2026, at 2:26 pmБодайбо купить марихуану Москва Тёплый Стан купить закладку Ecstasy: Red Bull 200 mg
купить стаф Москва Люблино Купить Кокаин, Марихуану, Бошки, Мефедрон Западная Двина купить закладку АК-47 – Бошки Шишки
Белая Калитва купить закладку LSD-25 в марках 250мк Тольятти купить закладку Мефедрон (миф)
Henrypeevy
October 16, 2026, at 2:26 pmЕсли интересует [url=https://kwork.ru/e-commerce-social-network/55108762/dizayn-kartochki-tovara-infografika-dlya-marketpleysa-wildberries]разработка инфографики для маркетплейса ВБ Кворк[/url] – это отличная возможность выделить товар среди конкурентов, показать его преимущества и повысить интерес покупателей. Разрабатываю современную инфографику, подбираю композицию, шрифты и визуальные акценты с учетом особенностей товара. Карточка получается понятной, привлекательной и ориентированной на продажи.
MichaelFonge
October 16, 2026, at 2:41 pmslovenia online casino real money casino free igre
hotel kranjska gora hit casino casino igre za pravi denar brez vplacila jackpot city casino big win free spins no deposit 2026
rosgvardiy_iusn
October 16, 2026, at 2:52 pmРосгвардия охрана объектов — это надежное решение для обеспечения безопасности вашей собственности, росгвардия вневедомственная охрана росгвардии.
Охрана объектов невозможна без регулярного контроля и профилактических мероприятий Росгвардии.
JosephFoP
October 16, 2026, at 3:06 pmاحتيال gooobet
MichaelSow
October 16, 2026, at 3:41 pmБоровичи купить Ecstasy: Red Stars 280 mg Томск купить Afgan Kush
Починок купить закладку Мефедрон 2.0] Купить Кокаин, Марихуану, Бошки, Мефедрон Москва ЮАО купить закладку Марки LSD 170мкг
Южно-Сухокумск купить закладку Гашиш Окуловка купить Метадон (HQ) Германия
MichaelFonge
October 16, 2026, at 3:50 pmbet online casino lovenia zodiac casino forum slovenija
book of ra rizk casino bonus dobrodoslice bez depozita kazino igre besplatno admiral hotel casino kozina
MichaelSow
October 16, 2026, at 3:54 pmКатайск купить Гашиш [Soft Hash] Новоуральск купить Ecstasy Rolls Royce
Франция купить Amphetamine Купить Кокаин, Марихуану, Бошки, Мефедрон Харовск купить закладку Метадон HQ
Багратионовск купить закладку Мефедрон в мелких камнях/муке Городец купить закладку Cocaine Premium: Peru
JosephFoP
October 16, 2026, at 4:02 pmاحتيال gooobet
MichaelFonge
October 16, 2026, at 4:13 pmslots games no deposit bonus online casino free spins
free casino games on net online blackjack real money grand theft auto online casino rocket spletne casino igre
Jamesbep
October 16, 2026, at 4:14 pmbrezplaДЌne igre na avtomatih – casino video igre
SERINAAvoip
October 16, 2026, at 4:14 pmhttps://intercom.help/bonuscode/uz/articles/17151131-1xbit-promo-code-sz-2026-btc777-bonus-7-btc
MichaelSow
October 16, 2026, at 4:15 pmГаврилов-Ям купить Гашиш [LV] Таиланд купить закладку Триптамины
Закладки кокаин в Кызыле Купить Кокаин, Марихуану, Бошки, Мефедрон Приозерск купить MQ Cocaine Mexico
Абаза купить Кристаллы соль Красный Кут закладки
RANAETus
October 16, 2026, at 4:17 pmhttps://intercom.help/bonuscode/uk/articles/17123221-mostbet-kampanjekode-norway-2026-most888-bonus-400-eur
ELLANFag
October 16, 2026, at 4:18 pmhttps://intercom.help/bonuscode/th/articles/16572757-how-to-think-about-avoiding-chasing-losses
GREGORIAKEYMN
October 16, 2026, at 4:20 pmhttps://intercom.help/bonuscode/sr/articles/17131053-1xbet-slot-promo-code-ghana-2026-joinbet55-bonus-gh-800
Jamesbep
October 16, 2026, at 4:22 pmonline casino for eu – bet365 bonus code for existing customers
MILLYmeert
October 16, 2026, at 4:29 pmhttps://intercom.help/bonuscode/tl/articles/17144953-e-preciso-fazer-o-primeiro-deposito-para-o-bonus-melbet-em-cabo-verde
LAWANDAReiny
October 16, 2026, at 4:36 pmhttps://intercom.help/bonuscode/nl/articles/17136239-б‹Ёmelbet-ማስተዋወቂያ-бЉ®б‹µ-እንዴት-б€›бЊЌбЉб‰µ-б‹б‰»б€‹б€Ќ-የማንነት-б€›б€ЁбЊ‹бЊ€бЊ«-ትбЉбЉб€€бЉ›-б€ќб‹ќбЊ€б‰Ј-max888-17-000-etb
MichaelFonge
October 16, 2026, at 5:05 pmbook of ra deluxe slot perfect pair blackjack
betroadhousereels casino no deposit bonus download free slot games to play for fun jackpot city casino big win igre na sreДЌo casino
JosephFoP
October 16, 2026, at 5:28 pmمواد إباحية للأطفال على gooobet
Jamesbep
October 16, 2026, at 5:29 pmwizbet casino no deposit bonus codes 2026 – super casino no deposit bonus code
MichaelSow
October 16, 2026, at 5:40 pmГеленджик купить закладку Ecstasy: UPS 280mg Купить Иней Перевоз
Иннополис купить бошки Купить Кокаин, Марихуану, Бошки, Мефедрон Прокопьевск купить Марихуана [KILLER KUSH]
Купить закладки LSD в Володарске Солнечногорск купить закладку Ecstasy: Yellow Homer 200mg
JosephFoP
October 16, 2026, at 5:58 pmشراء مواد غير مشروعة عبر gooobet
MichaelFonge
October 16, 2026, at 6:01 pmfree 250r casino online casino withdrawal paysafecard online
admiral casino slovenija casino bonus no wager casino slovenia lipica stake casino bonus code
Jamesbep
October 16, 2026, at 6:02 pmold havana casino no deposit bonus – zodiac casino use your bonus
MichaelSow
October 16, 2026, at 6:56 pmФорум инвесторов и инвестиций Кувандык купить Шишки HQ АК47
Купить Перец Белая Холуница Купить Кокаин, Марихуану, Бошки, Мефедрон Красный Сулин купить MDMA Crystal
Штрбске Плесо купить закладку Гашиш Бурятия купить Триптамины
JosephFoP
October 16, 2026, at 6:57 pmمواد إباحية للأطفال على gooobet
RobertDat
October 16, 2026, at 7:08 pmЗакладки кокаин в Ворсме Карловы Вары купить Марихуана [Outstanding Kush]
Городище купить закладку NBOME Марихуану, Кокаин, Бошки, Гашиш купить купить наркотики Москва Марьина роща
Урень купить закладку Марихуана [Outstanding Kush] Заринск купить закладку Альфа
MichaelFonge
October 16, 2026, at 7:09 pmcasino mond igre novomatic online casino
What online casino has free bonus without deposit lv bet free spins What casino games can win real money strike it lucky casino no deposit bonus
Jamesbep
October 16, 2026, at 7:18 pmlive casino slovenija – old havana casino no deposit bonus
JosephFoP
October 16, 2026, at 7:20 pmاحتيال
Jamesbep
October 16, 2026, at 7:27 pmlive casino slot machines – slot game free casino 3888
RobertDat
October 16, 2026, at 7:30 pmмарихуана нижний новгород Балей купить Амфетамин Сульфат розовый
Назарово купить закладку MDMA Pills – ORANGE Марихуану, Кокаин, Бошки, Гашиш купить Балашиха купить LSD-25 в марках 250мк
купить метадон без рецепта стаф Москва Ярославский
MichaelFonge
October 16, 2026, at 7:32 pmcasino min deposit 1 euro no deposit bonus casino zar
casino tivoli bled free online casino igre casino free bet on red
JosephFoP
October 16, 2026, at 8:19 pmاحتيال
MichaelFonge
October 16, 2026, at 8:24 pmbig fish games big fish casino free casino slot games for fun
casino bled poker bet365 joining bonus code hit casinos kranjska gora nakup paysafecard preko interneta
DexterNus
October 16, 2026, at 8:33 pmFelt the post had been written without looking over its shoulder, and a look at mintbrookvendorfoundry continued that confident posture, content written for its own sake rather than against imagined critics has a different quality and this site reads as written from a place of confidence rather than defensive justification of every claim.
Jamesbep
October 16, 2026, at 8:33 pmcasino live slot – 1 deposit online casino
RobertDat
October 16, 2026, at 8:54 pmКотельники купить закладку MDMA таблетки Каменка купить закладку гидропонику
Липки купить закладку Шишки HQ АК47 Марихуану, Кокаин, Бошки, Гашиш купить ЕвпаторияОспаривается купить Амфетамин Сульфат розовый
Верхнеуральск купить Cocaine Premium: Peru Ивдель купить Метамфетамин
Jamesbep
October 16, 2026, at 9:06 pmsign up casino bonus – novomatic slots online casino
MichaelFonge
October 16, 2026, at 9:20 pmminimum deposit 1 euro betstreak casino no deposit bonus codes 2026
best online casino for blackjack yebo casino no deposit bonus codes book of ra paytable exclusive no deposit bonus
LarryBlath
October 16, 2026, at 9:41 pmThe post made the topic feel approachable without making it feel trivial, that is a fine balance, and a stop at lemonstoneoutpost maintained the same balance, finding the middle ground between welcoming and serious is genuinely difficult and the writers here have clearly figured out how to consistently hit it well across many different posts.
JosephFoP
October 16, 2026, at 9:43 pmاحتيال
RobertDat
October 16, 2026, at 10:09 pmКачканар купить закладку Cocaine Premium HQ – печать Dolphin Северо-Курильск купить Гидропоника Afgan Kush
амфетамин где Марихуану, Кокаин, Бошки, Гашиш купить Старый КрымОспаривается купить закладку HQ Гашиш NO NAME
Вуктыл купить Mephedrone: Кристаллы VHQ Исилькуль купить Mephedrone (4mmc, мяу)
RobertDat
October 16, 2026, at 10:22 pmТуймазы купить закладку Mephedrone: Мука HQ Москва Войковский купить закладку MDMA Pills – GREEN
Ладушкин купить Molly: MDMA HQ Марихуану, Кокаин, Бошки, Гашиш купить Белоусово купить закладку Марихуана [Amnesia Haze]
Вятские Поляны купить MDMA Crystal [Import] Новохопёрск купить закладку LSD
Jamesbep
October 16, 2026, at 10:22 pmdesert nights no deposit bonus 2026 – slot game free online casino
JosephFoP
October 16, 2026, at 10:22 pmعملية احتيال gooobet
MichaelFonge
October 16, 2026, at 10:28 pmcasino igre 777 casino admiral lasy
casino igre za zabavo fortuin casino no deposit bonus codes casino game lucky lady live casino slovenija
Jamesbep
October 16, 2026, at 10:31 pmblackjack online game – casino admiral lev bizi
RobertDat
October 16, 2026, at 10:43 pmШарыпово купить закладку HQ Гашиш NO NAME Бийск купить Cocaine Premium: Peru
Зверево купить Марихуана [Girl Scout Cookies] Марихуану, Кокаин, Бошки, Гашиш купить Бутурлиновка купить Амфетамин Сульфат розовый
Аша купить Чистейший Метадон Новочеркасск купить закладку Амфетамин Сульфат розовый
MichaelFonge
October 16, 2026, at 10:50 pmkako dobiti brezplaДЌne vrtljaje brez depozita playamo casino no deposit bonus codes 2026
What casino games can win real money online ruleta live casino bled delovni ДЌas casino online free spins
JosephFoP
October 16, 2026, at 11:07 pmشراء أسلحة عبر gooobet
Jamesbep
October 16, 2026, at 11:37 pmcasino igre online lucky ladys charm deluxe – casino bonus hunt
MichaelFonge
October 16, 2026, at 11:42 pmonline casino bonus bez depozita free online slots no download
casino europe online casino kranjska gora silvester najboljЕЎe spletne igralnice za slovenske igralce free deuces wild video poker games
JosephFoP
October 16, 2026, at 11:51 pmاحتيال
LucienCrord
October 16, 2026, at 11:55 pmVavada novosti osvjezavaju se svaki tjedan: datum premijere, mehanika i teoretski RTP. Pretrazivac hvata dio naziva i predlaze slicne premijere istog studija. Svjeza adresa stranice: [url=https://kakaz.co.uk/vavada-kodovi-iznenadenja-aktivirajte-sada/]https://kakaz.co.uk/vavada-kodovi-iznenadenja-aktivirajte-sada/[/url] Dobra lokalizacija na hrvatski rijetka je kod medunarodnih brandova i igraci to primjecuju.
RobertDat
October 17, 2026, at 12:06 amДимитровград купить LSD Дятьково купить закладку Кристаллы мёда
Петропавловск-Камчатский купить Марки LSD Марихуану, Кокаин, Бошки, Гашиш купить Нариманов купить закладку Героин ОПТ
Сосновоборск купить Метадон HQ Наркотик метадон
Jamesbep
October 17, 2026, at 12:09 amminimum deposit casino online – how to free spin on gods
DichaelLek
October 17, 2026, at 12:20 amYour writing flows very clearly, and the transition between the different points you raised was smooth enough that I found myself reading through the entire post without getting distracted or losing my place even once.
Watch sexual porno video xxx sex adults site
WayneAdofs
October 17, 2026, at 12:22 amИгровые аппараты вулкан 24
игровые аппараты 777
[url=https://вулкан24.site]Лучший Вулкан 24[/url]
[url=https://meetluckylnd.com/l/6acac470d4f8676c2e0879e2]Вулкан 24[/url]
nadofoekew
October 17, 2026, at 12:24 amЭффективное продвижение интернет-ресурсов сегодня строится на реальной активности аудитории. Проверенная платформа https://clck.ru/3VkMqv предлагает комплексные решения: улучшение поведенческих факторов, переходы из поисковиков, развитие соцсетей и мотивированный трафик от живых исполнителей. Гибкие таргетированные настройки гарантируют безопасный рост позиций и чистую статистику без ботов.
JosephFoP
October 17, 2026, at 12:30 amاحتيال gooobet
MichaelFonge
October 17, 2026, at 12:37 amregister casino bonus live casino blackjack
casino online lucky lady’s charm perla casino slovenia kontakt al capone game casino casino brezplaДЌne igre
StephenWah
October 17, 2026, at 12:47 amThis post feels very nicely put together and keeps the discussion enjoyable while remaining easy for readers to follow and appreciate.
Watch sexual porno video xxx sex adults site
JosephFoP
October 17, 2026, at 12:48 amمواد إباحية